
‘Year of the Broker’ Gives Way to ‘Year of the Reduced Commission’
February 21, 2016 Many brokers just starting out in the alternative funding space may be in for a rude awakening. It’s not that the ‘Year of the Broker’ is over, per se, but 2016 certainly represents a new chapter for newbies—one in which getting rich quick and succeeding over the long-haul will be much more difficult.
“It’s the ‘Year of the Leader’ now. Fresh brokers coming into our space will have to work harder to set themselves apart, and it will be harder for many of them to make the money they once did,” says Amanda Kingsley, chief executive of Sendto, a Palm Bay, Florida-based firm that assists companies in the alternative finance industry with referral marketing and operational growth programs.
Funders today remain hungry for deals and are still paying relatively high rates to bring in new business. Yet there are several competitive realities putting a damper on a new broker’s earnings power.
“A few years ago, individual brokers could be making $20,000 or even $40,000 a month. Now those numbers are much more difficult to reach unless brokers have a unique lead generation method or their own money to participate in the deals,” says Zachary Ramirez, a vice president and branch manager in the Orange, California office of World Business Lenders, a New York-based lender.
Most funders today allow brokers to charge merchants between 8 and 12 points above the buy rate, with some allowing as high as 15 to 20 points, according to industry participants. But to win business amid a flurry of competition, brokers are being forced to take a lower cut on many deals. Not only are there more brokers to compete with, but merchants are also savvier—and more price-conscious—about alternative funding products than they were several years ago.
For higher quality deals, there’s another force at play driving down what sales reps can earn. That’s because a handful of large funders are instituting caps on what brokers can charge top-quality merchants. “They want to make sure that the price that’s charged to the merchant is fair,” says Stephen Sheinbaum, founder of Bizfi, a New York-based funder that has not instituted these caps.
Together, these competitive realities mean that sales reps, on average, are making much less than they did a few years ago. For example, on high quality deals, brokers might only be able to make 3 to 8 points per deal on average. For lower quality deals, on the other hand, brokers might make as much as 15 to 20 points.
So far, the changing economic tide hasn’t discouraged new sales reps from jumping in. In fact, the market is still hot for new brokers who continue to pour into the market at a torrid pace, buoyed by rampant media attention and aggressive advertising by funders and large brokerage houses. “I think it’s even worse now,” says John Tucker, a solo broker since 2009 who also blogs for DeBanked. “They’re signing up anybody with a heartbeat and a pulse.”
Clinging to Misperceptions
Despite the overcrowding issue, industry watchers expect new brokers will continue to flood in as alternative funding continues to gain traction. Many of these new brokers, however, won’t be around very long. That’s because many of them are coming into the space, especially from other sales-oriented jobs, thinking it’s easier than it is. “I think many people are going to come into the space, fail and leave bloodied and bruised,” says Ramirez of World Business Lenders.
Indeed, there are many new brokers who are still holding on to outdated notions about the business. Some are primed to think that they can easily make 10 points on a $100,000 deal and if they do that once a month, they have the potential to make $120,000 a year. “It’s just not as easy as it’s promoted to be,” says Tucker, who owns 1st Capital Loans in Troy, Michigan. Even Tucker, a seasoned broker, frequently has trouble connecting with merchants nowadays because they are inundated with sales pitches. They’ll hang up on him as soon as he makes it clear he’s a broker because they are getting so many calls from competitors, he says.
William Ramos, owner of Right Away Funding in Phoenix, Arizona, recently worked with a new broker who was convinced he was going to make $5,000 a week from the get-go. Ramos tried to manage his expectations by explaining he’d first have to learn the business and be persistent if he hoped to make that kind of money.
 Ramos says the broker took his advice by asking lots of questions and working hard over the next six months. He’s not making what he had originally hoped, but he is up to about $5,000 a month, says Ramos, the former president of Staten Island, New York-based Supreme Capital Group, which he sold in 2015 to open a new firm.
In talking to new brokers, Nathan Abadi president of Excel Capital Management in New York, a lender and MCA funder, also sees a lot of misconceptions about what they think they can make and how easy it will be. It becomes problematic when the reality doesn’t match up with their expectations. For instance, he recently hired a used car salesman who worked for his company for about two months before they parted ways. The broker thought that because he had sold so many cars in the past, he could easily apply that to alternative funding. But he didn’t want to take the time to thoroughly learn about the new product set. He was just trying to ink deals based on cost, which is no longer a viable strategy, Abadi explains. “Customers know what the rates are. They’re not just applying with one person,” Abadi says.
The first month, the new broker closed a $175,000 deal based on a lead he was given and with Abadi doing the bulk of the legwork. After that, the broker got a few more deals, but he couldn’t do it on his own without significant support from the firm. A big problem was that he didn’t understand the math behind the deals he was pitching. “If merchants ask you a question and you can’t answer it properly, you’re done. The deal’s over. Not enough people are taking the time to understand the market as a whole,” says Abadi, whose firm is in the process of hiring new brokers for its internal sales force.
Edward Siegel, founder and chief executive of Fundzio LLC, a funding company in Fort Lauderdale, Florida, says he still sees plenty of new brokers who come into the business believing they can easily close a deal for $50,000, make 10 points and sustain that type of income. “The market has changed. The cost of capital has gotten a lot lower for the customer, and since there are more brokers in the marketplace they are willing to take a lesser amount just to get the deal to the finish line,” he says.
A lot of brokers come into the industry all gung ho and then flounder when they see how hard it really is. Siegel says he’s seen them submit deals for a few months and then realize they were living a pipe dream and leave the industry. “It’s not easy, especially in a competitive marketplace, especially when 10 other brokers might be knocking on that same guy’s door,” he says.
Nearing the breaking point
Andrew Reiser, chairman and chief executive of Strategic Funding Source, a New York-based funder, says that many brokers are operating under a false sense of security. “We’re in a strong economy in our space largely because of lack of other available sources of capital from larger institutions. When a market is very forgiving, mistakes are easily absorbed and swept under the carpet.”
He believes it’s going to get even harder for brokers over time, likening the situation with brokers today to that of stockbrokers a few decades ago. People used to be inundated with calls from stockbrokers at firms of all sizes about this stock or that one. Now many small brokerage houses have disappeared and larger firms have moved away from cold calling. Instead they are focused on money management and proving their prowess as specialists.
“You can’t be all things to all people serving a market this size,” he says.
Survival Strategies
Kingsley of Sendto says she receives many questions from new brokers about how to compete effectively, and it’s not an easy answer. Having a niche product, though, can help. “If you can learn how a particular industry works along with appropriate deal placement, you can develop a really good client base. It helps when presenting your clients to funding companies and you will build a more professional relationship,” she says.
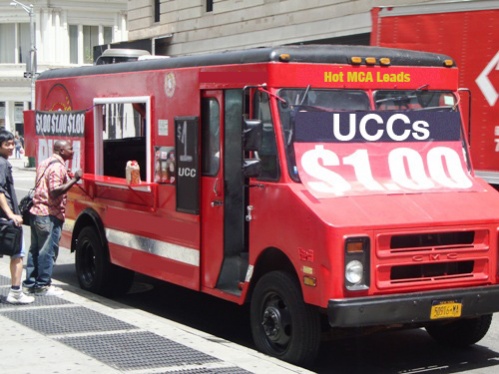 Tucker, the broker with 1st Capital Loans, notes that UCCs and Aged Leads are outdated marketing tactics and says most new brokers don’t have enough industry knowledge to critically think to create new strategies for survival. “All they will end up doing is burning through the little capital that they do have and be out of the business within 12 to 18 months,” he says.
Having good training is critical for new brokers to survive, according to Mike Andriello, president of Cushion Capital Corporation in Poughkeepsie, New York. “I think that if brokers focus on the nature of the industry, actually pick the business owners’ minds and learn their business as best as they can, they will have a lot of success. It’s not all about making the biggest commissions; it’s about having the biggest client book,” he says.
Ramirez of World Business Lenders believes brokers can do better for themselves long-term by syndicating because it’s a way to make more money. “I don’t think it’s a long-term strategy if a broker’s not participating in his own deals,” he says.
 Granted, some funders make it easier for brokers to participate than others do, but Ramirez believes brokers should seize opportunities to earn interest income over the life of the loan. So, for instance, on a $100,000 loan, instead of earning a $20,000 commission upfront, a broker might be able to apply that money to the deal and earn $26,000 or $28,000 over the life of the loan.
Of course, this strategy won’t work well for brokers living paycheck to paycheck. “But if you don’t need the commissions right away, you can roll the commissions into deals and increase your earnings exponentially,” he says. “Because of rising acquisition costs and decreased commission averages per deal, being forced to participate, or syndicate, is the natural evolution.”
Gearing for the Future
To be sure, industry watchers believe there is still ample opportunity for new brokers with drive and ambition to enter the space. “Successful brokers will always have a place in the ecosystem,” says Sheinbaum of Bizfi.
But there’s a general consensus that from now on these brokers will have to work harder than they have in the past to thrive. Says Andriello of Cushion Capital: “2016 will be the year of who was smart enough and made the right business moves to stay progressing and growing. It will also be the year a lot of funders and brokerage firms close shop.”
Over time, the changing economic reality will continue to set in. While it will be harder for individual brokers, it’s best for the industry when new sales reps understand the realities of the market and how to compete effectively. “You want the smartest people in the space. The more well-educated they are about the products and the processes, the better off everyone is,” Sheinbaum says.
Despite everything, it’s still a great time to be getting into the industry, provided you have the right mindset and proper resources behind you, according to Ramos of Right Away Funding. “If you’re just coming in and you just want to collect your weekly check, now’s not a good time to be a broker. It’s a great time for people who are hungry, motivated and determined to make something out of it.”
Did BFS Capital Trade Going Public for a Bigger Credit Line?
February 4, 2016 BFS Capital secured a $165 million credit line through Wells Fargo Capital Finance with an additional increase of up to $250 million. This agreement extends the former line of $135 million and will help the Florida based small business lender to service merchants in North America.
The company had an eventful 2015 — In July last year, it funded $1 billion worth of deals and acquired New York-based financial services firm Entrust Merchant Solutions in August. It also rebranded itself from Business Financial Services Inc.
Interestingly enough, as deBanked reported in September last year, the company filed for an IPO and submitted a draft registration statement on Form S-1 with the Securities and Exchange Commission (the “SEC”) relating to the proposed initial public offering of its common stock.
The Ghost of Second Source Funding Has Lost a Desperate Court Battle
February 4, 2016The notorious company returned from the dead for one last final stand
 For many veterans of the merchant cash advance business, the Second Source Funding name is something they’d rather forget. They were perhaps the largest funding ISO in the industry between 2006 and 2008. And as plenty of ex-employees will tell you, the story ends badly.
Meir Hurwitz, a co-founder of NY based Pearl Capital, immortalized the Second Source years through a Bloomberg exposé about how his own company rose and sold for $40 million. In his tale, he claimed that Second Source founder Sam Chanin still owed him $2 million for the work he performed there. For Hurwitz, the falling out set the stage for the company he would go on to start. For other employees, it was the beginning of a grudge that would stick around for almost a decade.
Chanin has gone so far as to admit on his blog that he became known as “the guy who ripped them off and didn’t pay their residuals.” According to him, it wasn’t his fault. Court records do show Second Source Funding filing a complaint against Cynergy Data back in 2009 for $60 million in damages. Cynergy was the processor behind their lucrative merchant services operation and ultimately where the residuals they paid out to sales agents originated from. The case was dismissed in October of that year because Cynergy declared bankruptcy.
Effectively shuttered by the circumstances, the only reminder of what had once been, was another lawsuit filed by Second Source in September 2012 against a company (and more than 30 co-defendants) that acquired Cynergy Data’s assets. In October of 2009, Cynergy’s assets were reportedly sold to The Comvest Group for $81 million. In the complaint, Second Source sought at least $50 million from them in damages.
It has been approximately seven years since Second Source’s days ended, sources estimate. Users on industry forums were already speaking of the company in the past tense as far back as early 2009. The Second Source website no longer even exists. While ex-employees have long urged old peers to move on from those days, others have been forced to confront their demons.
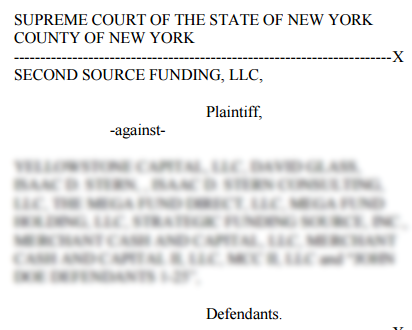 THE GHOST OF MERCHANT CASH ADVANCE PAST
In September of 2014, the very same Second Source Funding emerged through a complaint filed in the Supreme Court of New York against Yellowstone Capital, LLC, 8 named co-defendants and 25 John Doe defendants. Seeking damages in the astounding amount of $360 million, Second Source alleged that Yellowstone’s co-founders stole their “revolutionary business model” of which they describe as using “Independent Sales Offices to leverage economies of scale in marketing and selling a bundle of financial services, including credit card processing and cash advances.” As a result of that and other claims, they were allegedly the reason for “Plaintiff SSF going out of business.”
The ensuing battle was probably one of the most contentious litigations the industry has ever experienced, at least from what can be seen on the docket. In one publicly filed exhibit introduced by Yellowstone, was the draft of a complaint that the plaintiffs had allegedly sent them that named more than 40 defendants. It reads like a yearbook of the merchant cash advance industry in 2009.
Other exhibits are packed with plenty of Second Source era nostalgia, including copies of the entrance exams given to new hires. One test question embodies the culture of the time, when it asked applicants:
What movie is this quote from, “Put the coffee down, coffee is for closers?”
While motions and cross motions at times appear to venture into the arena of insanity, especially considering Second Source went out of business a long time ago, deBanked has learned that Yellowstone was vindicated this week in a decision that dismissed all the claims with prejudice. That means they can’t have a do-over. The suit lasted 17 months.
deBanked has been quietly following the docket for over a year. We did not ask either party to comment on the decision for the reason being that Second Source may be considering an appeal, or at least they alluded to that in the court transcripts.
 In the meantime, the ghost of Second Source reminded a few people in the merchant cash advance industry that the antics of 2006-2008 were more than just tall tales told by grey beard Wall Street guys. Back then the coffee was still for closers only. And back then, the game was so different that some people would still be feeling the effects of it a decade later.
THEN AND NOW
Yellowstone Capital was one of the first merchant cash advance companies to experiment with the ACH payment method. Today, they originate nearly a half billion dollars a year in funded deals.
If you want to see just how much has changed since the Second Source days, check out this answer to the Second Source exam in 2008.
Q: If a merchant is getting an advance from MCA and can’t switch processors, what can the agent offer this merchant?
A: Lock box
It’s amazing to think that ACH was inconceivable at the time. Touched by ghosts indeed…
Industry Trade Group Coming of Age: The SBFA is Becoming More Political
February 1, 2016By hiring an executive director, the Small Business Finance Association hopes to achieve at least two goals – taking a step toward becoming a full-service trade group and providing a public voice for the alternative finance industry.
Stephen Denis, formerly deputy staff director of the U.S. House Committee on Small Business, went to work in the new role in mid-December, setting up shop with his cell phone and laptop in a Washington, DC, area coffee emporium. He’s the SBFA’s first full-time employee.
Hiring Denis, who also has association experience, represents “the next evolution” of the trade group, according to David Goldin, SBFA president and Capify’s founder, president and CEO.
 The SBFA, which got its start in 2008 as the North American Merchant Advance Association, changed its name last year because members have added small-business loans to the their merchant cash advance offerings. Although the trade group’s not exactly new, it has plenty of room to grow and its leadership and members seem open to change.
“The goal is to start from scratch and take a look at everything the association is doing,” Denis told deBanked, “and to really build this out to a robust group that represents the interests of small businesses.”
Denis appears optimistic about pursuing that goal. He’s a native of the Boston area and a Harvard University graduate whose first job out of school was as an aide to Republican Sen. John E. Sununu of New Hampshire. After three years in that position, he took a job for two years with a UK-based trade association, traveling frequently to London to inform the group of Congressional action in the United States.
From there, Denis went on to become director of government affairs and economic development for the Cincinnati Business Committee, a regional association that included Fortune 500 companies among its members. After two years in that role, Denis joined the staff of Rep. Steve Chabot, R-Ohio, moving back to Washington and serving as the congressman’s deputy chief of staff during a five-year stint that ended when he joined the SBFA.
While working for Chabot, Denis also became deputy staff director of the House Committee for Small Business, the No. 2 position there, and he has held that job for the last three years. The committee’s tasks include learning as much as they can about small business, including financing, and using the information to advise members of the House on policy initiatives.
The experience Denis has amassed in government should serve the association well because his duties include briefing federal legislators and regulators on how the alternative-finance business works. With Denis as spokesperson, the industry can speak to government with a single voice, Goldin asserted.
“We are going to be aggressive in our outreach to legislators and regulators as well as be active reaching out to local, state governments,” Denis said. The SBFA will “work with other trade groups and small business groups to promote our mission to ensure small businesses have alternative finance options available to them.”
Until now, too many players from the alternative finance industry have been vying for lawmakers’ attention, Goldin said. To make matters worse, some of those seeking to influence government in hearings on Capitol Hill are brokers instead of lenders and thus may not have a perfect understanding of risk and other aspects of the business, he maintained.
“We’re hearing that there are people trying to be the voice of small-business finance that either don’t have a lot of years of experience or they’re not telling the whole story,” Goldin said. “We want to make sure the industry’s represented properly.”
Denis can draw attention away from the “noise” created by unqualified voices and focus on information that Congress needs to make reasonable decisions about the alternative finance business, Goldin maintained.
Besides getting the word out in Washington, the SBFA hopes to convey its message to the general public on “the benefits of alternative financing,” Goldin said. At the same time the group can help make small business owners aware of the finance options, Denis added.
 Asked whether hiring Denis marks the beginning of an effort to lobby members of Congress for legislation the association deems favorable to the industry, Goldin said only that additional announcements will be forthcoming.
Meanwhile, updated “best practices” guidelines might be in the offing to help industry players navigate the business ethically and efficiently, Goldin said. A set of six best practices the association released in 2011 included clear disclosure of fees, clear disclosure of recourse, sensitivity to a merchants’ cash flow, making sure advances aren’t presented as loans and paying off outstanding balances on previous advances.
Addressing other possible steps in the association’s growth, Goldin said the group doesn’t plan to publish an industry trade magazine or newsletter. However, a trade show or conference might make sense, he noted.
Denis said he and the board had not discussed the possibility of a test, credential or accreditation to certify the expertise of qualified members of the industry. However, associations often establish and monitor such standards, so it would be reasonable for the SBFA to do so, he added.
The association might establish a Washington office, Goldin said. “We’ll look to Steve for his thoughts and guidance on that,” he observed. Denis seems amenable to the idea. “Down the road, we would love to open an office and hire more people,” he said.
In Goldin’s view, all of those moves might help the rest of the world comprehend the industry. Understanding the industry requires taking into account the cost of dealing with risk and business operations, he said.
Placing a $20,000 merchant cash advance, for example, requires a customer-acquisition effort that costs about $3,000 and a write-off of losses and overhead of about $4,000, Goldin said. That’s a total of $27,000 even without the cost of capital, he maintained.
“Most people don’t understand the economics of our business,” Goldin continued. The majority of placements are for less than $25,000, he said, characterizing them as “almost a loss leader when you factor in the acquisition costs.”
While spreading that type of information on the industry’s inner workings, Denis will also conduct the day-to-day for the not-for-profit’s affairs. The association’s board of directors will continue to set policy and objectives.
Members elect the board members to two-year terms. Current board members are Goldin; Jeremy Brown of Rapid Advance, who’s also serving as the group’s vice president; John D’Amico, GRP Funding; Stephen Sheinbaum, Bizfi; and John Snead, Merchants Capital Access.
Member companies include Bizfi, BFS Capital, Capify, Credibly, Elevate Funding, Fora Financial, GRP Funding, Merchant Capital Source, Merchants Capital Access (MCA), Nextwave Funding, NLYH Group LLC, North American Bancard, Principis Capital, Rapid Advance, Strategic Funding Source and Swift Capital.
Companies pay $3,000 in monthly dues, which Denis characterizes as inexpensive for a DC-based trade association.
Membership could spread to other types of businesses, Denis said. “I’d like to expand the tent to other industries,” he noted. “The association is trying to represent the interests of small business and make sure they have every finance option available to them.”
But a key purpose of the trade association is to provide a forum for members to come together as an industry, Denis said. “We’re thinking big,” he admitted. “We hope that all members of the marketplace will want to become a part of it.”
January/February 2016 Cover Teaser
January 25, 2016The January/February 2016 issue of deBanked magazine is set to ship soon. Can you guess who is on the cover???
If you don’t already get the hard copy of our magazine, you can SUBSCRIBE HERE FREE. To review previous issues in HTML or PDF, click here.
Platinum Rapid Funding Group Sets Annual Funding Record
January 25, 2016Platinum Rapid Funding Group, a Long Island, NY based merchant cash advance provider, set a new personal-best funding record last year, according to company VP of Partner Relations Corey Cicero. Through direct and indirect channels, the company originated more than $100 million worth of funded deals during 2015.
The growth has led to what seems like a never-ending hiring spree at their Uniondale office. Cicero told deBanked that they plan to beat their 2015 figures this year by a wide margin. “We are still hiring,” he said.
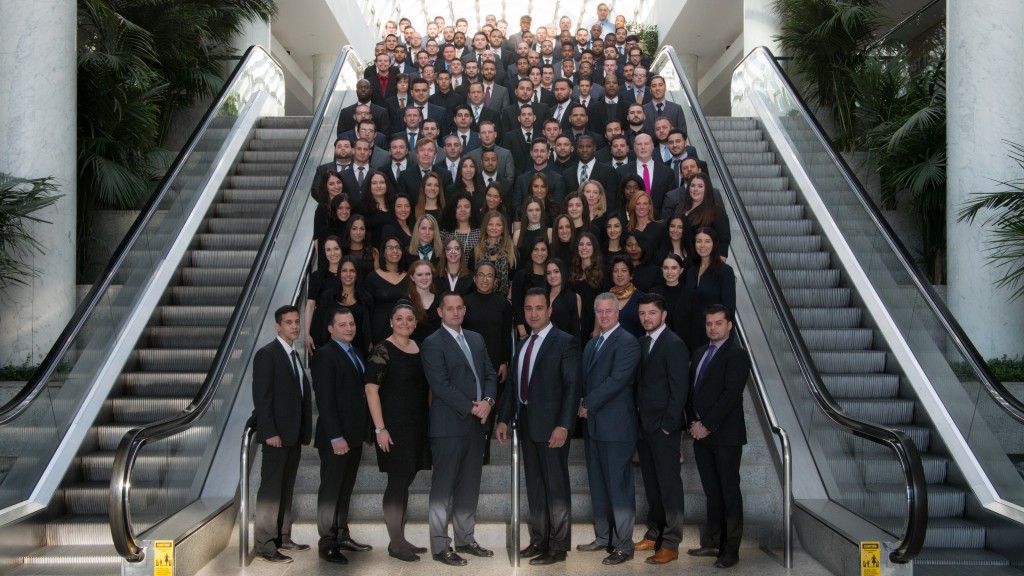
deBanked visited their office back in September and as evidenced by the above photo, they are not a small shop.
Should Funders Pay Lifetime Renewals?
January 24, 2016OPINIONS ARE LIKE A-HOLES RIGHT?
We all know what they say about “opinions” right? They (opinions) are basically like a-holes and everybody has one. I’ve stated a lot of opinions here on deBanked over the last couple of months, while some might agree and others disagree, I always try to provide educated opinions to separate commentary from the generic pack of people blurting out comments across industry forums and media publications that might not have firsthand experience on the front lines.
With that being said, it’s in my sole opinion that every funder/lender should offer their independent brokers lifetime renewal compensation despite new deal volume.
 BROKER AGREEMENTS SEEM TO CHANGE ON A WHIM
I’ve been reselling the merchant cash advance and alternative business loan products since November 2009, however, the current program structures/agreements of my funders and lenders look totally different today than they did in the beginning.
It’s almost as if a new agreement is created every 12 – 18 months with similar conditions, but certain terms might have changed, including the compensation of renewals.
Some funders and lenders will start without any provisions related to renewals, basically as long as the client continues to renew, then you will be allowed to collect commissions off the client. But later on down the line, some funders and lenders will change provisions and require certain levels of new deal volume in order to be compensated on renewals going forward. Most broker agreements have terminology listed that states that the funder/lender can change the program at their discretion, however, I believe that at no point in time (other than for particular circumstances of fraud or ethics violations) should a funder take away a broker’s renewal compensation as whatever “good” it’s supposed to be doing (which I still can’t think of any), I believe it does far more damage in return.
YOU CAN’T CLOSE WHAT YOU CAN’T GET APPROVED
Sometimes a broker doesn’t fund a deal within 3 – 12 months because the funder can’t approve any of the submitted deals. If the broker is like myself, I’m going to pre-screen all new applications to see if it fits the underwriting criteria before submitting it, as submitting applications that are outside the criteria does nothing but waste valuable underwriting resources. If they are a somewhat conservative funder, a lot of times a broker just might get too few applicants to fit the box.
WHAT DID YOU ACTUALLY SPEND ON MARKETING?
Funders and lenders receive free marketing from brokers because they bring them the deals, so what is the big deal about continuing to pay renewal compensation despite new deal volume? They don’t have to worry about taking the risk of putting marketing capital up on the table with a potential of no return. The person who puts up the capital is the broker, and they should be compensated for the lifetime of the client regardless of new deal volume.
As an independent broker, the individual is a part of the Mom and Pop Network, which is just a group of random brokers who resell for free (100% commission). Not only are funders/lenders receiving the free marketing from the resellers, but they are also receiving free data to utilize in any potential “big data” valuations for sell-off, or “big data” analysis for better market segmentation. In addition, if the broker’s portfolio of merchants (even if it’s just one merchant) didn’t default or the default rate is very low, what is the justification for cutting off the broker just because there was no new deal funded?
RENEWALS ARE THE LIFEBLOOD OF THE BROKER’S INCOME
Once upon a time, during the very early days of MCA, the product was pretty much a one-off project. A merchant had an emergency, they sold off a percentage of their future credit card receivables in exchange for some upfront cash today, and used the cash to address whatever emergency they were facing. If the merchant renewed, it was usually one time (twice if you were lucky) and that was it. Today, it’s a different situation if you set up your merchant based on their proper Paper Grade. Merchants are renewing back-to-back, a lot of times for 3 to 5 years (or more) in a row, which means that the product is becoming more of an integrated portion of their business (similar to the MCA’s Kin A/R Factoring) rather than a one-off occurrence. This means for a broker, there’s a lot of money to be made off of their MCA portfolio going forward and the entire point is to build your portfolio up to a particular size, where you can just “sit back” and solely manage the renewals of the portfolio without being required to continually produce new deals by spending more on marketing.
Take a broker with a portfolio of 25 merchants who renew just about every 6 months (twice a year) with an average funding of $75,000 with 5 points commission per deal. That alone is $3.75 million a year in funding volume and almost $100,000 per year in income, solely off the renewal portfolio. If the broker maintains this portfolio for 10 years in a row, that’s almost $38 million in funding volume and close to $1 million in income. Why on Earth would you want to even threaten to cancel a broker out of the deal when again, it was their ingenuity, rapport building skills and sales skills that are the foundation of the clients coming to the funder to begin with, as well as continuing to renew back-to-back?
YOU ARE ASKING FOR YOUR MERCHANTS TO BE FLIPPED OR STACKED
The broker is the one who has the original relationship with the merchant, thus, the merchant more than likely has more rapport with the broker than they have with anyone in the funder’s organization. Thus, cutting off the broker from the renewal compensation might do nothing but just cause the merchant(s) to be stacked or flipped to another funder/lender.
TELL ME WHICH BROKER IS MORE VALUABLE? BROKER A OR BROKER B?
Okay, so tell me which Broker is more valuable? Is it Broker A or Broker B?
– Broker A: Over the course of one year, Broker A brings in 15 new merchants, with only 4 of those merchants renewing once because the broker didn’t price the merchants in their proper Paper Grade and thus, a competitor stole them away at renewal. This produces a total of 19 advances (new/renewal) and let’s say with the average funding being $50,000 you are looking at volume of $950,000.
– Broker B: Over the course of one year, Broker B brings you only 8 new merchants, but 3 of them renew 4 times back-to-back (12 additional advances), 2 of them renew 3 times back-to-back (6 additional advances), 2 of them renew 2 times back-to-back (4 additional advances), and 1 of them renew only once, for a total of 31 advances (new/renewal). Keeping the average funding at $50,000 you are looking at volume of $1,550,000.
Broker B supplied fewer new deals than Broker A, but Broker B provided an overall higher level of production based on the rapport and proper structure they established with their clients that produced more renewals and advances in total for the funder. Seeing as though in our industry, when funders count their “total volume funded” they include both new and renewal volumes, how can it be that Broker B is not more valuable to a funder than Broker A is? Not saying that Broker A isn’t valuable, but based on potentially cutting off renewal compensation due to a lower amount of new deal volume, they would potentially be cutting off the Broker that offers more value over time.
THE FINAL WORD
Why on Earth would a funder or lender want to kick out a competent broker by cutting off their renewal portfolio? What does it solve to cut off a competent broker, with a low (or no) default rate, just because they didn’t bring in newly funded deals during the previous 3 – 12 months? What does that solve? Does cutting them off somehow produce more margin for the funders? More market share? Savings in some sort of area? As mentioned, the broker is likely to flip the merchants or stack the merchants when this happens, which again, does nothing for the funder in terms of providing any type of benefits or value.
The only justification for cutting off a broker is when they are engaged in unscrupulous acts. But cutting off competent brokers just because they didn’t fulfill some insane new deal volume policy, makes absolutely no sense because at the end of the day, cutting off the brokers will be like cutting off the funder’s relationship with the merchants as well. With the parade of new funders looking to grab market share, what better way to gain it than to partner with competent but dejected brokers, who just got their renewal compensation cut off for not fulfilling some insane new deal policy?
To Syndicate or Not to Syndicate?
January 20, 2016 Someone once asked the question of, “To love or not to love?” But I believe soon every broker will have to ask the question of, “To participate or not to participate?” Is it time we all get into the game?
THE YEAR OF THE BROKER OR THE YEAR OF ROSY PROMISES?
Debanked writers such as Sean Murray, Ed McKinley and myself, referred to 2015 as the Year of The Broker, as a stream of new brokers continued to rush into our space to take advantage of the perceived opportunities.
THE YEAR OF PARTICIPATION?
For experienced brokers, I’ve written two pieces so far here on deBanked in relation to the broker’s future. I’ve talked about how I believe the future of our industry will be dominated by Strategic Networks and those who utilize these networks efficiently will not just be the dominant players going forward, but they will be pretty much the only “real” players going forward. I also talked about how success in our industry is based mainly on leveraged resources and networks, rather than having some sort of “superior” selling capability.
But with that being said, I wanted to use this article as a way to add to this discussion of the future by outlining my recommendation that experienced brokers “get into the game” when it comes to syndication and deal participation. DeBanked reported back in April of 2015 about how Strategic Funding Source’s syndication network of over 200 partners (at the time) invested over $260 million of their own capital into funded deals. This level of investment, according to the reporting, helped amass significant wealth for the 200 syndication partners that participated. If 2015 was the Year of The Broker, could 2016 be the Year of Participation?
IT’S NOT THE SAME ANYMORE
It’s no longer 2000 – 2013, when quite frankly a broker could amass great income by just strategically utilizing the Uniform Commercial Code (UCC) as a marketing model. But pretty soon the word got out and everybody rushed in to duplicate the methodology. What was once a great idea became a complete waste of marketing dollars.
UCCs are so bad today, that when you call a merchant and just mention the fact that you are from a funding company, they immediately hang up the telephone. Sometimes, I would call and before I would even have the chance to say a word, the staff member on the telephone would ask, “Are you calling about a cash advance?” Once I would reluctantly answer in the affirmative, they would of course immediately inform me to put them on the do not call list, never call again, and either in nice language or a language full of swearing, they would inform me that they aren’t interested and how I’m the 19th guy that has called them this week. This is the result of a merchant getting 20 calls a week from 20 different companies, about 20 different merchant cash advance products.
As a result, brokers are going to have to specialize in the Strategic Networks and leveraged resources that I have been discussing for nearly a year now on Debanked. We will also have to juggle the rising marketing costs and increasing pressures on pricing as our industry goes more mainstream. You might not want to operate as a full-fledged direct funder, as I understand that the investment outlay for such a task is significant. But I believe going forward, you aren’t going to be able to “make it” like you used to by solely relying on commissions from brokering deals. You are going to have to get into the game and put some money in deals not just to sustain the amount of income you were making in commissions historically, but to potentially make more money than you ever made before.
A SHOUT OUT TO WBL
Also back in April of 2015, there was a pretty popular online discussion that discussed World Business Lenders’ (WBL) new ISO/Broker acquisition program. I had a conversation by telephone with Lenny Steigman from WBL on April 21st of last year to discuss the program in detail.
One of the things that Lenny mentioned on that call was the notion of the broker’s office requiring a shift in structure in order to survive in the upcoming future. Lenny discussed that brokers who chose to continue to operate on the sidelines relying solely on commissions from brokering deals, without getting involved in some sort of equity or syndication participation, might find the future of their involvement in our space limited as continued growth through strategic networks drive the progression of the industry. I could not agree more with Lenny Steigman. It’s certainly time for a shift and one of those shifts I believe will require more experienced brokers to become syndication partners through putting up a portion of the capital to fund the merchants that they service.
GET YOUR DUCKS IN ORDER
As you prepare for this shift and look to get into the game, make sure that you have your ducks in order:
Legal Representation: This is important, you need an attorney to review your syndication agreements as well as review the legal structure of the funder you are partnering with, to make sure that all of the legal terminologies are outlined properly.
Understand The Deals You Are Funding: Know the type of client you are funding, such as if they are A Paper, B Paper, C Paper, D Paper or E Paper. Your level of risk on the deal in terms of default increases when you get into the higher risk paper grades, thus, make sure you are getting a significant enough “return” on said deals to accommodate the risk you are tolerating.
Examine Your Funder’s Finances: By syndicating, you are doing more than just investing in the merchants that you serve, you are also investing in the financial soundness of the funder you are syndicating with. Make sure your funder is not on the verge of bankruptcy, profitable, and will actually be around a year from now.
Examine Your Funder’s Operational Structure: I’ve talked about the importance of making sure you vet who you partner with in relation to being a broker. Now that you are syndicating, you most definitely make sure you are dealing with a funder that’s “proven.” The funder should have at least 2 years in business, have funded in the eight digits in terms of volume, have a proven and profitable underwriting formula, have an office full of employees, not have a significant amount of bad reviews, be in good standing with the BBB, having an actual online presence, and they should be running a professional and competent organization overall.
Round Up Your Capital: The secret of many of the wealthy has always been their unique ability to utilize the money of other people for their business investments. They find equity investors seeking a return on their capital, invest said capital with a high return and collect a management fee off of the transaction. Or, they borrow money from a creditor at a particular interest rate, invest the monies for a higher rate of return, then pay off the loan with interest and pocket the profits. Whichever way you prefer, how about you utilize OPM (other people’s money) to your advantage (leverage) as well for your participation efforts?
TO PARTICIPATE OR NOT TO PARTICIPATE?
I believe we might be entering the year of participation, which means it’s time for the experienced brokers to join in on the strategic networks which will dominate our space going forward. New entrants who don’t know the space and still can’t spell “merchant cash advance” will be in for a bumpy ride going forward, but those with the experience, it’s time to add to your industry influence by coming off of the sidelines as brokers solely, and becoming broker/syndicates in the truest form.