Articles by deBanked Staff

Georgia CDFI Offers Merchant Cash Advances
November 17, 2026Albany Community Together, Inc. (ACT!), a CDFI in Georgia, is offering merchant cash advances.
“Revenue-based financing enables a business owner to get funding by selling future revenues at a discount,” ACT! says on their website. “This funding method is non-dilutive, which means you keep all your ownership.”
ACT! says their revenue based financing offering is made possible through Ned, a San Francisco-based portfolio management fintech company, which is also facilitating MCAs and revenue-based financing programs for other state-backed organizations as well.
Per the ACT! website:
In partnership with Ned, an innovative revenue-based financing platform, we are launching a program to expand ACT!’s small business financing capabilities.
Our goals are straightforward. We aim to help Georgia small businesses grow by:
• Empowering business owners to access capital more easily.
• Enabling them to repay with flexible terms.We chose revenue-based financing (RBF) because it provides the flexibility business owners need. They can quickly get the funds they require and repay on terms that work for them.
“With RBF, the business owner repays with a set percent (%) of whatever revenues the business makes. And they don’t pay anything if the business doesn’t perform,” ACT! says.
Government-supported Organization in Arizona Offers Merchant Cash Advances
November 17, 2026“STAC’s revenue-based financing (RBF) allows small businesses to pledge future revenues for an advance of financial capital. Payments can vary depending on how well a business does and its gross revenues after receiving funding. Businesses have higher payments when they are generating more revenues and lower payments when they are generating less revenues, an arrangement that can be especially useful for seasonal businesses.”
STAC stands for Success Through Alternative Capital, a program offered by CIC, a non-profit in Arizona enrolled in the Arizona Loan Guarantee Program with support from the Treasury Department.
“You may have heard of other RBF products but we’re not like the other guys in the market. We’re local,” CIC says while referencing revenue based financing products from Square Loans and PayPal Working Capital as examples of who they are competitors with in a video slide.
CIC charges a 1.28 factor rate and caps the repayment rate so that if a business’s revenue accelerates substantially, the repayment rate eventually reaches a ceiling. Payments can be weekly or monthly. Good credit is not required, nor is any collateral. They underwrite the historical revenues of the business to determine eligibility. Marketing materials describe the transaction as a sale of future revenues, not a loan. However, it projects a time period of 3-5 years.
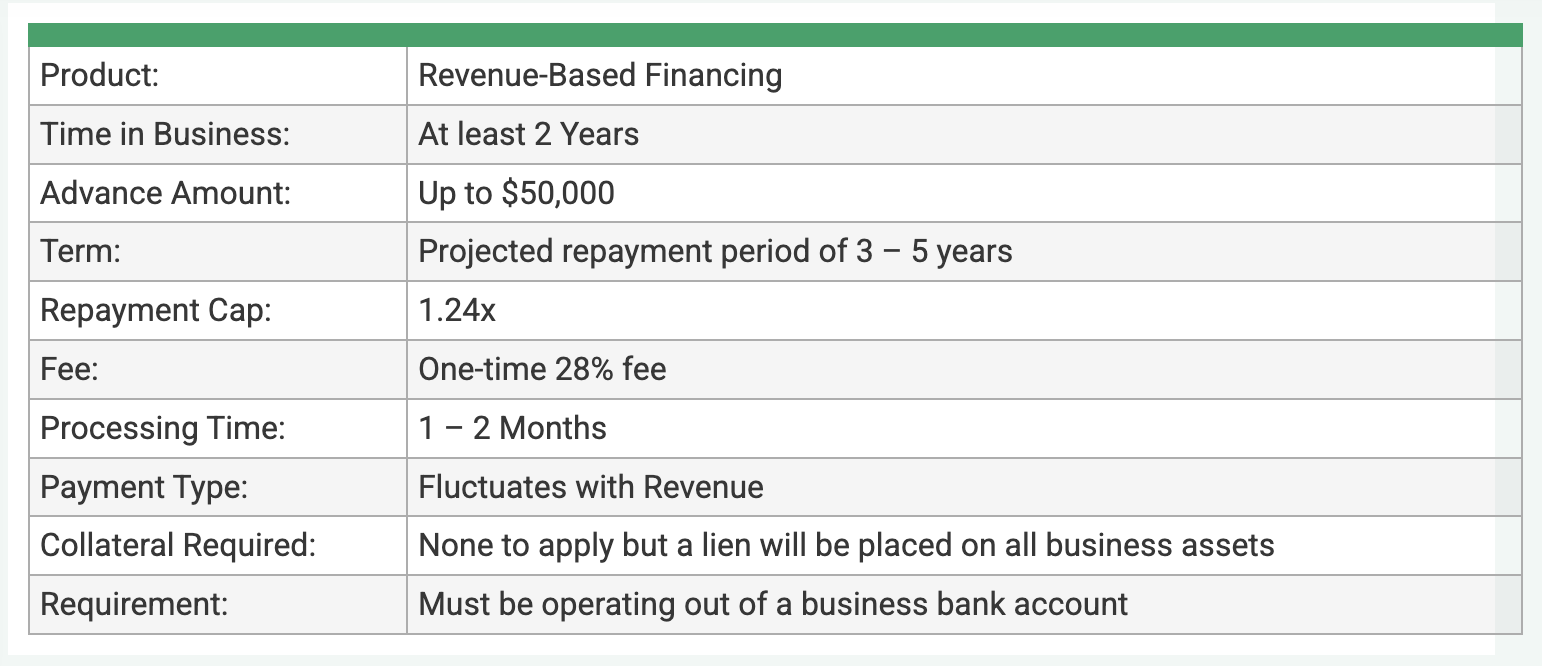
“(RBF) eligibility is determined by looking at the business revenues,” the website says. “The business owner pays back the funding they received (the amount of purchased revenue) plus a fixed fee (discounted amount) over time based on the cash flow of the business.”
CIC’s revenue based financing program launched in January 2023. It joins other states and municipalities in offering similar programs including Oregon, Washington, California, and New York City.
Figure: SMB HELOC Origination Run Rate at $500M
November 16, 2026“Growth vectors we have been highlighting in the past are strengthening,” said Michael Tannenbaum, CEO of Figure, during the Q3 earnings call. “We now have over 20 active depository partners and over 150 partners in our fast-growing SMB business, which crossed $500 million in run rate volume in Q3. And there’s more growth to come.”
Figure’s SMB business is its HELOC product. It has become a popular option in the tool belt for small business loan brokers. For example, at the B2B Finance Expo that took place last month in October, a panel of business loan brokers all said they were familiar with or were referring HELOC business to Figure.
Referral partners are continuing to play a very important role in their growth.
“This quarter saw another record number of partner additions, ending at 612 stand-alone and 894, including Kiavi’s broker partners,” said Tannenbaum. “In addition to all of the net new growth I just described, we’re also seeing expansion from existing origination partners. Those that were with us a year ago in Q3 ’25 are now doing over 40% more volume this Q3 ’26, a testament to the value we drive for partners.”
Upstart CEO on How to Beat Personal AI Agents: Build the Best Product
November 13, 2026“I think there’s just so many companies right now that are looking at what people are doing with AI, with personal agents, and trying to build these walled gardens and say, ‘Oh, man, if people could just freely shop for the best product, they might stop being loyal to us,'” said Paul Gu, CEO of Upstart, during the Q3 earnings call. “I think that just says something terrible about companies that think that way. They’re not confident in the real value-add that their product gives to their customers. I think one thing that will always be really, really centrally important to us is we just want to build the best product. We think we have the best product in a lot of cases. We want to make it even better. We want to build the best product in a lot of our emerging categories. We want to just have no fear around how the customer ultimately finds our product, whether it’s on our surface or whether it’s via a Muse or a Grok or whatever they’re using out there. We want our product to be everywhere, and we want to compete and win on having the objectively best product. We think that the era of personal agents and personal AI is going to usher in a world where people just have much more ability to shop for the very best product, and we think that’s going to help whoever has the best product to offer the customer, and we think we’re going to win in that world.”
Like other online finance providers (i.e. NerdWallet, LendingTree), Upstart has been facing questions from analysts as to whether or not they are prepared to compete with personal AI agents for customers. That’s because AI agents can often provide answers that such sites have long depended on to draw in customers, all while making their own product or destination recommendation.
“Someone just today, I think, looking at us would say, ‘You’ve been around for 14 years, and you haven’t really made any meaningful profits yet. What’s the point of all this fancy AI if it doesn’t make money?'” said Gu. Today, I don’t think we get to complain about how investors are valuing us yet. Even though I think investors are, to be clear, I think investors are wrong about the stock. I think they’re undervaluing the stock, but I kind of think they have every right to do that because they can’t tell if and when we’re finally going to make some real money, and ultimately, it’s our job to change that.”
Organic Search Headwinds Persist for SMB Lending Products at NerdWallet
November 13, 2026NerdWallet’s SMB finance referral business grew only 6% year-over-year last quarter. The company said that “an increase in business loan originations was partially offset by continued pressures in organic search traffic.”
NerdWallet execs have previously stated that borrowers shifting to AI to get their answers to monetary questions is impacting the industry. And that’s been a challenge for them since they’ve historically depended on organic search traffic to source customers.
“In terms of SEO, organic search has become a fraction of what it was for us after 3.5 years of rapid declines,” said NerdWallet CEO Tim Chen during the Q3 earnings call, “the pace of declines has stabilized a bit, in recent months. So just as a reminder, educational content has been severely impacted as Google puts AI summaries in search results.”
One analyst asked how NerdWallet could continue to compete with some of the big LLMs that are now veering into personal finance functionality and product recommendations all on their own.
“I think for us, a big piece of this is the marketplace dynamic,” Chen responded. “Consumers have to often make complex decisions, especially in areas like insurance, personal loans, mortgages, where there is risk-based pricing. And in order to do that in a compliant manner, you really need a trusted marketplace that has inventory and the pricing that is going to send you to the right place. And so that is where we are in conversations with both the model companies as well as constantly with consumers. And I think there is an opportunity to do that in an agentic world. Now exactly what shape that takes I think it is still being sorted out in terms of how the economics work. I think it is going to be much more liquid in some verticals and not going to change that much in others. But we want to be ready for all eventualities there, so we are definitely making the investment today.”
California Celebrates Its Own Business Loan Marketplace and Partnership With State-Backed Revenue Based Financing Providers
November 10, 2026The California Infrastructure and Economic Development Bank (IBank), a state government agency and capital access bank housed within the Governor’s Office of Business and Economic Development (GO-Biz), announced that it had surpassed $5 million in small business loans through its California loan match website.
“The platform is unique in that every lender is enrolled to use California IBank’s Small Business Loan Guarantees, a state-government program that reduces lending risk for financial institutions that want to serve small businesses,” the State agency says.
That includes revenue-based financing providers. Back in January, deBanked discovered one, but that number has grown. Among the 30 lender partners listed, at least three offer revenue based financing in their product suite: AltCap California, Capital Impact Partners, and Mission Driven Finance.
AltCap California
Every agreement is unique.
- Loans up to $500,000—typically sized at up to one-third of the previous year’s revenue.
- Monthly loan payments tied to monthly revenue—up to 8% of sales.
- Total repaid: 1.4 to 1.5 times the original loan amount.
- Borrower has up to 7 years to repay the loan.
- Either no personal guarantee OR no collateral required.
Capital Impact Partners
Revenue Share Mezzanine Debt
Unsecured mezzanine debt whereby businesses pay a percentage of revenues and interest.
Criteria
- Minimum revenue: $4 million+
- Positive cash balance
Terms
- Investment amount: $1–$15 million
- No collateral or personal guarantees
- Variable revenue share payment + fixed interest payment
- Use of proceeds: growth or acquisition capital
- 3–5 year term with set maturity date
Mission Driven Finance
Revenue-based and Islamic financing available.
“The Small Business Loan Match tool narrows the confusing array of lending options for small business owners,” said Andy Nakahata, IBank Executive Director in the announcement. “By tailoring matches to lenders that can choose to use IBank’s Small Business Loan Guarantee Program, we’re reducing barriers small businesses often encounter when searching for loans. We’re thrilled to celebrate California small businesses accessing $5 million to move their businesses into the future.”
Lightspeed Capital: ‘Our goal is shorter MCAs’
November 6, 2026“Today, our typical remittance period for a merchant cash advance is approximately seven months,” said Asha Bakshani, CFO of Lightspeed during the company’s Q3 earnings call. “Our goal is to target a shorter remittance time frame, and we are making great progress towards that end.”
That objective can be most likely attributed to the company’s desire to redeploy that capital as fast as possible since the company is always closely monitoring and managing its cash flow.
“Aside from potential buybacks, our largest use of cash will be growing our merchant cash advance business,” Bakshani added. “There are currently $106 million in merchant cash advances outstanding, and we intend to continue to grow this high-margin business over time.”
Like other e-commerce platforms that do the same (Shopify and Block), Lightspeed has continued to be impressed by the overall positive impact of providing working capital to its own client base. In their regular quarterly financial docs for example, they explain that the purpose of their MCAs are “to help [merchants] with overall business growth and cash management. Merchants are meant to use these cash advances to manage their cash flows, to buy inventory, and to invest in marketing, amongst other things.”
Square Loans Has Consistently Beat its 4% Loss Target
November 5, 2026Square Loans isn’t just the largest originator of online small business loans that deBanked tracks, they’ve also managed to beat their 4% loss target every year for the last 10+ years.
“Since launching Square Loans in 2014, we’ve been able to hold loss rates consistent with our target while meaningfully expanding eligibility to more and more customers,” the company said in its Q3 shareholder letter. “Every annual Square loan cohort has performed in line with or better than our 4% loss target, and we’ve been able to grow Square Loans at a 27% CAGR over the past decade because of our disciplined underwriting approach, proprietary data, and world-class expertise.”
During the earnings call, Block’s Head of Underwriting, Juan Hernandez, said that their success with Square Loans is a “core part of their DNA.”
Square Loans benefits from the POS ecosystem that Square provides its clients.