Canadian Merchants Show An Appetite For Capital
November 25, 2017In Canada, the average deal size for a merchant is anywhere between $20,000 and $30,000 in funding, depending on who you ask. That’s why when one startup recently funded a $300,000 CAD advance from its balance sheet to a Canadian merchant, the deal turned some heads. While it’s unclear whether this amount could be indicative of a trend unfolding at our neighbors to the North, Canadian small businesses are preparing for some changes in the industry landscape in 2018.
SharpShooter Funding, whose name depicts the famous wrestling move of the WWE’s Bret “The Hitman” Hart, was behind the $300,000 deal with an Eastern Canadian grocer.
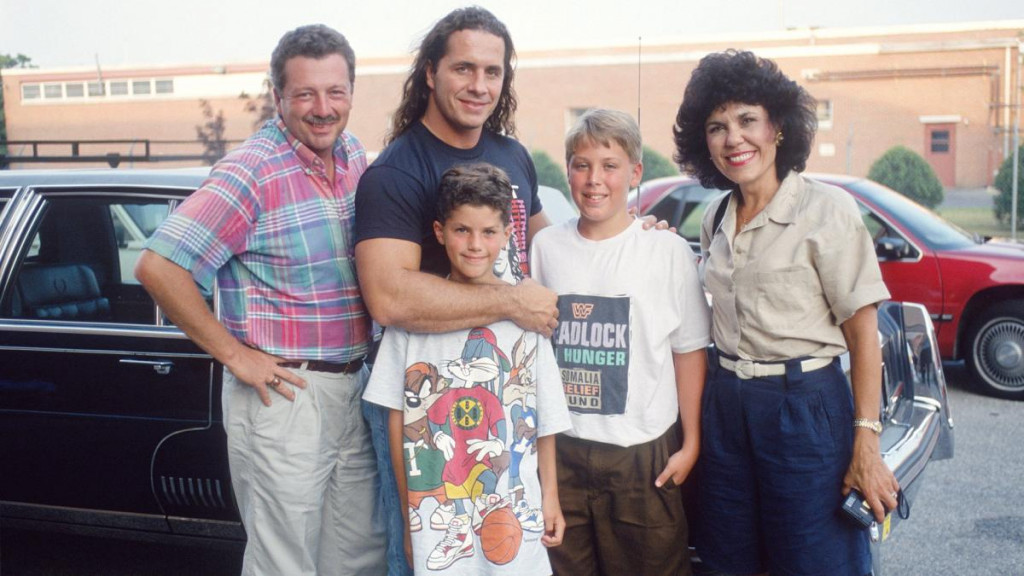
If you’re wondering how a merchant funder and WWE legend became partners, chalk it up to a combination of fate and timing. Paul Pitcher, SharpShooter Funding managing partner, has been Hart’s biggest fan since he was a kid. Pitcher got the opportunity to meet his hero when was just 10 years old. It was then that the green shoots of friendship formed, and today the WWE’s Hart is acting commissioner of SharpShooter Funding, having helped to launch the business.
Canadian Merchant Landscape
To get a taste of the Canadian merchant financing landscape, consider that the three top Canadian funders deploy $20 million and $25 million per month combined, explained David Gens, president and chief executive of Merchant Advance Capital, which is included among the top three funders. That’s up from a range of $15 million to $20 million earlier this year.
And while a $300,000 advance may not seem like something to write home about for U.S. funders, it’s a big deal in the Canadian market. The culture among small businesses in the Great White North is different and more conservative than their US counterparts.
“It’s a function of the size of the merchant,” Gens explained. “The typical single-location storefront merchant is going to qualify for $30,000 to $50,000. It takes a larger and more established business, whether it’s a multi-location merchant or a business that is in the B-to-B space, a manufacturer, distributor or wholesaler to be large enough to qualify for large financing.”
Meanwhile there are some changes to small business taxation that are coming down the pike that may influence demand for credit, Gens noted, though the precise shape any changes to the tax law will take remains unclear.
“They will reduce the small business taxation rate on the face of it. But for businesses where they hold cash or need to hold cash, it’s a gray zone as to whether or not they will be able to hold financial assets in those businesses. The government is going after companies that are holding investments. But there’s a gray line as to what is a holding company that is holding an investment and an operating company holding a buffer because of seasonality or cyclical demand. We have yet to see what the rules end up being exactly,” Gens said.
Anatomy of the Deal
In the case of SharpShooter Funding, the grocer merchant originally came to the funder for less than $300,000 but qualified for more, bringing the funder’s tally for a single day’s deals to more than $500,000.
“We never thought we’d hit this milestone in the Canadian market. But the file was right, and the timing was great,” Pitcher told deBanked. Now that they’ve gotten a taste of it, SharpShooter Funding hopes to do more deals of this nature. “For a small funder like us to double the size of a big funder was a big moment for us, especially in the Canadian market,” Pitcher said.
Merchant Advance Capital’s Gens said his company is prepared to take on the risk for deals at even a higher threshold. “Our average is $35,000 to $40,000, and the largest deal we’ve ever done was $600,000. I don’t want to steal their thunder, but there have been larger deals,” said Gens. “A few funders may syndicate when deals get that big, but it’s not an inconceivable size.”
OnDeck, which similarly has Canadian operations, lends up to $250,000 CAD in Canada. OnDeck has extended more than $7 billion in online loans across 70,000-plus customers across the United States, Canada and Australia.
As for SharpShooter Funding, Pitcher said the funder has been on the sidelines for larger deals because they don’t want to grow too fast. He’s been turned off by other funders doing deals within a couple of months of launching and then being forced to close their doors.
“Our capital has always been strong. It’s not that we can’t afford to lend larger amounts. It’s because we want to make sure we’re doing it right from the start,” Pitcher said, adding that SharpShooter Funding has only had its doors open in Canada since June 2015, though its corresponding U.S. business, First Down Funding, has been around since 2012. “It’s been a work in progress, and I love every day of it! We’re only getting started, and I am 100% excited for the future,” he said.
The Canadian grocer reached out to SharpShooter Funding in response to Google advertising. The affiliation with the Bret Hart association didn’t hurt. Pitcher explained there is a seasonality tied to the merchant’s business, evidenced by a couple of months or more each year in which revenue is spotty, that made the grocer unattractive for banks to fund. “That’s why those sized deals are difficult to put out and banks won’t put out, because of seasonality,” Pitcher said.
SharpShooter Funding was not deterred by that. “We were really able to gain in-depth trust and visibility into this merchant from the first call to the last call. There was never a problem with him mixing up stories. Just the honest truth. From his references to his landlord, everyone involved made it clear he was here to work with us and not to play games,” Pitcher said.
Pitcher was impressed by the business owner’s work ethic. “He’s a roll-up-your-sleeves entrepreneur who didn’t borrow $1 million from his father. No bank loans. Six years ago, he rolled up his sleeves and made it work. Now he’s in a situation where banks won’t lend to him. But we will,” he said.
The merchant’s bank statements also made sense to the funder given their consistency, predictability and transparency. “Whenever we ask for finances from someone and that merchant can get them to us in an organized fashion in less than an hour, it speaks wonders. It means they’re honest and ready to play ball. And that’s what we want,” Pitcher exclaimed.
The merchant plans to use the capital for an expansion into a new food product line. If he pays off the advance early the funder will lower the rate.
Take a Break From Funding This Thanksgiving
November 21, 2017This Thanksgiving…
Step back from the daily grind
Those merchants eager for your cold calls can wait
There’s no need to start worrying about next year just yet
It’s Thanksgiving
So hug an underwriter
Kiss a broker
Think about your favorite merchant
And pay no attention to the algorithms automating your job
Give thanks
Because nobody wants to hear you recap your holiday like this
Or this
Or this
Enjoy the Holiday!
You should also check out our 2016 Thanksgiving Day post and 2012 Thanksgiving Day post.
The Bad Broker And Merchant Due Diligence
November 15, 2017 There may be a rogue broker on the loose. The scam involves a fraudulent Letter of Intent (LOI) falsely claiming to be that of a major funder designed to resemble the real McCoy. Events like this place a spotlight on the risks associated with this market and is a reminder that not all small businesses are armed with the right information.
deBanked was contacted by a victim of the fraud, Noah Grayson, managing director and founder of Encino, Calif.-based South End Capital. Grayson said the real victims are the merchants who get taken advantage of by these scams. In this case it was a New York-based small business owner who took on too many MCAs.
Grayson is quick to point out the MCAs were not at fault and each may have even thought they were the first position funder since it all unfolded so quickly. “They’re just trying to do business and provide financing to businesses, and they got burned as well. They’re going to take some degree of financial loss because of this and maybe more,” Grayson said.
False Pretenses
When Grayson reviewed an email that he received from the borrower, which included a copy of the LOI, he knew immediately that it was fraudulent and the borrower had been misled. “It was a fraudulent LOI and we had no record of the borrower or the brokers who provided it in our system,” Grayson exclaimed.
As it turns out, the borrower was tricked by the fake LOI that sought to leverage the reputation of South End Capital’s brand to coerce him into taking out $260,000 of MCAs from four separate funders. They did it under the false pretense that South End Capital would then consolidate those positions in 10 days and extend as much as $900,000 more in working capital to grow the business.
To be clear, South End Capital does offer a genuine MCA consolidation loan program. Grayson had never agreed to consolidate the business owner’s MCA positions, however, or provide an additional $900,000. That part was fabricated. This left the merchant holding the bag for more than a quarter of a million dollars in MCAs, placing his business, which has been successful since the 1960s, on the brink of bankruptcy protection in the interim because of the crippling weekly payments.
Fraud Prevention
Andi McNeal, research director at the Association of Certified Fraud Examiners, or ACFE, said she has seen this before, only on the consumer side of the industry. “Loan consolidation fraud for credit card debt is very common in the consumer space, and it’s not surprising to know that similar schemes are popping up in the small business space, too,” she said.
She went onto explain that because a small business is typically run by a small management team who typically aren’t trained in fraud prevention, they often adopt the same mindset as they do in personal finances. They don’t always have the necessary checks and balances in place, which can place them at risk of being victimized by such schemes.
“Sometimes they’re not savvy enough to detect those types of scams coming at them,” she noted. “Certainly, big businesses can fall prey to this, but it’s less common.”
Staying on Defense
The recent saga unfolded over a period of six weeks. Meanwhile Grayson has outlined some red flags for small businesses to watch out for to prevent becoming the next victim to a new fraud.
“If what you’re being told seems suspicious or doesn’t make sense, question it. Ask questions and get more information,” said Grayson.
Another rule of thumb is to stick to the document in front of them. Again, this may just be a case of a few bad apples spoiling the bunch, but sometimes brokers tell small businesses something contrary to what appears in front of them on the official document. “The LOI spells it out,” said Grayson, adding that when in doubt the borrower should defer to the document.
The merchant should also take it upon themselves to call the lender whose name is on the LOI to verify its authenticity before signing it or providing any upfront fees.
“In this case, it was a fraudulent document and it didn’t help out the borrower but calling us to confirm it initially would have. Most of the time, looking at what’s written out on paper from the verified source will help and getting a verbal or email confirmation from the actual lender, certainly will,” Grayson said.
Another defensive step merchants can take is to simply review the website of the brokers and funders and look for names, press releases and past closings, details which Grayson noted were all missing from the broker in question’s site.
“Anybody can say they make loans and provide financing. They could tomorrow put up a website for a couple bucks and say they’re a lender and start taking applications. But just because there’s a website doesn’t mean they’re legitimate,” Grayson said.
He’s suggesting merchants check out the names of the principals and employees on the site. Google is their friend to check for any history of loans closing. Look for closing announcements and any complaints tied to the entity in question. Call the Secretary of State Department and inquire about any complaints.
At the end of the day, it comes down to the merchant doing their homework. “A lot is on him. He should have done more research, absolutely. But anybody can be coerced or tricked if the right things are said,” said Grayson.
If a merchant does find themselves in a situation where they fall victim to a fraud, there are steps they should take. McNeal said that while each situation is unique, a good first step is always going to be to reach out to a trusted legal counsel.
“They can help guide you through the process of what the options are. Do you have recourse? Does the situation call for insurance to help cover the losses? They also can advise on which law enforcement or government agencies are the most helpful – should the case be referred to the local authorities or do they need to bring in the FBI,” the ACFE’s McNeal advised.
More Pervasive
Grayson’s fear is that this is not an isolated incident. He has reason to be cynical, as this was the second incident this year resembling the most recent situation that they have experienced.
The first incident was relayed to South End Capital by a handful of borrowers about one specific MCA broker. No fraudulent documents were ever recovered, but the borrowers recalled the harrowing details of the incident
“Per the multiple borrowers, the broker used our real LOIs and lied to borrowers about how to interpret them to coerce tens of thousands of dollars in upfront fees from them. For example, for an LOI we issued for our SBA loan program that listed what SBA guarantee fees would be due at closing, he would convince them that that fee was his and they needed to pay it to him upfront to proceed,” Grayson explained.
The small business owner at the center of the scandal declined to comment, and it’s unclear whether they were the one to initiate the original communication with the broker or vice versa.
Former MCA Co-founder Meir Hurwitz Kicks Off New Venture With Kim Kardashian West
November 9, 2017I love how @screenshopit lets you find the exact designer looks you see people wearing online, plus suggests similar items at all price points! #ScreenShop_Ambassador https://t.co/TXZ23agVoT pic.twitter.com/nA8JBDVbU5
— Kim Kardashian West (@KimKardashian) November 7, 2017
An early innovator of the merchant cash advance industry has re-emerged on the business scene in a very different new venture focused on mobile shopping.
Meir Hurwitz, co-founder of Pearl Capital, the MCA company acquired in 2015 by Capital Z Partners Management LLC for as much as an estimated $60 million, is now the chief visionary officer of ScreenShop. The New York startup markets an app designed to enable users to shop for a specific item by uploading a screenshot of the item to the app.
Working on a mobile app is a longer shot than MCA and it doesn’t always pay off, but Hurwitz said Thursday he’s enjoyed learning the business after two years off and visiting 62 countries since selling Pearl Capital.
“It’s new and exciting for me, but I don’t get paid right away,” he said. “It’s something I haven’t done before — it’s kind of exciting for me.”
The app is the first developed by New York-based Craze Ltd. and publicly launched on Nov. 7 with celebrity Kim Kardashian West cited as an advisor. Craze employs 12 technical workers in Israel and five in New York, Hurwitz said.
Hurwitz started in MCA in 2006 and then launched Pearl Capital with partner Abe Zeines in 2010.
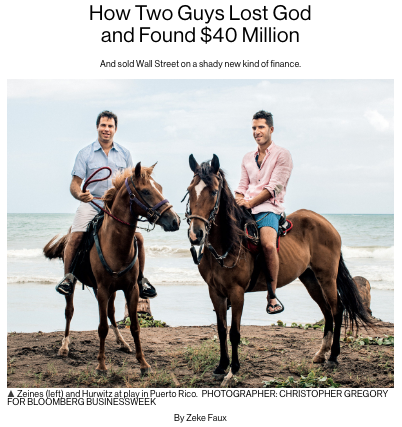
Pearl launched with $1 million and generated an $8 million profit in 2012. The following year, the company doubled its profit and reached origination volume of $100 million, Bloomberg reported in 2015. Hurwitz’s ScreenShop profile indicates that he’s a “three-time successful entrepreneur” and cites “over $500 million in funding capital.”
In addition to a real estate business in Puerto Rico, Hurwitz said he’s managing partner of New York-based GS Capital, a convertible debt company lending to small businesses. Zeines lists himself as the CIO of GS Capital, according to his online profile.
At ScreenShop, Molly Hurwitz (Meir’s sister) is listed as the co-creator and co-founder. CEO Mark Fishman was previously a risk manager for Pearl Capital.
The startup’s app, which is free, scans screenshots taken from any app or website on a mobile phone, converting them to similar items that can be bought for various prices. It plans to generate revenue by collecting a commission at the point of sale, Forbes reported.
“The results have been — we’re No. 5 on the app store category of fashion,” Meir Hurwitz said. “We’re just getting started.”
ISO Alleged to Have Forged a Confession of Judgment
November 6, 2017 Underwriters, keep your eyes on the notary stamps.
A lawsuit filed in the New York Supreme Court last week by a merchant cash advance company against an ISO and several co-defendants, alleges that an ISO was partially responsible for damages when a merchant defaulted.
And they make a compelling argument. In this case where a Confession of Judgment (COJ) was required to approve the deal, the merchant, who defaulted within 30 days of being funded, claims to have never signed one, despite the ISO having delivered a signed one to the funder.
Well then who signed it?
Upon inspection, the notary stamp on the COJ belonged to a notary in Nassau County, NY, where the contract logically would’ve been notarized. But the merchant is based in Florida and claims to have been in Florida at the time the COJ was allegedly signed.
So who would’ve been in Nassau County that day?
According to the funder, it was the ISO, since the ISO is based on Long Island and the ISO is the one that delivered the signed COJ to them.
These are just the allegations at this point, of course, since the defendants have not even yet had a chance to respond.
The complaint, however, adds another twist, that after the ISO got the deal funded, they then referred it to a debt settlement company, who assisted the merchant in defaulting.
As you might imagine, the debt settlement company is a named co-defendant.
The case is filed under Index Number: 656692/2017 in the New York Supreme Court. You can view the entire complaint here.
CFC on the Front Lines of the MCA Regulation Battle
November 6, 2017
As the US Senate attempts to reach a bipartisan agreement on relaxing some of the rules in the Dodd Frank legislation of 2010 that would treat banks more favorably, the MCA industry is having to fend off legislation and regulation of its own at the state and federal levels that could position funders in a similarly crippling position.
MCA regulation has been thrust into the spotlight for a number of reasons, not the least of which has been the Consumer Financial Production Bureau (CFPB). The CFPB is moving forward with the Dodd-Frank Section 1071 rulemaking process for data collection regarding small business lending, a sector of the market for which they do not have jurisdiction, sources say.
Front and center in the policy discussions has been the Commercial Finance Coalition (CFC), a merchant cash advance trade association that is coming up on its two-year anniversary in December. While federal policymakers appear to be listening, state legislatures have been a more difficult nut to crack.
The CFC’s Influence
In its short two-year history, the CFC has been one of the most vocal if not the most influential trade organization lobbying on behalf of the MCA industry, having attended 70 congressional meetings and having led advocacy efforts for the industry in the halls of Albany, Sacramento, Illinois and Washington, D.C.
Dan Gans, executive director of the CFC, has been the voice of the MCA industry on Capitol Hill and has been invited to testify in key congressional hearings. “For whatever reason, the CFC has really become the voice and has taken an active part in the so far successful advocacy efforts to educate and mitigate potential harm to our members’ ability to deploy capital to small businesses that need access,” Gans told deBanked.
Most recently the CFC participated in a fly-in, one of two such events this year, to Washington, D.C. in which the association’s counsel Katherine Fisher of Hudson Cook, LLP testified.
In her testimony Fisher said: “The MCA and commercial lending spaces are sufficiently regulated by existing federal and state laws and regulations. Both MCA companies and commercial lenders must comply with laws and regulations affecting nearly every aspect of their transactions, from marketing and underwriting through servicing and collection.”
She went on to explain: “Even if they comply with every applicable law and regulation, small business financers must also be wary of the Federal Trade Commission’s powerful authority to prevent unfair or deceptive acts or practices.”
Fisher told deBanked she received a “positive” response to her testimony from funders but has not heard anything from lawmakers.
Gans said Fisher did a fantastic job in articulating the needs and status of the industry.
“She presented a very good case as to why the industry is currently adequately regulated. We don’t feel there is a need for federal regulation. In some cases, less regulation would allow our members to deploy more capital and help more small businesses,” Gans said.
The sweet spot for MCAs, Gans explained, are transactions under $100,000 and probably in the $24,000 – $40,000 range. He said the industry does a fantastic job of being able to deploy financial resources to small businesses in a timely manner that neither banks nor SBA lenders can match. He’s not suggesting MCA is for everybody but for some businesses it’s an essential product that can help. There have been many success stories.
“Competition is all over the place. But that’s great for the merchant. The more options that merchants have, the more we can enforce best practices and more competitive rates. And the more we can keep the government from impeding people from getting into this space, the better off small businesses are going to be,” said Gans.
Setting the Record Straight
The CFC was formed with the mindset that the organization, which is currently comprised of CEOs of small- and medium-sized funders, would take a proactive rather than a reactive approach to industry regulation. In its two-year history the CFC has tasked itself not only with educating policymakers on the role of MCA funders for small businesses but also with undoing the misinformation and misconception surrounding the anatomy of an MCA.
“Unfortunately, because MCA uses the term cash advance in its product name, uninformed people will often confuse MCA as some form of payday lending. And so that has been one of our biggest challenges, educating members of congress and committees that there is absolutely no correlation between MCA products and what their views of consumer payday loans is,” said Gans, adding that the CFC has had to communicate that MCA is a version of factoring has been around for more than 1,000 years.
A common thread that the CFC has been able to weave with lawmakers has been the diverse geographical representation of both the trade group and the House and Senate.
“Most venture capital is deployed in a few spots – New York, California and Texas – and it’s a cliff to get to those three states. So, one nice thing that I take pride in is my members are looking all around the country regardless of the geographic location. That helps us with policymakers, most of whom are not from the New York City metropolitan area or Silicon Valley. It’s nice being able to look at them in the eye and tell them we care just as much about your district as you do,” he said.
The Road Ahead
The CFC has an ambitious long-term agenda, one that includes raising their profile in the industry and participating in events.
“I think one of the ambitions we have is to have an organization where funders and brokers can be at the same table and work though some of the issues impacting the industry and try to make sure people are doing things in the right and best way.”
The trade group is planning to partner up with deBanked for Broker Fair 2018 and they’re looking to bolster membership.
“The industry has had a lot of free riders that are benefiting from our advocacy efforts but not supporting it. So, from my perspective, if you’re in this industry, particularly in the MCA space, we’d like to expand membership. If we grow our membership, we can do more things, engage more states and expand our lobbying team,” said Gans. “The more members we have, the more we can do to advance the ball and protect the interests of the industry.”
The CFC will need all the help it can muster given the fight ahead to fend off regulation particularly in Washington, Albany and Sacramento. “I think we could see some harmful regulations and potentially legislation over time. Some of those bad ideas that emanate in states have a tendency to percolate into Washington. If at some point there is a less business-friendly administration in the future, we could see all those ideas get some traction at the federal level,” Gans warned.
View From The C-Suite: Alternative Funding Execs Talk Shop, The Landscape, And The Future
October 30, 2017 Alternative funders have had a roller coaster 2017 with highs and lows that will likely be remembered as a high-stakes time for the industry, one in which the rubber met the road for many and the market landscape shifted for everyone from funders, to merchants to brokers.
Three C-Suite executives in the alternative funding space — Christine Chang, CEO of 6th Avenue Capital, Heather Francis, CEO of Elevate Funding and Torrie Inouye, National Funding president — spoke with deBanked, offering their take on some of the industry shakeups, direction of the alt lending space and upcoming developments at their respective companies.
All three execs are embracing what appears to be shaping up as a bigger and better 2018 with plans on the horizon for new products, relationships and deals but also where there could be further shakeout as the shift in the industry landscape takes hold.
Industry Landscape
6th Avenue Capital, provides short-term funding to merchants that Chang describes as “high touch, high tech and fast.” The company is building an SEC RIA compliant infrastructure as Chang believes that MCA regulation will take place over the next several years. Chang said she is sympathetic to the banks and the onerous rules that they must follow, and whatever form the industry regulation eventually takes on, the company will be ready for.
A recent story in The Wall Street Journal points to community banks comprised of those with less than $10 billion in assets historically funding local merchants in what’s dubbed character-based lending. As the name suggests, the underwriting standard for the loans was tied to the character of the business owner, which the lender knew based on personal relationships in their own communities.
The financial crisis gave rise to greater regulation, driving a spike in that model and the rest is history. Small banks were forced to direct their resources toward risk management and compliance instead of adding more personnel to service loans. The WSJ quotes a small business lender that bears repeating: “When they created too big to fail, they also created too small to succeed.”
When that door closed, however, another one opened, creating the opportunity for alt lenders to service a niche that was getting left out in the cold.
“The alternative funding industry is here to stay. That’s good news for MCA and fintech in general. There’s a need for fast funding and there will continue to be a trend toward that,” said Chang.
Banks, meanwhile, have started coming to the fintech table to compete for deals. “We’re in the process of speaking to a number of banks, some quite large and some regional, that have expressed an interest. We think this is a great opportunity for them. The idea is that we’d help them to serve a population of clients that they would not otherwise be able to serve,” said Chang.
6th Avenue has had discussions about white labeling and customizing the platform for institutions. “We would run everything for them,” said Chang.
In addition to possible new banking relationships, 6th Avenue Capital, backed by a private family and institutional investors, will expand the business model to include more investors on its platform. “We are in discussions with a number of significant international investors. It’s in the works. We’re building an institutional infrastructure, so it was always contemplated,” she said.
Elevate Funding, whose is 100% referral-based and whose product suite is comprised of a trio of MCA solutions, is coming up on its three-year anniversary in December.
“When I created Elevate, I did it with the purpose of providing a product to high-risk merchants. That’s who we deal with. We’re not dealing with credit scores. There is a level of risk to who we work with. Elevate was created to provide a product that is going to fit their needs and also provide a product that doesn’t treat them like they’re high risk. That’s who we are,” said Francis.
Gainesville, FL-based Elevate recently hired Michael Gaura to spearhead a new MCA product that the company is rolling out in 2018. Francis held the details of the new funding product close to the vest, but she did offer her views on the direction of the MCA and alternative lending space.
“I see difficulty in the coming years, especially in 2018, for qualified lead flow. You have a lot of big banks that are getting into this industry. And that’s a lot of marketing dollars that you’re competing against.”
She points to JPMorgan Chase, American Express, Square and PayPal, saying they are “huge marketing dollar companies” with tremendous access to customers on their respective platforms.
“There’s going to be a shakeout of what can you reach, who can you reach, can you get them the first time? How do you engage them to where they only want to work with you and they’re not submitting 20 applications for every website they come across?”, Francis said.
San Diego, Calif.-based National Funding is a balance sheet lender whose primary product is loans, not MCAs. The broker factor has changed significantly for the lender in a very positive way this year. “We’re really seeing sizeable growth in our broker channel in 2017 and have designed a strong and consistent process for our broker clients” Inouye said. The leads have been driven by a variety of factors, not the least of which comes down to CAN Capital and Bizfi’s loss being National Funding’s gain.
“That’s a factor we can’t ignore. The broker community has rewarded us for being consistent and building those relationships and being a partner to them,” Inouye said. “We definitely saw an uptick in business when they left the space. I can say we’ve continually experienced sizeable growth in our broker channel year over year but 2017 was beyond what we had expected. It surpassed other years.”
Incidentally, National Funding was one of the earliest alt funders on the scene along with CAN Capital in the 1990s. CAN’s fate started unraveling about this time a year ago.
“It’s not positive when you see that happen in the industry. However, we are really focused on what we’re doing and the decisions we’re making internally. I think that’s why we’ve consistently had profitable growth over the years. We’ve stayed true to our underwriting principles and the market seems to have rewarded us. We were consistent and not erratic. Brokers know they can rely on us and feel confident that we would quickly fund their deal once we issued an approval,” said Inouye.
The Broker Effect
Elevate, a balance sheet funder, relies on outside brokers and referrals for deals. “I don’t find it a disadvantage for us not having an internal sales team. A lot of companies in this space have the ability for a chief marketing officer who focuses entirely on leads. Elevate isn’t there yet. Will we be there in five years? Maybe. Marketing can change by that time,” Francis said.
6th Avenue Capital welcomes relationships with brokers as well. “We have an in-house business development team that works with brokers. 6th Avenue Capital is also considering direct sales in niche strategies in its future,” said Chang.
6th Avenue Capital has a starter program in which there are no guarantees but considers businesses that have been in existence for less than a year and businesses with credit scores of 500 or more. Plus, they’re willing to do consolidations up to two advances.
In addition, 6th Avenue Capital is open to offering financing to brokers. “It’s really good in that there is an alignment of interests and allows brokers to participate in the deals they put forth. If they think the merchant is credit worthy and a terrific opportunity, they participate. Everyone has skin in the game and interests are aligned,” Chang said.
Technology
While technology is at the core of fintech, all three of the companies take a hybrid approach when it comes to credit underwriting comprised of a tech platform and the human touch, which perhaps keeps character-based lending alive in some form.
With respect to fintech, “6th Avenue Capital’s philosophy is that technology is a tool to supplement human underwriting. We use technology to detect fraud, manage workload processes and manage risk. We do not use technology to make our final decisions,” said Chang.
Specifically, 6th Avenue Capital benefits from research, artificial intelligence and predictive technology of its sister company Nexlend Capital. 6th Avenue Capital has customized Nexlend’s consumer lending algorithmic intellectual property, which uses machine learning and credit analysis with high speed execution to make better and faster decisions.
Elevate also takes a dual-approach to its underwriting process. “I believe in a hybrid method. You have to have someone looking at it, to have eyes on the paper at some point in the process. This doesn’t mean a computer system can’t help to weed out what might not meet the criteria, but I do believe there needs to be a person reviewing the files,” Francis said.
National Funding was started as an equipment leasing company. “We apply some principles we learned as a leasing company and take into account all of the attributes that go into that business in addition to FICO and cash flow,” Inouye said.
Automation is an area of technology that they continue to look to for innovation and process efficiencies. “We do serve our customers online, but we also provide a human contact as well. We deliver a loan experience that builds trust and confidence with customers. We try to deliver on what our customers want in the most efficient way,” said National Funding’s Inouye.
National Funding continues to look at construction deals and accepts them as a niche in their portfolio, which Inouye said differentiates the company. “It allows us to be more flexible and comfortable with certain industries that other lenders might stay away from.”
Corporate Culture
2017 has been a roller coaster year for fintech including alt funders. While there have been plenty of bright spots, there was also some fallout that left veteran players scrambling to salvage either their reputation, status as a funder or both.
SoFi has been at the center of controversies that resulted in the Mike Cagney leaving his chairman post with plans to step down as CEO. Most recently, the lender has removed its application for a bank charter, according to reports.
We asked Elevate’s Francis about it. “SoFi is a very big company. They’re to the level where the CEO has people to answer to. They have a checks and balances system they need to go through,” said Francis. “It worked, and they removed him.”
Francis maintains an open-door policy with her employees, and she says all you can do is focus on your house and keep your house in order. “My door is always open. That’s our office policy. They use that quite frequently; it’s a catch 22,” she said with a laugh.
Fintech and Diversity
Something else that all three executives have in common is that they are all women in top roles in fintech, an industry that isn’t known for its diversity.
6th Avenue’s Chang’s career includes working at a large institutional bank for six years. Out of 200 professionals, only four of them in her group were women. “At the end of the day, performance is the best differentiator. If you perform well, it presents unique opportunities. At 6th Avenue Capital, diversity is embraced. Our underlying merchants aren’t just one gender or color. Diversity helps us understand the needs of small businesses better, so we can provide fast and customized funding quickly,” she said.
Goodbye Liens and Judgments
October 28, 2017 Justice can require sacrifice. Take the example of a decision by the three major credit bureaus – Equifax, Experian and TransUnion – to stop including some liens and most judgments in their credit reports.
The change makes life a little less unfair for consumers who fell victim to reporting errors. Many invested precious time and large amounts of money trying unsuccessfully to correct their credit histories and restore their reputations.
But for the alternative small-business finance industry, omitting data on liens and judgments increases costs, creates extra work and can even give rise to an unsettled feeling in the pit of the stomach. “You’re not looking at a full credit report anymore, which is kind of scary,” one alt funder admits.
Yellowstone Capital CEO Isaac Stern provides an example to illustrate what’s at issue. “Imagine I’m the Ford Motor Co. and I want to do a lease with you,” he says. “But I don’t have the information that you happen to have judgments from Chrysler, Chevy and BMW, so I approve your lease. Imagine that! Without full information, how do you make accurate decisions?”
Operating without the data could prove dangerous, agrees David Goldin, who sold his U.S. Capify operations to Strategic Funding Source in January but still runs Capify UK and Capify Australia and remains open to U.S. opportunities. “The IRS could come in and seize credit card processing accounts and prevent the lender from getting paid,” he says. “Once you have a judgment a creditor could come in and freeze bank accounts.”
Fears aside, the change in reporting probably won’t dry up alternative small-business credit – even in the short run, Goldin predicts. Alt funders will adjust quickly, he says, noting that they can compare the old and new credit scores of long-time customers to spot patterns and apply those patterns to their calculations. The industry can also tap alternative sources of information.
Even with those reassurances, the transition would have been easier if the industry had more advance notice, alt funders say. “We found out July 31 when a Reuters rep emailed us and said this is going into effect tomorrow,” recalls Stern. “That was really weird – I’ve got to tell you.” Experian didn’t provide a heads-up even though Yellowstone is one of its largest New Jersey customers, he notes. “We were a little bit annoyed, but what are going to do?” Meanwhile, Goldin says he didn’t begin researching the situation until deBanked asked him about it. “I don’t think anyone really knew about it” much in advance, he says.
But the industry is finding out and taking action. Yellowstone, for example, is performing a performing a workaround by integrating the judgments and liens section of the Clear investigative platform into the information underwriters see when they open a file, Stern says. The integration required a couple of weeks of hard work by the Yellowstone tech team, he notes.
 Clear, which is provided by Thomson Reuters, amasses public records that can date back 20 years and can fill more than a hundred pages, he says, adding that you have to know where to look for the relevant information. “You have to dig through it,” he says.
In the past, Yellowstone performed a Clear report on most files just before funding them, Stern explains. Now, the Clear report is scrutinized more extensively and earlier in the process – before the file is approved. As a result, Yellowstone underwriters will have all the information they need, but it will take them a little longer to get it, he says.
Yellowstone incurred the expense of obtaining additional user licenses from Clear, which cost it $800 to $900 monthly Stern says. Experian now charges the same price for less information, he notes.
Accommodating the changes didn’t require more underwriters but it became necessary to hire four additional data entry clerks to input information until the integration with Clear was completed, Stern says. Now that Clear and the Yellowstone systems are working together, the four extra clerical workers will shift their attention to inputting data from the increasing number of applications coming into the company, he says.
Most Alt funders won’t need to employ more people in their underwriting departments because changes to their models will be automated, Goldin says. “I don’t think this is as much of a game changer as people think it is,” he says of the credit bureaus’ new approach to reporting.” It’s just one extra step. It’s more of a nuisance issue than a manpower issue.”
However, a challenge arises for underwriters because leaving out the liens and judgments will result in higher credit scores for some loan or advance applicants, Goldin says. That means some alt lenders may need to go to the trouble and expense of tweaking their risk models to compensate for the change in the scores reported by the credit bureaus, he maintains.
The impact may be greatest among alt funders who rely on quick online decision-making, Goldin says. Adding extra steps to the process increases the difficulty of maintaining the speed that provides a selling point and a source of pride for those companies.
 While Clear is helping to fill the gap at Yellowstone, it’s not the only company providing much-needed data. LexisNexis Risk Solutions isn’t a credit bureau and will thus continue to disseminate information it gathers from courtrooms on lien and judgments, Goldin notes. Alt lenders who weren’t already using the vendor’s service or were using it only when an application reached a predetermined threshold will face added expense because of the credit bureaus’ decision, he says.
Indeed, LexisNexis Risk Solutions views the credit bureaus’ hiatus on some liens and judgments reporting as a business opportunity to increase its sales by supplying the missing data, according to Ankush Tewari, senior director of marketing planning in the company’s business services section. The company was already selling data on liens and judgments and anticipates selling much more of it, he observes.
 For 15 years LexisNexis Risk Solutions has been selling RiskView Solutions, a product that contains liens, judgments and other information not generally found on credit reports, such as the assessed value of a consumer’s home or a list of a consumer’s professional licenses. It offers no data on loan repayment but its other information helps define a consumer’s creditworthiness and character, Tewari says. Lenders can combine that peripheral information with credit scores for a more complete customer profile that outperforms the credit score alone, he suggests.
And there’s more. LexisNexis Risk Solutions has reacted to the credit bureaus’ decision by creating RiskView Liens & Judgments Report, which lists only those two types of records. “The credit bureaus announced these changes a year ago, and we knew there would continue to have a need for that data,” Tewari says. The company prices the RiskView information based upon the transaction volume, he notes, so a lender pays less per transaction as volume increases.
With this emphasis on liens and judgments, one might well wonder who tracks down the information. Companies like LexisNexis Risk Solutions gather and disseminate public records on liens and judgments from courthouses throughout the United States, says Tewari. Over the years the company acquired some of its competitors and eventually was spun off from its sister company, LexisNexis, which built its name partly as an aid for lawyers researching cases, he notes.
For decades, LexisNexis Risk Solutions has been providing the credit bureaus with raw data not only on liens and judgments but also on bankruptcies, Tewari says. The bureaus have then parsed those files electronically and appended the data to credit reports, he continues.
Problems arose because the credit bureaus’ tech systems could not always link the court documents to the right person when the courts provided only a name and address, Tewari maintains. Courts often limit information in their records to those two identifiers because they’re reluctant to divulge additional identification that criminals could intercept and use to commit fraud, he says.
Tewari traces the bureaus’ inaccuracies in matching court records to the right people to what he calls the bureaus’ “DNA.” The bureaus are accustomed to receiving “clean” information from lenders on a regularly scheduled basis. Conversely, some of the LexisNexis Risk Solutions data, gathered from obscure places like county deed offices, may arrive in a form that’s far from clean, he notes.
 However, that lack of court information or inconsistencies in the presentation of that information doesn’t pose problems for LexisNexis Risk Solutions because the company cleans the data before analyzing it. Tests indicate its linking methodology works accurately with just a name and address more than 99.9 percent of the time, Tewari contends. Thus, the company can establish that John Smith at 1234 Maple Street is the same person as John A. Smith at 1234 Maple Street, he says. He considers that linking technology the core of the company’s operations.
The information LexisNexis Risk Solutions can supply becomes vital to lenders because studies indicate that people who have a lien or judgment on file are twice as likely as people without them to default on a consumer loan and five times as likely to default on a mortgage, Tewari says. “The data didn’t become less important because the credit bureaus decided not to include it anymore,” he maintains. “It’s still just as predictive as it was.”
Meanwhile, other types of information can also help lenders make decisions, notes Eric Lindeen, vice president of marketing for ID Analytics, a credit risk and fraud risk management company that offers a credit score called Credit Optics, which it bases on a combination of traditional and alternative credit data.
Alternative credit data is defined as anything the credit bureaus don’t include in their reports, Lindeen says. Examples include the bills consumers pay for cell phones, utilities and cable television, he notes, adding that rent is also sometimes considered alternative credit data. The category also encompasses records from marketplace lenders.
A consumer’s tendency to pay those bills on time, late or not at all can reflect on creditworthiness, Lindeen maintains. That history becomes relevant for alt funders because the small businesses they serve constitute a hybrid of consumer and commercial credit, he says.
Using that data, ID Analytics can spot people who are good credit risks when the credit bureaus still consign them to “thin file” status — the limbo where applicants don’t have enough credit history to evaluate their creditworthiness, Lindeen maintains. About 60 percent of near-prime applicants qualify for credit when lenders factor in alternative data, according to an ID Analytics study he says. At the same time, alternative data can also expose weaknesses among individuals with excellent traditional credit scores, he observes.
Combining alternative data with traditional data has become more important with the bureaus’ decision to stop supplying data on liens and judgments, Lindeen says. Leaving out that data will raise some credit scores, and the effect will be strongest among near-prime individuals with good but not great traditional scores, he notes. With those consumers, a 10-point shift could make a big difference in qualifying for credit, he says.
“Even though it’s a small population, it’s a critical population,” Lindeen says of those newly minted prime applicants. They may number only one in a hundred of a particular funder’s portfolio, but they may advance to another risk pool and consequently invalidate a risk model, he suggests. Over time, risk managers will adapt to the change and oversee a “risk migration,” he predicts.
 Overall, between 6 percent and 9 percent of consumers will see their credit scores rise because of the bureaus’ new policy, Lindeen estimates. The change usually won’t exceed 20 points, he says. Still, about 700,000 will see an improvement of 40 points or more, he continues. “That’s a significant increase for a nontrivial population,” he says. “It’s likely their performance will stay the same as their score goes up.”
A study by VantageScore Solutions, the company that provides the VantageScore credit scoring model to the credit reporting bureaus, projected scores would increase an average of 10 points for slightly more than 8 percent of the scorable U.S. population.
Those changes are characterized as “minimal” by Francis Creighton, President & CEO of the Consumer Data Industry Association, a trade group that represents the three major credit bureaus as well as about a hundred other companies – mostly smaller credit bureaus around the country, resellers of credit bureau information and background screening companies.
The credit bureaus decided to curtail reporting of judgments and liens as part of the National Consumer Assistance Plan, or NCAP, Creighton says. NCAP is an agreement reached in March 2015 among the three major credit bureaus and the attorneys general of 31 states, who were pressing for fairness in credit reports. Many observers call NCAP a “settlement” but the agreement did not result from a lawsuit, he notes.
Under NCAP, the bureaus will continue to include bankruptcies in their reports because the records meet the standard of providing a name, address, Social Security number and date of birth and because visits to the courthouse to update records occur at least every 90 days. About half of liens don’t meet those standards and will be removed from credit reports, and nearly all judgments fail to adhere to the standard and will no longer appear on the reports.
Although Creighton declines to say how many consumers were victims of credit reporting errors, he emphasizes the severity of the problem for each victim. “If you were one of the people who had a name similar to somebody else or a similar Social Security number, it would impact you a lot,” he maintains. “I don’t know how widespread it was, but it was disruptive enough for individual people that it’s better just not to have it.”
A Federal Trade Commission study released in 2013 reported that a sample of 1,000 credit reports indicated that 25 percent had at least one error that could reduce scores, according to published reports. Such findings prompted state attorneys general to seek remedies that resulted in NCAP.
The bureaus planned to implement another major portion of NCAP in September when they were to begin waiting 180 days before reporting medical debts, Creighton notes. At the same time, debts for medical expenses covered by insurance policies were to be omitted from credit reports, he says.
Changes brought by NCAP represent part of ongoing efforts to improve the system, according to Creighton. “We want accurate information in the reports,” he says. “That’s good for everybody.”