Banking
Online Lenders Beat Credit Unions, Friends, and Family as Primary Source of Credit
July 14, 20197% of small businesses generating less than $5 million/year in revenue relied on online lenders as their primary source of credit in the last quarter, according to the latest Private Capital Access Index published by Pepperdine Graziado Business School. 3% relied on credit unions as their primary source and 6% relied on friends and family.
Banks were the most popular. 19% relied on large banks as their primary source of credit and 12% relied on community banks.
38% said they didn’t have any source of credit at all.
Sticking with the under $5 million/year segment, 45% of respondents explained that their primary source of credit had become so simply because they were able to qualify for it. 21% said their primary source became so because they couldn’t qualify for any other source.
Meanwhile, merchant cash advances, online business loans, and factors experienced among the lowest reported approval rates for businesses of all sizes. Of those businesses that applied for financing, the success rate in obtaining funds are as follows:
| Financing Type | Success Rate |
| Business credit card | 65% |
| Trade credit | 57% |
| Personal loan | 51% |
| Lease | 48% |
| Bank loan | 41% |
| Online lender | 38% |
| Merchant cash advance | 31% |
| Asset Based Lender | 28% |
| Factor | 23% |
| CDFI/Credit Union | 18% |
While bank loans came in at 41%, revenue was a major determining factor. 88.9% of businesses doing $5 million to $100 million/year in revenue successfully obtained a bank loan while only 31.6% of businesses doing less than $5 million/year in revenue successfully obtained a bank loan.
OnDeck Canada, Credit Union Announce Partnership
July 11, 2019 Today sees the partnership of OnDeck Canada and Coast Capital Savings, the first collaboration of its kind in Canada, being between an online lending company and a federal credit union.
Beginning this month, small business members of Coast Capital will be able to apply for term loan financing from OnDeck Canada of up to CAD$250,000 online, in branch, and via the Coast Capital Contact Centre. And as a perk of partnering with an alternative financing company, Coast Capital members will benefit from the fast turnaround times for approvals and funds being made available that are typical of the industry, with waits being as short as one day.
The move comes as OnDeck Canada is expanding to Quebec, paralleling Coast Capital’s efforts to spread across the nation, beyond its home of British Colombia. Both parties appear to be approaching the partnership with similar visions of where it will take them, with Tiffany Kayar, the OnDeck Canada Communications Manager, explaining that OnDeck is able to further help fund those small businesses who have been historically underserved by alternative financing, and Coast Capital will benefit from a greater national presence.
It is one more notch on OnDeck’s belt of partnerships, coming after the online lender linked with JPMorgan Chase in 2017 and PNC Financial Services Group last year to extend loans to businesses.
And for Coast Capital, which has the largest membership base of any credit union in Canada, it is a development that is consistent with their history of innovation. Having offered Canada’s first free checking account from a full-service financial institution and Help Extras®, which further assist members with investing, this opening up of funding channels to small business owners further cements Coast Capital’s position as a unique non-bank choice for finance management.
With small businesses comprising 98% of Canadian businesses, this partnership is hoping to provide support for such a large sector of the country’s economy. Saying in a press release that “As the proven leader in online small business lending, OnDeck Canada is delighted to partner with Coast Capital to offer online financing to its small business customers, ensuring that their unique and ever-evolving needs are met faster than ever with the power of automation and a world class digitized customer experience,” Neil Wechsler, CEO of OnDeck Canada, is confident that the synergy between OnDeck’s tech and Coast Capital’s membership will benefit the Canadian business community. Just as Derek Turner, Head of Small Business at Coast Capital, is sure that the partnership will “deliver the Coast Capital experience that so many members already enjoy, to even more people across Canada.”
Canadian Lenders Association to Host Open Banking Summit on July 10th
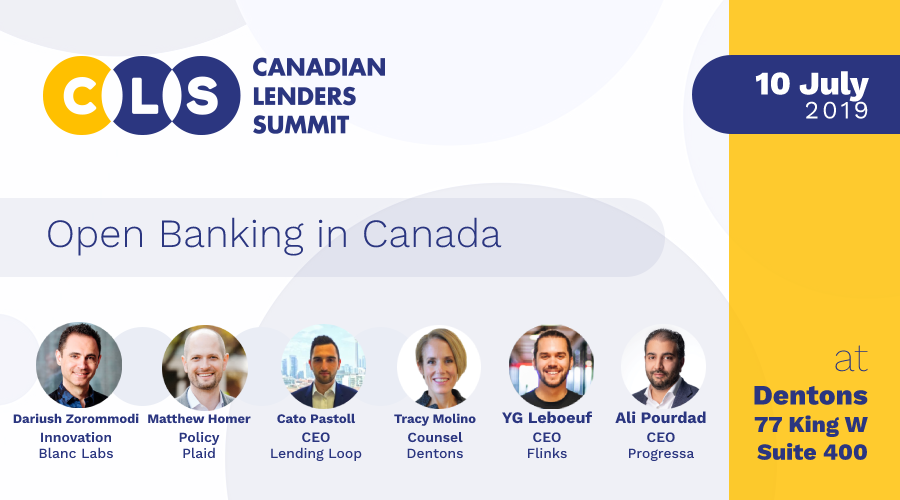
June 27, 2019The Canadian Lenders Association will be hosting its Open Banking Summit on July 10th at Dentons Toronto. It begins at 8am and ends at 11am. This is the third in their event series, and will tackle topics in Open Banking and Big Data in Canada. They will discuss how the industry can best work toward an open data economy in Canada. Join the amazing panel of industry leaders.
The total cost to attend is CA$79.08. You can register here.
Credit Invisibles Recap – Presented by Canadian Lenders Association in Toronto
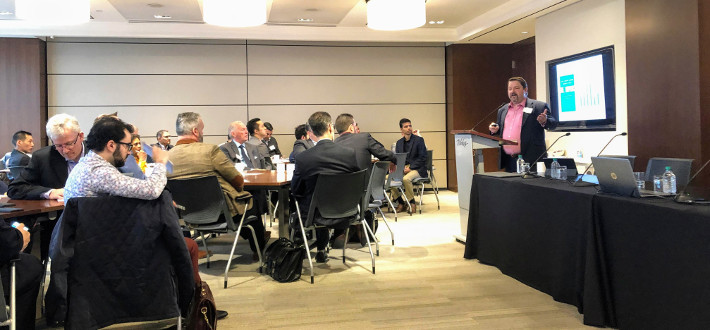
June 9, 2019The Canadian Lenders Association’s (CLA) workshop on credit invisibles and credit deserts was held at the Toronto law offices of Blake, Cassels & Graydon on June 5th. Situated in the financial district with views of the CN Tower, Michael Turner of Policy and Economic Research Council (PERC) kicked off the morning with a presentation on credit invisibility.
Using data from TransUnion Canada, PERC’s research showed that 36.5% of all credit files in Ontario, the most populous province, have between 0-2 trade lines. Anything fewer than three was considered to be credit invisible. The numbers were similar for Quebec and British Columbia at 33.7% and 37.2% respectively. Meanwhile, in sparsely populated Yukon, the percentage of invisibility is over 65%.
Credit deserts were geographic areas where invisibility was highly concentrated.
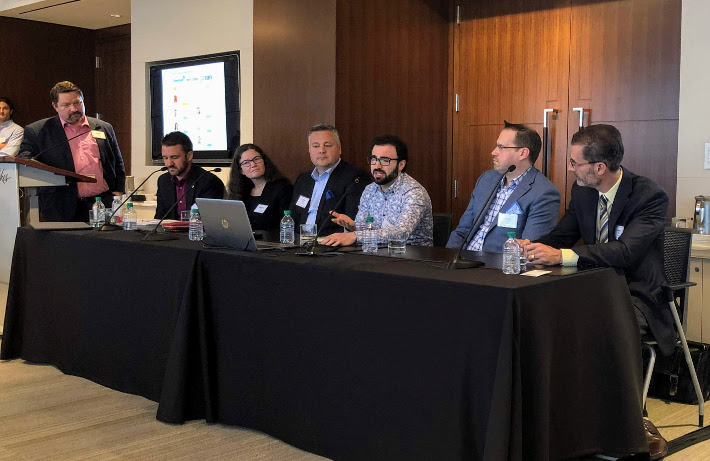
The panel that followed affirmed PERC’s research that there is a lack of available credit data on a significant portion of the population and that geographics play a role. Panelists included Jason Appel, EVP & Chief Risk Officer of goeasy ltd., Glenn Waine, Head of Data Science at TransUnion, Elizabeth Sale, Partner at Blake, Cassels & Graydon LLP, Tony Vardy, COO at Progressa, Vahan Der Kaloussian, Director of Data Science at Capital One, and Christopher Grnak, CRO & EVP and Trust Science.
A video recording of the presentations is below:
Small Businesses Rank Online Lenders More Transparent Than Big Banks
April 16, 2019When it comes to business loans, small businesses say online lenders are more transparent than big banks.
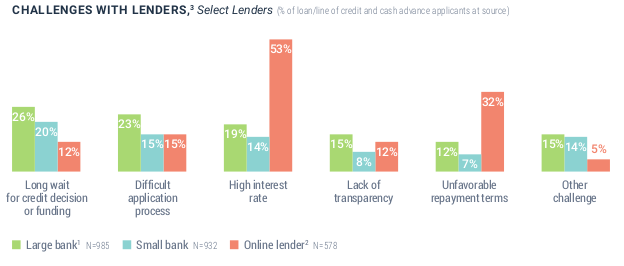
Specifically, 15% of respondents to a Federal Reserve survey reported challenges with transparency experienced at big banks versus only 12% with online lenders. Small businesses also ranked big banks worse on credit decision wait times, application process difficulty, and other unspecified challenges.
The Federal Reserve survey examined small businesses with less than 500 employees.
Small banks fared the best on transparency, payment terms, and interest rates.
Lyft IPO Follows a Foray into Finance Business
March 29, 2019 Lyft had its IPO today in the same week it announced that it was offering a debit card to its drivers. The company announced the launch of “Lyft Driver Services,” a suite of services for Lyft drivers including Lyft Direct, a no-fee bank account and debit card. The Lyft Direct debit card will allow drivers to instantly access their earnings after each ride, according to a company statement on its Medium page. This is an extension of Express Pay, which allows drivers to cash out on their earnings right away, rather than wait for the pay cycle to end.
“The traditional biweekly paycheck falls short of serving today’s workers, and the rising costs of maintaining a bank account disadvantage them further,” Lyft COO Jon McNeill explained in a statement. “Americans pay an average of $163/year in banking fees. Minimum balances are often greater than what many people can save, and most cash-back programs require an above-average credit score. We’re fixing that for our drivers.”
The Lyft Direct debit card has 4% cash-back on select restaurant purchases, 2% on gas, and 1% on groceries. Additionally, Lyft will offer its drivers a no-fee bank account with access to over 20,000 fee-free ATMs. Lyft is working with Oklahoma-based Stride Bank on this program. Stride Bank will manage all of the drivers’ bank accounts.
Last April, Uber released the Uber Visa debit card with Go Bank which also allows drivers to get paid instantly. Like the Lyft Direct debit card, the Uber debit card also gives users cash-back, like 3% on Exxon and Mobil gas, 2% on Walmart purchases and 8% on your Sprint bill.
Uber is no stranger to finance. In fact, the company once offered a product akin to an MCA where drivers were offered money up front in exchange for a percentage of their future fares, according to a deBanked story from 2016. That arrangement was made by Clearbanc. Uber also got into the leasing business with its leasing program, Xchange Leasing. But that was phased out beginning in 2017 due to myriad problems, including losses, an FTC lawsuit that dealt with misrepresenting the program, and an FTC complaint, according to a December 2018 post on The Simple Dollar, a personal finance website. The complaint accused Uber of connecting its drivers with subprime auto companies and dealers that provided interest rates significantly higher than industry averages.
So while Uber offers its drivers a debit card, it has backed away from other financing. With Lyft a step behind, will Lyft stop with this new debit card? Or perhaps learn from Uber’s mistakes and expand into the lending space?
The Lyft stock (NASDAQ: LYFT) started at $72 and closed its first day of trading at $78.29, up 8.7 percent.
Two Cultures Collided, Gently
March 25, 2019
Banks are heavily regulated. Factoring companies are not. The two don’t always mix. So it was interesting last July when Axiom Bank, a regional bank in Florida, acquired Allied Affiliated Funding, a factoring company based in Texas.
Fast forward nine months and the merger of the two companies has been surprisingly easy, according to Axiom CEO Daniel Davis.
“Banking and factoring are two different worlds, two different cultures,” Davis said. “[But] the challenges that we expected didn’t occur.”
Davis explained that the biggest challenge with a bank acquiring a factor is reconciling a bank’s credit risk with a factor’s, which are different because banks are more or less governed by regulatory standards while factors are not.
“Good factoring shops have guidelines too,” Davis said, “and we’re lucky to be involved with Allied which does share that high level of policies, procedures and internal controls.”
Regardless of how well a factor self-regulates, factoring companies have virtually no regulations compared to a bank, and this may give regulators a little pause to see a bank mixing with a factor.
“It is a challenge,” Davis said about merging a factoring company with a bank regarding regulations. “What the regulators want to see you do, whether you’re acquiring a factoring company or entering into a new product or service…what they’re most concerned with is that you’ve put the policies and procedures and risk management in place to actively manage and monitor that business.”
But so far, so good, according to Davis, who said that the factoring business has grown 30% in receivables since the July 2018 acquisition. Allied Affiliated Funding, which has retained its name, is now known as the factoring division of Axiom Bank. The bank has 24 branches throughout Florida, 22 of which are located inside Walmart stores. As far as marketing the relatively new factoring product, Davis said that while they do some brand marketing, the Allied factoring division gets most of its business from referrals, including attorneys and accountants.
He said that they also get referrals from banks. For instance, if a bank’s underwriting standards makes it such that it cannot keep a loan, the bank might send the loan to Axiom for it to be restructured as a factoring deal.
Small Community Banks Power Fintech Revolution
February 15, 2019 “A few years back there was a lot of disruption talk about how the fintechs were going to destroy the banks,” said Jo Ann Barefoot, co-founder of Hummingbird Regtech and a former deputy U.S. Comptroller of the Currency, which regulates national banks. “There’s much more talk in the last few years about the need for banks to partner [with fintechs].”
This quote was cited in a CNBC story published today and judging from the recent bank partnerships with some of the largest fintech companies – including Square, Stripe and Robinhood – this could not be more evident. The CNBC story points out that most of these fintech/bank partnerships are not with household name banks, but rather with small community banks that welcome the business. These banks, including Sutton Bank, headquartered in Attica, OH, Cross River Bank, headquartered in Fort Lee, NJ, and Celtic Bank, headquartered in Salt Lake City, UT, are handling the banking activities for these growing fintechs – activities like holding customer deposits and underwriting consumer and business loans. And significantly, making sure that everything is up to snuff with government regulations.
A number of fintechs, including Square and SoFi, have tried to take the banking component of their businesses into their own hands by applying to become an ILC bank. But they have been met with tough resistance, much of it coming from, interestingly, community banks.
“No one envisioned when they wrote the ILC charter that we would have fintech companies that finance mortgages and student loans from private equity capital and not deposits,” President and CEO of the Consumer Bankers Association told deBanked last year. “It’s a new world. Like with all rules and regulations, federal regulators should periodically review longstanding policy.”
So far, the opposition has been relatively successful but time will tell if it keeps up. Square and SoFi withdrew their ILC loan their applications, but Square eventually reapplied. At the 2018 Money 2020 conference in Las Vegas, SoFi CEO Anthony Noto said he would entertain seeking ILC bank status.