Banking
Fintech Inevitable, But Petrou Says Risks Abound
February 12, 2019 At the end of last week, two large regional banks, BB&T and SunTrust announced that they are merging. The entity will be the sixth largest U.S. bank and the largest bank merger since the 2008 financial crisis. A MarketWatch story yesterday indicated that large bank mergers are part of a somewhat recent trend, citing the mergers of Chemical Bank with TCF Bank, and Key Bank with First Niagara, both in 2016. (The number of bank acquisitions have been static in 2017 and 2018, with 252 and 253 banks, respectively, according to American Banker.)
If large bank mergers are a trend, Managing Director of Federal Financial Analytics Karen Petrou told MarketWatch that this is in part because banks realize that they can combine resources to develop mobile banking capabilities to compete with online banks.
“If banks don’t come up with ways to innovate, they die,” Petrou told MarketWatch yesterday. “Then consumers are left to do their banking with nonbanks.”
Federal Financial Analytics, where Petrou is the managing director, is a Washington, D.C.-based consulting firm and Petrou is a highly regarded voice in the financial regulation space.
While Petrou acknowledges that online banking is the only alternative if traditional banks don’t innovate, she sees serious problems in fintech which she outlined in a paper published earlier this month, according to American Banker.
For instance, she wrote about the danger of a company like Amazon getting into banking and being able to charge individuals different amounts for the same item based on its knowledge of how much money the customer has. Or, the implementation of better banking policies for people who exercise and eat healthier. Petrou says this favors wealthier people with more time for exercise and greater access to more expensive, healthier food.
“I am all for technology,” Petrou said. “But I spent a lot of time when I was a student at MIT studying tech policy, and there is one after another example of seemingly promising technologies with terrible, unintended consequences.”
Joust Launches Banking Platform for Entrepreneurs
January 17, 2019 Lamine Zarrad, CEO, Joust
This week marked the launch of the Joust iOS app, a platform for freelancers and small businesses that provides banking, payments, collections and invoice factoring solutions. The Android App is scheduled for release on February 1, 2019.
“We straddle three different domains: payments, merchant processing, and factoring, all in one app,” said Joust co-founder and CEO Lamine Zarrad. “Most freelancers have a bank account, then add a payments account using Stripe or Paypal, or both.Then you need an invoicing tool. Now you’ve accumulated three or four different tools to bill your customers. What Joust did, in partnership with [our banking partner], is we were able to consolidate all of these tools.”
Zarrad said that Joust has three categories of customers: traditional small businesses, part-time freelancers, and full-time freelancers, or “solopreneurs” – people who dedicate all of their efforts to their entrepreneurial endeavors.
Some of the most common financial problems among solopreneurs that Joust aims to fix are stabilization of cash flows, gap financing, and integration of payments and banking.
In conjunction with an online banking platform, called Cambr, Joust provides customers with a bank account as well as a merchant account, which gives them the ability to accept credit cards directly into their account, Zarrad said. Cambr was created by StoneCastle, a technology enabled financial services company managing over $15 billion on behalf of its clients. It stores cash within a network of 850 community banks in all 50 states.
Another significant pain point for freelancers is collection of unpaid receivables. Zarrad said that entrepreneurs in general lost 14% of their receivables to non-paying or extremely delayed paying clients in 2018. The Joust platform/app also includes a collections service, which is a series of five emails strategically spaced out.
“Most bills don’t get paid not because people don’t want to pay, but because it’s been de-prioritized,” Zarrad said, “and having a third party act on behalf of a freelancer is immensely more powerful.”
If there is no response after the fifth email, Joust then outsources the collections. Having a Joust bank and merchant account is completely free, with the exception of credit card processing fees, which Joust passes on to the customer. Joust anticipates making money in part by bringing business accounts to StoneCastle and primarily from its factoring capabilities. Zarrad said they make 1 to 6% on guaranteeing invoices.
Trained at OnDeck, LendingFront Founders Help Banks Lend to Small Businesses
January 9, 2019 Yesterday LendingFront announced that it has raised $4 million to help deliver its white label software designed to help banks and other financial institutions lend to small businesses. The company was founded in 2015 by two former OnDeck employees, Jorge Sun and Dario Vergara.
Sun was the Chief Credit Officer at OnDeck from 2007 to 2012 and said he was the company’s third hire. Vergara joined OnDeck as its Chief Technology Officer in 2008 and was also among the first to join the company, Sun said. They both left before OnDeck went public in 2014 and took other jobs before reconnecting to create LendingFront together. Sun said that it is very difficult to create a technology company inside a large bank, which is what he tried to do in his job at Capital One, following his time at OnDeck. Vergara was working as VP of Technology at Bonobos, an online clothing company.
As Sun began talking with Vergara about going out on their own, he recalled telling Vergara: “There are no platforms in this space directly created to help lenders become more efficient…We’ve built this once [at OnDeck], let’s build it again. But the difference now is it’s strictly a technology company. We take no risk, we don’t lend. All we’re doing is powering other lenders.”
Sun said that LendingFront is “lender agnostic,” in that they license out their proprietary lending platform to any financial institution, including banks, community banks, leasing companies and Community Development Financial Institutions.
Their customers pay them a licensing fee and the customer, say a bank, sets its own parameters with regard to underwriting. The platform simplifies the underwriting process, but completely allows for customization and design of the customer experience, Sun said.
The idea of helping banks become better online lenders is not completely unique. In fact, the founders’ former employer, OnDeck, recently launched a separate entity called ODX, with the mission of making banks better lenders to small businesses.
But Sun said that while ODX and LendingFront both help banks, there is a difference between the two. He said the difference is that ODX is more of a full service shop acting on behalf of a bank.
“With us, a bank is using our platform like using Excel…versus [using] Excel and then giving it to a different company and saying ‘use Excel on our behalf.’”
Sun said that customers have funded $150 million through the LendingFront platform since they started licensing it out in 2016. They previously raised $1.6 million in 2016 and they employ 24 people in an office in New York.
Square Renews Effort to Become a Bank
December 19, 2018 Square has plans to refile paperwork with state and federal regulators to open a wholly owned bank in Utah, according to a report in The Wall Street Journal today. In 2017, the company applied with the Federal Deposit Insurance Corp (FDIC) for a licence to become an Industrial Loan Company (ILC) bank, but it withdrew the application at the beginning of July 2018.
An ILC bank can take deposits and can be owned by a non-bank. It is also exempt from certain regulations that traditional banks must follow, making the ILC bank structure highly controversial. Critics say that ILC banks are very risky because they can engage in commercial activity outside of banking, which could lose money and jeopardize the bank.
“ILC banks were meant to serve a certain type of industrial worker [in the early 1900s] that had trouble finding a commercial bank they could bank with,” said Chris Cole, Senior Regulatory Counsel at Independent Community Bankers of America (ICBA), a trade group.
“Now we don’t have that problem anymore…this [ILC bank] charter is completely outdated [and is] a loophole that should be closed so that the owners of these bank-like institutions are restricted in the same way that commercial banks are restricted,” he said.
Proponents of ILC banks, like the fintechs that seek ILC status, say that becoming a bank can better serve their customers. Under the 2010 Dodd-Frank Act, which came in response to the Great Recession, there was a moratorium on establishing ILC banks because they were deemed to be a risk to the U.S. banking system. That moratorium was lifted in 2013 and over the last several years, a handful of fintechs have applied to get an ILC bank charter license.
SoFi applied for a license and later withdrew its application in 2017 amid a scandal related to its former CEO. But its current CEO, Anthony Noto, mentioned the possibility of pursuing ILC status again at the Money 20/20 conference in October.
NelNet, which services student loans, applied for an ILC license in June of this year and later withdrew its application in October.
Open Banking — A U.S. Pipe Dream or Near-Term Reality?
December 18, 2018 Some alternative funders are anxious for “open banking” to become the gold standard in the U.S., but achieving widespread implementation is a weighty proposition.
Open banking refers to the use of open APIs (application program interfaces) that enable third-party developers to build applications and services around a financial institution. It’s a movement that’s been gaining ground globally in recent years. Regulations in the U.K., a forerunner in open banking, went into effect in January, while several other countries including Australia and Canada are at varying stages of implementation or exploration.
For the U.S., however, the time frame for comprehensive adoption of open banking is murkier. Industry participants say the prospects are good, but the sheer number of banks and the fragmented regulatory regime makes wholesale implementation immensely more complicated. Nonetheless, industry watchers see promise in the budding grass-roots initiative among banks and technology companies to develop data-sharing solutions. Regulators, too, have started to weigh in on the topic, showing a willingness to further explore how open banking could be applied in U.S. markets.
Open banking “is a global phenomenon that has great traction,” says Richard Prior, who leads open banking policy at Kabbage, an alternative lender that has been active in encouraging the industry to develop open banking standards in the U.S. “It’s incumbent upon the U.S. to be a driver of this trend,” he says.
The stakes are particularly high for alternative lenders since they rely so heavily on data to make informed underwriting decisions. Open banking has the potential to open up scores of customer data and significantly improve the underwriting process, according to industry participants.
“Open banking massively enables alternative lending,” says Mark Atherton, group vice president for Oracle’s financial services global business unit. What’s missing at the moment is the regulatory stick to ensure uniformity. Certainly, data sharing is gradually becoming more commonplace in the U.S. as banks and fintech companies increasingly explore ways to collaborate. But even so, banks in the U.S. are currently all over the map when it comes to their approach to open banking, posing a challenge for many alternative lenders. Many alternative lenders would like to see regulators step in with prescriptive requirements so that open banking becomes an obligation for all banks, as opposed to these decisions being made on a bank-by-bank basis. Especially since many consumers want to be able to more readily share their financial information, they say.
“It will create huge value to everyone if that data is more accessible,” says Eden Amirav, co-founder and chief executive of Lending Express, an AI-powered marketplace for business loans.
Some global-minded banks like Citibank have been on the forefront of open banking initiatives. Spanish banking giant BBVA is also taking a proactive approach. In October, the bank went live in the U.S. with its Banking-as-a-Service platform, after a multi-month beta period. Also in October, JPMorgan Chase announced a data sharing agreement with financial technology company Plaid that will allow customers to more easily push banking data to outside financial apps like Robinhood, Venmo and Acorns.
There are several other examples of open banking in action. Kabbage customers, for instance, authorize read-only access to their banking information to expedite the lending process through the company’s aggregator partners, says Sam Taussig, head of global policy at Kabbage.
Also, companies such as Xero and Mint routinely interface with banks to put customers in control of their financial planning. And companies like Plaid and Yodlee connect lenders and banks to help with processes such as asset and income verification.
Some banks, however, are more reticent than others when it comes to data sharing. And with no regulatory requirements in place, it’s up to individual banks how to proceed. This can be nettlesome for alternative lenders trying to get access to data, since there’s no guarantee they will be able to access the breadth of customer data that’s available. “As an underwriter, you want the whole financial picture, and if data points are missing, it’s hard to make appropriate lending decisions,” Taussig says.
The problem can be particularly acute among smaller banks, industry participants say. While the quality of data you can get from one of the money-center banks is quite good, “as you go down the line, it becomes a little less consistent,” says James Mendelsohn, chief operating officer of Breakout Capital Finance. For these smaller banks, the issue is sometimes one of control. There’s a feeling among some community banks, that “if I make it easier for my small business customers to get loans elsewhere, I’m done,” says Atherton of Oracle.
Absent regulatory requirements, alternative lenders are hoping that this initial hesitation among some banks changes over time as they continue to gain a better understanding of the market opportunity and as more of their counterparts become open to data sharing through APIs.
Open banking could be a boon for banks in that it would enable them to service customers they probably couldn’t before, says Jeffrey Bumbales, marketing director at Credibly, which helps small and mid-size businesses obtain financing. Open banking makes for a “better customer experience,” he says.
One challenge for the U.S. market is the hodgepodge of federal and state regulators that makes reaching a consensus a more arduous task. It’s not as simple here as it may be in other markets that are less fragmented, observers say.
Major rule-making would be involved, and there are many issues that would need attention. One pressing area of regulatory uncertainty today is who bears the liability in the event of a breach—the bank or the fintech, says Steve Boms, executive director of the Northern American chapter of the Financial Data and Technology Association. Existing regulations simply don’t speak to data connectivity issues, he says.
To be sure, policymakers have started to give these matters more serious attention, with various regulators weighing in, though no regulator has issued definitive requirements. Still, some industry participants are encouraged to see regulators and policymakers taking more of an interest in open banking.
A recent Treasury Report, for example, notes that as open banking matures in the United Kingdom, “U.S. financial regulators should observe developments and learn from the British experience.” And, The Senate Banking Committee recently touched on the issue at a Sept. 18 hearing. Industry watchers say these developments are a step in the right direction, though there’s significant work needed, they say, in order to make open banking a pervasive reality.
“We’re seeing the pace and interest around these things picking up pretty significantly,” Boms says. Even so, it can take several years to implement a formal process. “The hope is obviously as soon as possible, but the financial services sector is a very fragmented market in terms of regulation. There’s going to have to be a lot of coordination,” Boms says.
Another challenge to overcome is customers’ willingness to use open banking. Many small business owners are more comfortable sending a PDF bank statement versus granting complete access to their online banking credentials, says Mendelsohn of Breakout Capital Finance. “There’s a lot more comfort on the consumer side than there is on the small business side. Some of that is just time,” he adds.
Certainly sharing financial data is a concern—even in the U.K. where open banking efforts are well underway. More than three quarters of U.K. respondents expressed concern about sharing financial data with organizations other than their bank, according to a recent poll by market research body, YouGov. This suggests that more needs to be done to ease consumers into an open banking ecosystem.
The topic of data security came up repeatedly at this year’s Money20/20 USA conference in Las Vegas. How to make people feel comfortable that their data is safe is a pressing concern, says Tim Donovan, a spokesman for Fundbox, which provides revolving lines of credit for small businesses. Clearly, it’s something the industry will have to address before open banking can really become a reality in the U.S., he says.
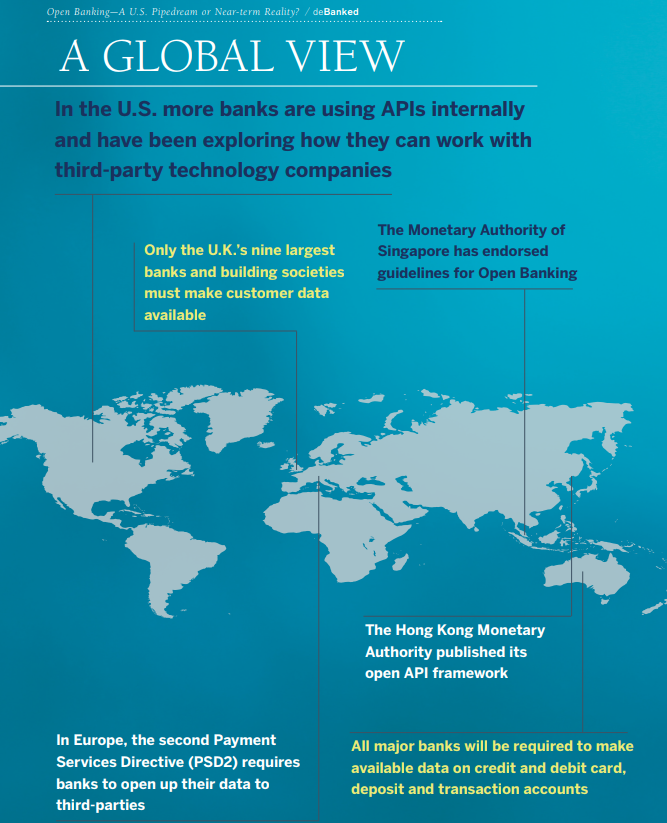
Despite these challenges, many market watchers feel open banking in the U.S. is inevitable, given the momentum that’s driving adoption worldwide. Several countries have taken on open banking initiatives and are at varying states of implementation—some driven by industry, others by regulation. Here is a sampling of what’s happening in other regions of the world:
In the U.K., for example, the implementation process is ongoing and is expected to continually enhance and add functionality through September 2019, according to The Open Banking Implementation Entity, the designated entity for creating standards and overseeing the U.K’s open banking initiative.
At the moment, only the U.K.’s nine largest banks and building societies must make customer data available through open banking though other institutions have and continue to opt in to take part in open banking. As of September, there were 77 regulated providers, consisting of third parties and account providers and six of those providers were live with customers, according to the U.K. open banking entity.
In Europe, the second Payment Services Directive (PSD2) requires banks to open up their data to third parties. But implementation is taking longer than expected—given the large number of banks involved. By some opinions, open banking won’t really be in force in Europe until September 2019, when the Regulatory Technical Standards for open and secure electronic payments under the PSD2 are supposed to be in place.
In Australia, meanwhile, the country has adopted a phase-in process to take place over a period of several years through 2021. Starting in July 2019, all major banks will be required to make available data on credit and debit card, deposit and transaction accounts. Data requirements for mortgage accounts at major banks will follow by February 1, 2020. Then, by July 1 of 2020, all major banks will need to make available data on all applicable products; the remaining banks will have another 12 months to make all the applicable data available.
For its part, Hong Kong is also pushing ahead with plans for open banking. In July, the Hong Kong Monetary Authority published its open API framework for the local banking sector. There’s a multi-prong implementation strategy with the final phase expected to be complete by mid-2019.
Singapore, by contrast, is taking a different approach than some other countries by not enforcing rules for banks to open access to data. The Monetary Authority of Singapore has endorsed guidelines for Open Banking, but has expressed its preference to pursue an industry-driven approach as opposed to regulatory mandates.
Other countries, meanwhile, are more in the exploratory phases. In Canada, the government announced in September a new advisory committee for Open Banking, a first step in a review of its potential merits. And in Mexico, the county’s new Fintech Law requires providers to provide fair access to data, and regulators there are reportedly gung-ho to get appropriate regulations into place. Still other countries are also exploring how to bring open banking to their markets.
The U.S. meanwhile, is on a slower course—at least for now. More banks are using APIs internally and have been exploring how they can work with third-party technology companies. Meanwhile, companies like IBM have been coming to market with solutions to help banks open up their legacy systems and tap into APIs. Other industry players are also actively pursuing ways to bring open banking to the market.
As for when and if open banking will become pervasive in the U.S., it’s anyone’s guess, but industry participants have high hopes that it’s an achievable target in the not-too-distant future.
Thus far, there has been little pressure for banks to adopt open banking policies, says Taussig of Kabbage. But this is changing, and things will continue to evolve as other countries adopt open banking and as pressure builds from small businesses and consumers in an effort to ensure the U.S. market stays competitive, he says. Open banking “is going to happen in the near future,” Taussig predicts.
Entegra Bank Chooses Velocity Solutions to Power Its Small Business Digital Lending
December 18, 2018 Velocity Solutions announced today that its Akouba digital lending platform was selected by Entegra Bank to power the bank’s digital lending for its small and medium-sized business customers. Akouba provides community and regional banks with origination and underwriting services.
“We selected Akouba not only for their cutting-edge technology and willingness to work with us, but for the very positive impact we believe this will have on the bank’s bottom line and on the customer experience,” said Charles Umberger, Executive VP and Chief Lending Officer for the Franklin, NC-based Entegra Bank.
According to the Velocity Solutions statement, Akouba is the only small business digital lending solution endorsed by the American Bankers Association (ABA). Akouba was endorsed by the ABA back in February 2017.
“The ABA’s endorsement will give lending institutions the assurance that Akouba’s solutions meet the highest standards,” said CEO of Akouba Chris Rentner, when they received the endorsement from the ABA. “In a rapidly changing lending environment, and with marketplace lenders disrupting the business lending space, our platform will help banks bring their customers the technology they have been lacking.”
In the same way that OnDeck’s ODX is trying to improve online lending for large banks, like Chase and PNC, Velocity’s Akouba does the same thing for regional banks.
“The small business loan application process is very time-sensitive and costly for banks, and there is a need to simplify and accelerate the process,” said Bryan Luke, chairman of ABA’s Endorsed Solutions Banker Advisory Council.
Velocity Solutions, which operates Akouba, is based in Fort Lauderdale, FL and employs over 100 people, according to Crunchbase. Entegra provides personal and business banking serves at 20 retail branches throughout Georgia, North Carolina and South Carolina.
Cross River Bank Raises $100 Million
December 11, 2018Cross River Bank, which provides banking services to fintech companies, announced last week the completion of a funding round of roughly $100 million. This was comprised of a $75 million equity investment from KKR, along with capital from Andreessen Horowitz, Battery Ventures, Rabbit Capital, and funding from new investors CredEase and Lion Tree. This adds to a $28 million raise a little over two years ago.
Cross River, which originated more than $5 billion in loans as of the end of August 2018, has developed partnerships with fintech leaders to build fully compliant and integrated products within the lending marketplace and payment processing spaces. They have about 15 lending platform partners, including fintech clients Affirm, Best Egg, RocketLoans, Coinbase and TransferWise.
According to the announcement, this new capital will be used to allow Cross River to continue building a complete banking platform where fintech companies can leverage best-in-class banking technology coupled with compliance.
“Cross River offers solutions to fintech companies by giving them access to a full suite of banking solutions and services in a single, fully compliant and innovative platform, making it an increasingly attractive and valuable franchise in a dynamic marketplace,” said Dan Pietrzak, Member and Co-Head of Private Credit at KKR, Cross River’s leading investor.
According to its website, Cross River was named “most innovative bank” by LendIt in 2017 and 2018. Founded in 2008, the Fort Lee, NJ, business-oriented bank has more than 180 employees.
Trump Administration Criticizes Postal Banking Concept
December 9, 2018 Earlier this week, a Trump administration report diminished the idea of having the United States Postal Service take on the role of a bank.
“Given the USPS’s narrow expertise and capital limitations, expanding into sectors where the USPS does not have a comparative advantage or where balance sheet risk might arise, such as postal banking, should not be pursued,” the report states.
This argument – that the USPS has no experience in banking – is the same that many banks presented when the idea was introduced in a 2015 report from the Office of the Inspector General. According to a June 2017 story in Tearsheet, a financial publication, those in favor of the idea of postal banking think that it could be a way for millions of unbanked or underbanked Americans to gain access to financial services. It could also create a new revenue stream for the perennially unprofitable USPS. (The USPS reported a net loss of $3.9 billion in fiscal year 2018, its 12th straight year of net losses.)
To those opposed to the idea, this would place a burden on an already struggling system, and would be unprofitable. While postal banking has the support of a number of high-ranking democrats, including Senator Elizabeth Warren of Massachusetts and Senator Kirsten Gillibrand of New York, postal bank has a surprising opponent: the National Council of Postal Credit Union (NCPCU).
According to a story in the Credit Union Journal, NCPCU board chair and CEO of Signature Federal Credit Union Becca Cuddy said, “Any new competition in the financial field is a threat to postal credit unions.” She suggested that a better strategy might be for third parties – possibly including banks – to partner with postal credit unions or the NCPCU “rather than try to reinvent the wheel.”
It is worth noting that postal banking did exist in the U.S. from 1911 to 1966. And according to the Pew Charitable Trusts, there are currently over 1.6 billion postal bank accounts, many in developed economies such as Japan, Brazil, France and Switzerland.