
Sean Murray is the President and Chief Editor of deBanked and the founder of the Broker Fair Conference. Connect with me on LinkedIn or follow me on twitter. You can view all future deBanked events here.
Articles by Sean Murray

Google Serves Low Blow to Merchant Cash Advance Seekers
December 2, 2015 Almost eighteen months ago, I explored whether or not Google was rigging the search results to benefit two lending companies they had equity investments in, Lending Club and OnDeck. At the time, both companies ranked at the top for highly coveted keywords even if they weren’t directly related to the user’s search query.
Now that those two companies are public, a company called Credit Karma seems to have inherited the top spots. And wouldn’t you know it, Google has also invested in them.
Google: loans
Google: personal loan
But that’s not the worst of it. Thanks (or no thanks rather!) to a relatively new search result feature called “People Also Ask,” one keyword recently started serving up results with a different kind of hidden agenda.
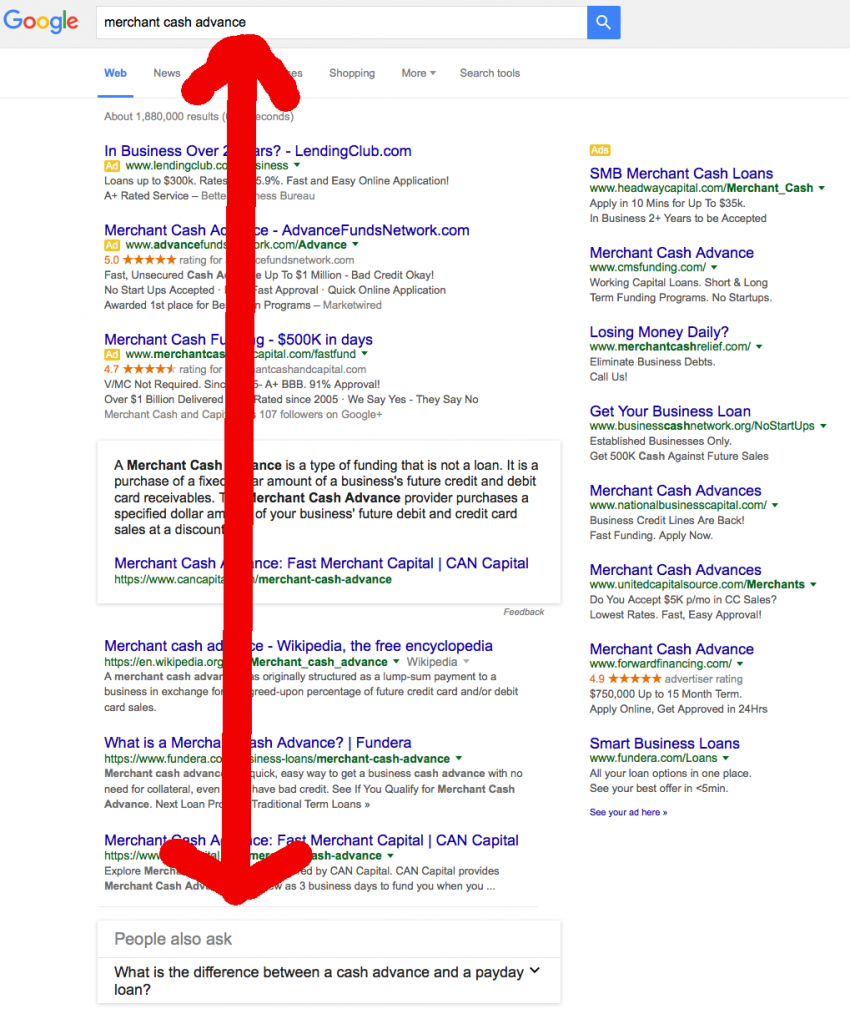
While my captured results may not be identical for everyone, I have conducted tests with other people on other devices and from other areas and it was present each time. With this box, Google is subtly planting the negative seed that payday loans and merchant cash advances are basically so identical that other people just like you are wondering what the difference between the two are. But here’s the rub, the two have nothing to do with each other and it’s unlikely so many people are asking that.
Pay no mind to the fact that the box makes reference to a “cash advance” not a “merchant cash advance.” The painstaking mishap could be innocently chalked up to an algorithmic error if only googling just cash advance revealed the same box in the results. But it doesn’t. Only merchant cash advance brings this up.
Comparing merchant cash advances to payday loans is straight out of the anti-merchant cash advance propaganda playbook. At least one Google-owned business lending company is actively lobbying against short term business lending and merchant cash advances in Washington so the placement and comparison of the People Also Ask box in their results is highly suspicious.
It’s no secret that Google is also directly lobbying in the online lending space too. One month ago, right before Google magically started to suggest to searchers that merchant cash advances and payday loans were related, Google formed a lobbying organization called Financial Innovation Now with Amazon and Apple. On their main agenda is online lending.
Given the suspicious search rankings for companies they have an equity stake in, I would not doubt for a second that something like this was manually inserted. I admit that my evidence and my case are weak, but given the circumstances, it’s quite possible there’s something deliberate happening here.
What do you think? Do you see this when you google merchant cash advance?
Funding Circle’s Sam Hodges Comments On OnDeck/JPM Announcement (Video)
December 2, 2015Earlier today, Funding Circle’s Sam Hodges appeared on Bloomberg TV to discuss the new OnDeck/JPMorgan Chase announcement. Hodges said he believes its the first step towards many banks working with marketplace lenders and reminded the panel that in the UK, his company already does that.
He was then asked if such a tight relationship even makes sense given the overwhelming consumer sentiment against banks these days. Watch what the video and how he responds below:
JPMorgan Chase and OnDeck Partner Up
December 1, 2015 Coming soon, when small businesses apply at a Chase bank for a loan under $250,000, there’s a good chance that OnDeck will be doing all the work. That’s because JPMorgan Chase and OnDeck announced a strategic partnership earlier today that is expected to commence in 2016.
A comment earlier in the day by Jamie Dimon hinted that something was coming. “We haven’t announced it yet, we’re going to be doing a thing with one of these peer-to-peer, small-business lenders,” Bloomberg reported.
That caused peer-to-peer lending industry advocates like Peter Renton of LendAcademy to speculate who that might be. He originally bet on Lending Club but posited that it could also be OnDeck, Funding Circle, or Kabbage.
When I asked Lending Club on twitter if they were slated to be JPM’s partner, I received a public reply back from a VP at OnDeck saying that it would in fact be them. By then the news had already been released.
The SEC filing states, “JPM will use the Company’s small business lending platform and the OnDeck Score® to serve its small business customers” and adds that they’re still in the process of building things out and finalizing agreements.
OnDeck (ONDK) which closed at $9.01 before the announcement is expected to soar on the news for the Wednesday open.
deBanked Nov/Dec Teaser
December 1, 2015The November/December issue of deBanked Magazine should go out in the mail at the end of this week. In the meantime, can you guess who is on the front cover of this issue?! Here’s your clue:
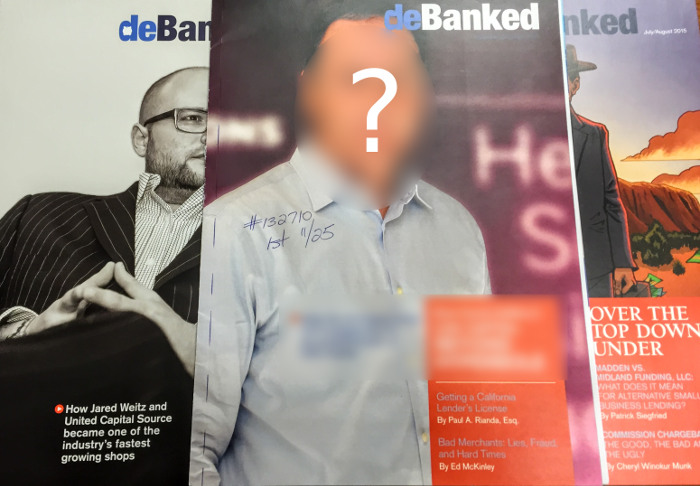
Jared Weitz, the CEO of United Capital Source, was on the cover of the previous September/October issue.
Shark Tank’s Barbara Corcoran Teams Up With OnDeck for Small Business Contest
November 29, 2015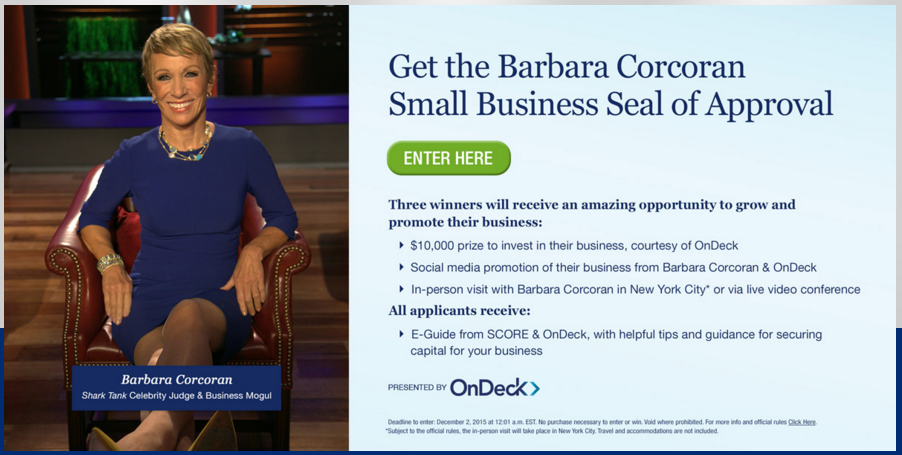 Barbara Corcoran, co-founder of The Corcoran Group and famous Shark Tank investor, has teamed up with small business lender OnDeck to support entrepreneurs through a contest. Three winners will be chosen for a $10,000 prize and they’ll also get to meet Barbara Corcoran.
Contest applicants are asked to enter what they would spend the $10,000 on to grow their business. The deadline to enter is December 2nd, 2015.
The partnership is significant because it marks yet another time that a Shark has crossed paths with online business lenders. Just one year ago, Kevin O’Leary became a spokesperson for IOU Financial.
I'm thrilled to announce a new partnership between O'Leary Financial & @IOUCentralInc this morning! http://t.co/ECJl1K5ZUC #smallbusiness
— Kevin O'Leary (@kevinolearytv) October 2, 2014
Also around that time, Kevin Harrington, an original Shark Tank investor before Mark Cuban or Lori Greiner, co-founded his own small business lending marketplace, Ventury Capital. Straight out of the OnDeck or merchant cash advance playbook, Ventury’s FAQ says their system “deducts a fixed, daily payment directly from your business bank account each business day.”
Watch Kevin Harrington explain his company here:
Of course there was the time that a merchant cash advance company (Total Merchant Resources) actually went on Shark Tank and pitched the sharks…
It seems that the show and the real world have a lot in common.
Will the Wild West of alternative lending stay that way?
November 24, 2015Comments on the regulatory future of alternative lending were included in a joint report prepared by Lendio and Dealstruck:
Blake hopes that governing agencies will offer reasonable policies that will encourage best-in-class business practices (to weed out the bad actors) without damaging the innovation and growth in the industry. Furthermore, Lendio highly recommends that any new or additional regulations come from the Federal level, rather than through a state-by-state patchwork of laws that will impose inconsistent and costly regulations on the online lenders.
– Brock Blake, Lendio CEO
Thoughtful regulation to ensure operators are performing with honesty and transparency is a good thing. And good players are stepping up to the plate to take a proactive stance regarding fair and transparent lending practices, executed ethically and with integrity. Fortunately for the small business lending market, the key lenders and marketplaces in the industry have used a blueprint of best practices that were established and implemented in the consumer lending space. It’s fascinating to think about how much room they have left to grow.
– Ethan Sentura, Dealstruck CEO
The report compiles other interesting pieces of data such as OnDeck’s share of the entire business loan market, which stood at less than a quarter of 1% just 1 year ago.
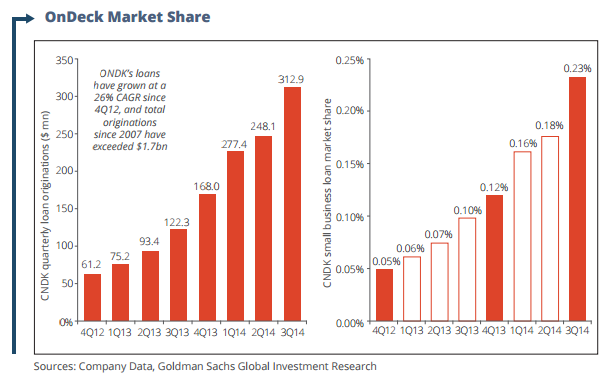
You can view Lendio and Dealstruck’s full report here.
Merchant Cash Advance APR Debate (Sean Murray v Ami Kassar)
November 24, 2015The other day, Inc. writer and loan broker Ami Kassar took some time out of his day from taking photos of his shadow in the park to engage me in a debate about the use of APRs in future receivable purchase transactions. He was apparently very bothered by my analysis of Square’s merchant cash advance program which has transacted more than $300 million to date.
To clarify my position here, I am indeed in favor of transparency, so long as it’s intelligent transparency. Coming up with phony percentages based on estimates and applying them to transactions where they don’t make sense is not transparency. Similarly, advocating that merchant cash advance companies and lenders alike move away from a dollar-for-dollar pricing model to one that requires the seller or borrower to do math or hire an accountant is also not transparency.
Even a Federal Reserve study that attempted to prove merchant cash advances were confusing inadvertently proved that APRs in general were confusing. If someone doesn’t know how to calculate an APR, then it’s unreasonable to assume that they could work backwards from an APR to determine the dollar-for-dollar cost of capital. In effect, APR is a surefire way to mask the trust cost despite arguments to the contrary.
My unplanned debate with Ami Kassar on twitter is below:
Sorry Ami. The only thing unclear is your argument.
Beat The $3,000 Capital Loss Cap in Marketplace Lending
November 24, 2015 Because interest on platforms like Lending Club is counted as normal income and the losses as capital losses, you can only deduct a maximum loss amount of $3,000 if you don’t have capital gains from other investments. That can be an expensive mistake for an investor with a large portfolio who isn’t paying attention. For instance, if you earned $20,000 in income through Lending Club but had $10,000 in losses from defaults, you’d actually be taxed on $17,000, not on the difference between the two. In, Is the Premium Gone in Peer-to-Peer Lending?, I wrote that there’s a whole lot of risk in marketplace lending and not a whole lot of yield to compensate for it, especially when considering the poor tax treatment.
It’s surprisingly easy to rack up thousands of dollars in defaults in a single year even if you spread the risk around through small $25 increments. I know this because I’m teetering on the fence of it just on Lending Club alone. I had approximately $2,600 in charge-offs so far for 2015 at the end of October. Anything beyond $3,000 I can’t offset against my gains so there’s little sense in investing any more money.
Unless…
There is one way to build a significant portfolio without breaking the threshold, invest in the low risk loans. Of the 246 A-grade loans I’ve invested in, so far none of them have ever defaulted. Of the 675 B-grade loans, only 9 of them have already defaulted. Compare that to the 52 G-grade loans I’ve participated in where 11 have defaulted. It might interest you to know that the average time remaining to maturity on those G-grade loans is about 3 years. That means 21% of them have already gone bad and there’s still another 3 years left to go. While these stunningly high risk loans might return in yield for what they lack in performance, they’re a great way to build a capital loss mountain, something that could cause significant damage once you exceed $3,000.
By investing in low risk loans and staying below the capital loss cap, you can invest substantially more. Illogical as it may seem, a big lower yielding portfolio can earn more than a higher yielding one because of the tax treatment if you do not have outside investments with capital gains.
If you are a small investor looking to play with $5,000, none of this will likely be relevant to you, but if you were looking to place $100,000 or more, you might want to remember this phrase in marketplace lending, lower yield is more.
Read more about the capital loss rules and Lending Club on the LendAcademy blog.