Can an ISO “Excel” in 2016?
August 26, 2016
Don’t let anyone tell you that it’s too hard for a commercial finance broker to make a buck in exchange for honest work these days. One ISO in lower Manhattan is seeing more opportunity than ever before. Chad Otar, a managing partner of Excel Capital Management, sat down with deBanked to make his case for a bright future.
“As long as there’s small businesses, there’s always going to be opportunity,” Otar said. “Business owners are always going to need money.” Ironically, his own company that he cofounded in 2013 with hometown friend Nathan Abadi, was formed without any outside debt. Bootstrapped even to this day and even as they’re expanding, they’ve seen firsthand what other businesses around the country have to go through to get ahead.
“We’ve always believed in the products that we’ve sold,” said Otar, who brokers merchant cash advances, business loans, SBA loans, factoring products and more. They want every deal to help their clients whether it’s big or small, explaining further that even he himself has to feel comfortable with what the merchant wants. When asked about size, Otar said the largest SBA loan they got done was for $4.9 million.
But when questioned if more merchants were moving towards factoring and other traditional products, he explained that some merchants just don’t want to deal with the hassle of something that might be overly invasive or a process that might take a long time. They just want to get funded quickly, he said. And that’s where they come in.
Otar and Abadi’s optimism is not just anecdotal. The two partners, who previously renewed one year leases for their small office on Maiden Lane, saw enough runway to recently sign a five year lease for a 2,700 sq ft. office on Greenwich Street, staying within the bounds of the city’s financial district. Between full time employees and contractors, they currently house about fifteen people in their new office.
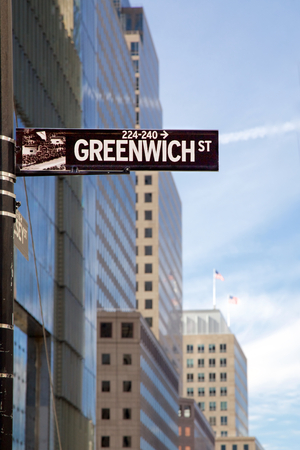 Though the partners live in Brooklyn, they, like many other companies in the industry, believe a Manhattan headquarters makes the most sense. “Everything is here,” Otar said. It’s easier to recruit new hires, he explained. And they indeed have immediate hiring plans now that they’ve got the space for it, both in sales and operationally.
This new up-and-coming generation of business owners is very comfortable with the Internet and technology, Otar added, speeding up the process and allowing they and the funding partners they work with to do more deals together. One example offered was a small business owner who gave a guided tour of his establishment to an underwriter using FaceTime on his phone. Normally, the process would’ve been delayed by a few days because of the time it takes to hire a third party to perform a site inspection.
Some funding partners offer DocuSign so that merchants don’t even have to spend time printing and signing documents anymore, he said, qualifying that however by adding that while some merchants love it, others hate it and feel more comfortable doing things the old fashioned way. He acknowledged that was likely due to the generational gap that still exists.
When asked if the setbacks and gloom that had begun to envelop the consumer lending side of fintech, was also affecting the commercial side, Otar said he didn’t see it. Funders are still very aggressive with approvals and terms, he said. While paperwork required for approval is declining overall, he described one obstacle that he hadn’t really dealt with in previous years, UCC filings that are accidentally left active even when the agreements are satisfied in full.
Underwriters doing due diligence might interpret active UCCs to mean that outstanding obligations still exist. Absent a formal termination of the UCC, an underwriter may request that merchants provide documents from the secured party to support that a termination should’ve been filed. This in itself is not a burdensome task but Otar said he has seen merchants who have used alternative financing products continuously over the last eight years or so, who are then challenged to produce satisfaction letters from dozens of companies, some of whom the merchant may only vaguely remember.
But he is not discouraged when new challenges come up. “We’ve been constantly learning,” he said. And when asked what their secret to success has been up until this point, “It’s hard work and dedication,” he responded.
Can Technology Be More Than Automation?
August 19, 2016
In yet another Lending Club exposé, Bloomberg revealed the identity of the man who allegedly first discovered suspicious Lending Club loans that would later be confirmed connected to disgraced CEO Renaud Laplanche in a post-resignation audit. Brian Sims, a retail investor in Lending Club loans used a specially designed algorithm to spot patterns such as multiple loans made to a single borrower at different interest rates. No easy task considering Lending Club takes great strides to protect borrower identity.
And this truly is the argument both for and against technology. Irrespective of what side of the debate you’re on, it’s hard to argue its indispensability in day to day business. It’s the one thing CEOs think long and hard about and rightly so — automation makes or breaks the size and scale of a business, vastly improves productivity and narrows if not eliminates the margin for human error (up for debate).
So, at deBanked we were curious to discover how small business financing companies use technology in their companies, what processes are automated and which side of the man vs machine debate they fall on.
Boston-based Forward Financing that makes merchant cash advances, working capital finance and small business loans up to $300,000 started investing in proprietary software right from the beginning, four years ago. It uses Salesforce for customer relations and basic reporting.
Its underwriting tool, channels leads and performs varying levels of automation to underwrite files quicker. The app pulls data from a number of different sources like credit bureaus, public record databases, social media and Google APIs before it goes to an underwriter. “Our goal over the next 3-4 months is to automate a percentage of all the deals that comes through the system,” said CEO Justin Bakes.
The company also has a banking application, a portal where customers log in with their bank details, with read-only access to their bank accounts to identify and analyze transactions which are then used to underwrite. Separately, it also has a portfolio management system that manages all the funding, transactions and all the collections.
While Bakes started investing in technology early on, it wasn’t until a year and a half ago that he tried automated underwriting. “Some hear the word automation and think they are going to lose their jobs,” said Patrick Hereford, Director of Technology at Forward Financing. “I can understand that automation can reduce jobs, but here, they found that they could underwrite more deals faster and with more accuracy.”
Hereford was hired in October last year from the TV show America’s Test Kitchen where he was working as a software engineer. Hereford makes a case for automated underwriting with proof — “We went from spending 20 minutes per file to six minutes per file,” he said. “We were expecting 50 percent efficiency in underwriting but we got more and increased productivity.”
 The company hired full-time engineering staff last year to move all their tech support and development in house. “A majority of our new hires and investments have been in technology. The tech team has grown the most over the last year,” said Bakes. He noted that the company has spent over a million dollars in building proprietary software alone and 20 percent of its selling, general and administrative (SG&A) is allocated to technology development.
“There is no doubt that we are a financing company but we are a tech-minded financing company. To be a true industry leader, you have to automate a certain amount. Our philosophy is we plan to keep improving our technology and the ability to approve faster than anyone else,” Bakes said.
Forward Financing is among other companies moving in that direction. California-based lender National Funding who has deployed $1.5 billion to small businesses over the last 17 years is also preparing for a technology overhaul, trying to get access to data pools to automate underwriting. “We need to be tech driven, as deals get smaller, we need to automate them to make it affordable,” National Funding CEO Dave Gilbert told deBanked earlier.
And five-year-old Pearl Capital is on a similar journey. The company grew its tech team from two to twelve people over a year and a half ago including data analysts and statisticians and is making significant investments in scoring technology, portfolio management and risk assessment. “We had a human model running successfully for years and they produce good results but move to machine is additive and supplemental,” said CEO Sol Lax. “Data and tech add a lot more texture and nuance to the market, it’s like the weather radar, you have visibility and can price accordingly.”
But technology doesn’t have to necessarily mean automating underwriting. In fact, there is a strong bastion of people actively resisting it. Isaac Stern, CEO of New York-based Yellowstone Capital is one of them. “I am going to get my underwriters as much information as possible – background check, credit check to make good decisions but that does not mean I am going to let a computer decide whether to fund or not.”
That doesn’t mean Stern doesn’t care about efficiency. In fact, Yellowstone has invested over a million dollars over the last year in ramping up technology. It hired AIG’s chief data scientist and has improved data mining with access to over 140 data points including SIC codes, credit scores and loan history. The company uses an application called Clear®, a Thomson Reuters product, through which it can conduct background checks as well as review business history and public records.
No matter what camp you belong to, there are strong arguments to be made for each side and it really comes down to the philosophy of the matter. But in a crowded lending market, does it make sense to grab every opportunity to scale better?
“Different people have different thoughts on whether this is frankenstein going off the rails or not and whether that will blow up or not,” said Lax. “But the barrier to entry is low as a funder, and the spend on tech can be small yet profitable.”
There are many alternative finance companies who believe that staying in the game requires some change in incumbent models to boost efficiency and speed that’s driven by auto approvals and declines. But there are also some like Stern who treat technology as an aid rather than an aim.
Perhaps time will tell which system is better.
Is The “Uber” Of Merchant Cash Advance Actually Uber?
August 15, 2016
If imitation is the sincerest form of flattery, Uber is paying the alternative small-business finance industry a high compliment. The San Francisco based ride-sharing company is offering its drivers some programs that closely resemble merchant cash advances.
New drivers receive part of the advance before they pick up their first fare and the rest soon after that initial ride. Clearbanc, which bills itself as a financial services provider for “the self-employed, freelancers, independent contractors and entrepreneurs,” is putting up the money. As with a merchant cash advance, drivers can choose to pay back the Advance Pay funds by directing a portion of their weekly earnings to Clearbanc, according to a blog by Rachel Holt, an Uber regional manager. In the test the companies are limiting the automatic deductions to no more than 50% of the driver’s weekly paycheck, she said. Participating drivers can still work whatever hours they choose.
If $1,000 isn’t enough to put an aspiring Uber driver on the road, the company has another plan. Through the XChange Leasing program Uber automatically deducts car lease payments from drivers’ weekly income, a company spokesperson said. A number of financial institutions work with the ride-sharing company in the program, according to the Uber website.
Applicants have to agree to what the company calls “a routine screening.” If they’re approved they receive a list of participating local car dealers. The leases are up to three years for new cars valued at as much as $20,000 and used cars worth up to $18,500. Cars can’t be more than seven years old or have more than 75,000 miles. They have to have four doors and five seat belts. Drivers put up a $250 security deposit when they receive the leased car. Typically, they might have 156 payments of $115 each for a 2013 Toyota Corolla or 156 payments of $143 each for a 2016 Corolla. California requires rideshare insurance, and Uber provides it through Farmers Insurance or Mercury Insurance.
 Unlike many standard automobile leases, XChange Leasing does not have mileage caps, and drivers can exit the program by giving two weeks notice and paying a $250 “disposition fee,” essentially forfeiting their security deposit, the Uber spokesperson said. For drivers who prefer to own their vehicles, Uber has negotiated fleet discounts with a long list of car manufacturers, the company said. The deals can reportedly bring drivers thousands of dollars in savings over the sticker price of a car. Meanwhile, Uber is testing another foray into financial services. Drivers can use “Instant Pay,” an Uber debit card from Green Dot’s GoBank division, to collect the cash immediately after finishing a ride, according to Holt. The cards don’t require a minimum bank balance and don’t carry any fees, she said.
The company seemed upbeat about its new offerings. “We look forward to seeing how these pilots progress and to making innovative payment solutions more widely available to drivers soon,” Holt said in her blog of Advance Pay and Instant Pay.
But some Uber drivers don’t share that optimistic view. In fact, Advance Pay and XChange Leasing have both come under fire for what critics view as disadvantages for drivers and for the economy as a whole. Some have gone so far as to label the lease terms practices as predatory.
Uber offers Advance Pay only to new drivers, and they could receive just about as much as a signup bonus, according to a blog on UberPeople.net, a website for drivers. The author of the blog speculated that the company is using Advance Pay to eliminate the signup bonus and also to do away with its bonus for referring new drivers.
Drivers have to pay off the advance in 15 weeks, according to the UberPeople blogger. At the rate of 30 cents per mile that drivers receive in Detroit, paying back the $1,000 would require logging 3,333 miles, approximately the distance from New York to California, the blogger lamented. However, Uber pays a lower rate in Detroit than in most cities, according to statements from other drivers.
And although Advance Pay carries no interest, Clearbanc charges drivers a fee of up to $50 if they fail to pay off the advance in 15 weeks, according to published reports.
Complaints also arise with XChange Leasing, according to a website called therideshareguy.com. Dealers sometimes refuse to provide used cars for the program because they can make more money with new cars, according to the site.
If the dealers are willing to provide used cars, problems sometimes surface because XChange Leasing prohibits leasing a used vehicle for more than 105% of its book value, the site said. Cars with a reputation for reliability, such as Toyotas and Hondas, often sell for more than book value, according to the site.
 Drivers have reported elsewhere that they feel trapped by the leases, many of them continuing to work for Uber just to make the payments. However, the Uber spokesperson maintained that drivers can leave the program anytime after the first 30 days. Some critics bemoan the spread of subprime auto leases, which they have compared to the subprime mortgage debacle that contributed to the Great Recession that struck in 2008. Uber prefers comparisons to Amazon, a company that has expanded by continuing to enter new businesses.
In general, Uber has met resistance repeatedly from traditional taxi drivers who find their livelihood threatened by the ride-sharing service. Taxi drivers around the world have chided Uber for failing to pay taxes, obtain taxi licenses and uphold safety standards.
Complaints aside, Uber continues to grow prodigiously and now serves riders in more than 400 cities in 70 countries, according to metrics supplied by the Uber spokesperson. Seventy-five percent of Americans live in counties where Uber operates, the spokesperson added. Globally, Uber employs 7,000 workers and 1 million drivers, the company said.
The word “uber” is defined as “denoting an outstanding or supreme example of a particular kind of person or thing, according to a dictionary entry the company sometimes cites. In German, “uber” means “across” or “above.” Many potential riders know the word “uber” from the phrase “Deutschland, Deutschland uber alles,” a line from the German national anthem that translates as “Germany, Germany above all else.” The words to the song were written during Germany’s unification, and the lyrics refer to the idea that allegiance to the nation should trump loyalty to local kingdoms. Maybe Uber should stick with its own definition of “uber.”
California Finance Lenders Law Licensing Compliance for Merchant Cash Advance Financiers
August 2, 2016 Since the Richard B. Clark v. AdvanceMe Inc. class action case settlement was brought to the awareness of the Merchant Cash Advance (“MCA”) industry, many MCAs applied and obtained a California Finance Lenders Law License from the Department of Business Oversight. (“DBO”)
After your company obtains a California Finance Lenders Law license, it will then need to comply with the California Finance Lenders Law. (“CFLL”)
CFLL does not contain specific financial code sections and regulations to regulate MCAs. However, CFLL regulates consumer and commercial loans. So, MCAs licensed under the CFLL will need to comply with the code sections and regulations that apply to commercial loans, assuming that MCAs provide advances that are each “bona fide” $5,000 or more in principal amount and for commercial purposes.
The MCA contract you use when making advances in other states is likely not in compliance with CFLL. CFLL regulation includes without limitation, (either directly or by incorporation of other California and federal laws) the rates and charges, marketing and advertising, disclosures, contractual provisions, electronic transactions, collections, credit applications, default and repossession, brokers and finders, and general operations of main and branch offices.
The CFLL license application requires the MCA company’s principal (corporate officer or LLC manager) to acknowledge on behalf of the MCA company, that it read the contents of and is familiar with the CFLL, and that it agrees to comply with the CFLL.
Lack of compliance can be brought to the attention of DBO’s enforcement officials as a result of either, a customer or competitor complaint, a DBO audit, through the Annual Report that must be filed by CFLL licensees by March 15 of each year, or by other means.
It is important to not only obtain the CFLL license, but to also comply with the CFLL to keep the license. DBO publishes online enforcement actions, such as Desist and Refrain Orders and Accusations. A CFLL licensee has a right to request an administrative hearing to defend itself and present its case. Unfortunately, although the legality of this practice by DBO is questionable, DBO publishes online none-final (and also final) administrative enforcement actions such as Desist and Refrain Orders (“D&Rs”) and Accusations. (publishing of final administrative orders is specifically authorized by the Financial Code but not none-final orders) Potential customers and competitors who review none-final D&Rs, are under the mistaken belief that the D&R is a final order, and may therefore refuse to conduct business with the licensee.
MCAs who are either CFLL licensees or potential licensees should familiarize themselves with CFLL law to avoid administrative enforcement actions, court actions, loss of business, and other adverse repercussions.
Google Adwords Interruption May Be Coming for Business Lending and MCA This Week
July 12, 2016 Get ready for Google to probably misinterpret what you do come July 13th, the day that Google has decided to ban all consumer lenders that charge more than 36% APR or have terms less than 60 days, from paid search advertising. This is according to an announcement Google made back in May, as part of a campaign they’ve suddenly decided to undertake to stop profiting from payday lending.
Nevermind that Google is openly in the payday lending business themselves through their investment in LendUp, a short term lender they made a second massive investment in just a few months before they moved to ban everyone else. And nevermind of course that the CFPB has just extended their enforcement activity to middlemen, most notably by going after T3Leads and its owners for directing borrowers to questionable prospective lenders that pay top dollar, arguably in a similar banner to what Google does with its searchers and its paid payday search results.
Nevermind all that.
Here’s what you might mind. A Google Adwords specialist might have no idea what kind of financial activity you engage in and it could end up costing you. Eight months ago for example, the organic search results lumped merchant cash advance into cash advance, triggering a special box for merchant cash advance seekers that inadvertently (or maybe intentionally) referenced payday loans.
If your Google ads do get suspended this week, the semantics surrounding the term cash advance could create a challenge.
Google wrote that commercial loans are exempt from the ban and that should presumably mean all commercial finance products such as factoring and merchant cash advance. But if they screw up, and in all likelihood they probably will with some companies, be as clear as you can in explaining the commercial nature of your product and how it works.
Because if they don’t get it, you could be banned for life.
Fundry Secures $75 Million Credit Line, Confirming That This Niche Is Still Hot
July 5, 2016
Fundry has secured a new $75 million credit line, according to the company’s CEO Isaac Stern. The transaction was facilitated by Brean Capital and Pi Capital.
Fundry is commonly known by one of their subsidiary companies, Yellowstone Capital. According to a document obtained by deBanked, the company did more than $40 million in deals last month, with the vast majority funded in-house. The positive announcement follows their recent big move from NYC’s financial district to Jersey City, NJ, after being wooed to the state with tax incentives in return for creating jobs.
While confidence has retreated from online consumer lending after the scandals at Lending Club, specialty tech-enabled commercial finance companies, some of whom specialize in merchant cash advance, are still finding enthusiasm from institutional investors. Just over the last three weeks, Bizfi secured a $20 million investment from Metropolitan Equity Partners, Pearl Capital secured $20 million from Arena Investors, and Legend Funding secured a $3 million debt facility from Ango Worldwide. That’s $118 million invested into a very specific niche industry in less than a month.
Fundry alone, facilitated $422 million in funding to small businesses just last year.
Split-Funding MCA and Daily Debit Loans Are Spreading Across the World
July 4, 2016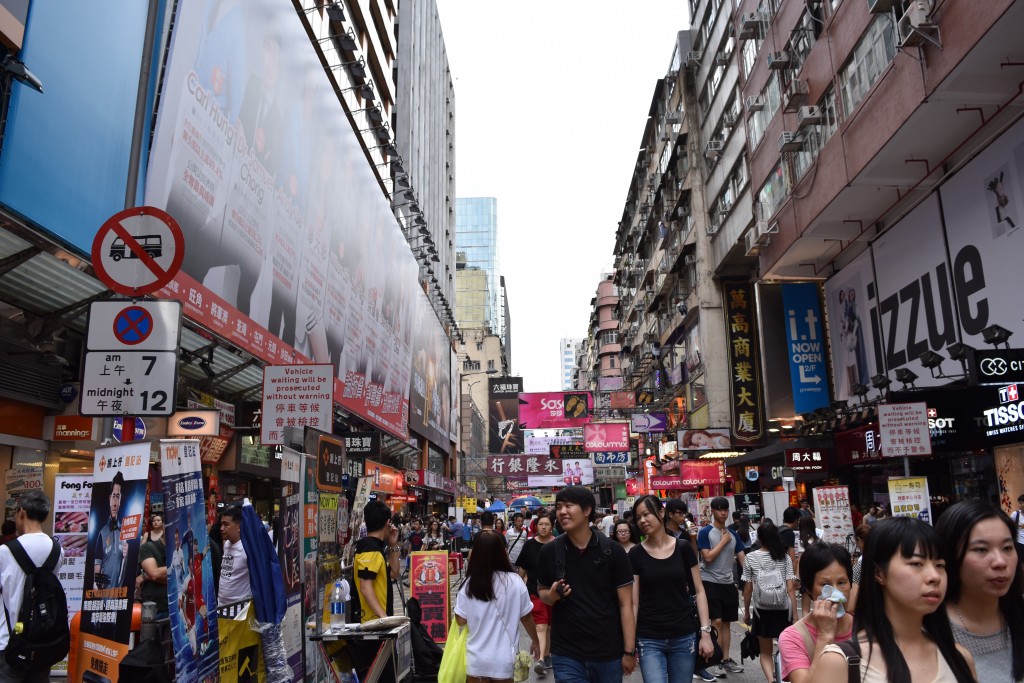
When banks say no, merchants all over the world are getting funded via non-bank alternatives that resemble products here in the USA. In Hong Kong for example, a special administrative region of China, there are non-bank businesses that offer merchant cash advances and/or daily debit loans.
Having had the opportunity to visit with some of those funders there last week, I was surprised to learn that we spoke the same language. By that I mean that they price deals with factor rates, work with local finance brokers, underwrite files using recent bank statements, do site inspections and more. They even a have decision issued by the highest court in the land that declared merchant cash advances to be purchases, not loans.
Even the pitch is basically the same. “Banks aren’t lending to small businesses,” I heard time and time again in Hong Kong. And that’s probably not going to change any time soon. While the non-bank business financing scene is starting to take off, merchant cash advances in particular have been around there for about seven years already.
Hong Kong’s population is a little less than a third of the size of Australia, where many US-based funders have been expanding to over the last couple years.
Alternative Funders Continue to Look Down Under
June 29, 2016 Add CapRock Services to the growing list of US-based small business funders that have joined the scene in Australia.
CapRock has formed Sprout Funding as part of a joint venture with Sydney-based family office Huntwick Holdings. Together, they will provide small businesses with loans or revenue-based MCA products up to $100,000.
What’s truly unique is that CapRock will actually be underwriting the deals from their Dallas-based office. And they hope to fund $20 million in two key Australian markets in their first year. Luke Schmille, CapRock’s CEO, told the Dallas Business Journal that he believes the Australian market is very similar to the US. “70 percent of the population is employed by small to medium sized businesses,” he said.
Other funders in Australia that have US-backing include Capify, Prospa via Strategic Funding Source, Kikka Capital via Kabbage, and OnDeck.
Last Fall, John de Bree, the managing director of Capify’s Sydney-based office, told deBanked that he was surprised of the American interest in Australia. “The American market’s 15 times the size of ours,” he said.
One of his competitors, Lachlan Heussler, managing director of Spotcap Australia, was not so shocked. “This is a market that will evolve over time, and we think the opportunity is enormous,” he said.
In an email, CapRock’s Schmille, wrote that they were excited about the expansion abroad.