Related Headlines
| 03/20/2024 | Can brokers split fees in CA? |
| 04/19/2021 | GOUNDFLOOR teams up with PadSplit |
| 02/05/2020 | Avant splits in two |
| 08/09/2018 | Industry split on CA disclosure bill |
| 09/21/2017 | Simply Funding announces new split provider |
Related Videos
What is Split Funding? What's A Split Deal? | Split Funding & Split Deals - Ep. 66 |
Why Split Funding is Better Than ACH | |
Stories
Revisiting Splits and Payment Methods in the Funding World
March 31, 2024 As most people are aware, ACH debits are only one method used in the small business finance industry to facilitate performance of a deal. Here are some other common ways:
Split Funding
This method has been in use since at least 1998 and is still used by many funding companies today.
See: CC Splits Still Make Profits, Payments Knowledgeable Funders Benefit
Lockbox
A lockbox gives you the protection and visibility of a split but may require additional setup steps. This method was very common in the 2008 – 2012 era and is still available.
Variable ACH
The variable ACH system, made famous by MCC starting circa 2009, is still in use around the industry.
See: Homegrown Software Enables FundKite to Reconcile MCAs Daily Rather Than Monthly
Não é bom: When Split-Payment Business Loans Fail
February 20, 2022 As tech companies like Square and Shopify capitalize on their respective abilities to collect loan payments from borrowers by withholding a percentage of their credit card sales, similar companies have replicated that model across the world. StoneCo, for example, which is traded on the Nasdaq but operates in Brazil, had a market cap last year of over $25 billion. More recently, however, it’s dropped to nearly $3 billion.
In Brazil, StoneCo used its wide reaching payment business to start originating small business loans that were paid back through their customers’ credit card sales. That business seemed to hold up quite well early on in the pandemic but then took a turn for the worse. According to Bloomberg, distressed businesses came up with ways to circumvent their payments. “…[B]usinesses started jumping to other payments firms, meaning Stone no longer had access to their card purchases,” it said.
“Lockdowns pressured businesses’ cash flows and several sought ways to not pay back their loans,” StoneCo CEO Thiago Piau said.
Historically, diverting sales through another payment processor to avoid this type of obligation was known as “splitting.” It’s an inherent risk to finance companies that make underwriting decisions based on the assumption that the customer is unable to exit the relationship without seriously disrupting its business.
StoneCo was hit so bad that it stopped lending altogether and a significant percentage of its customers went into default. In the company’s Q3 2021 earnings call, Chief Strategy Officer Lia Matos said that they intend to get back into lending again but with some adjustments.
“So, those improvements are, for example, the inclusion of personal guarantees from the business owners and potentially other business they may have, improve risk scoring through additional data,” said Matos.
Covid may have been less damaging to similar companies in the US like Square, for example, because Square was able to repurpose itself to a PPP lender. The incentive to move to another payments platform may have been diminished by the allure of leveraging a pre-existing relationship to secure PPP funds.
StoneCo in Brazil is an example of what can happen to a fintech lender reliant on recouping credit card sales when that relationship doesn’t stick.
To help ensure the team gets things right in the future, StoneCo recently acquired Gyra+. Described as “a data-driven SME lender, which operates under a fee-based, asset-light approach,” the company plans to gently ease back into lending.
“I think that we are not ready to provide a specific guidance in terms of scaling the credit,” said CEO Thiago Piau in November. “We are really focused toward engineering and getting the feedback of clients and all the clients’ experience that we have learned throughout this.”
Brazil has a population of 212 million people.
CC Splits Still Make Profits, Payments Knowledgeable Funders Benefit
June 15, 2021 Back in its heyday, the MCA industry began as credit card factoring. The original product was simple- purchase future credit card receivables, and collect a percentage of them every day: easy peasy. Then, the industry broadened into ACH, funding businesses that did not have credit card purchases and credit card receivables became less common.
But some funders still work with credit card payments through long-standing payment processor relationships. Cash Buoy is a Chicago-based MCA firm that uses a network of twelve major credit card processors and thousands of representatives from payments ISOs to fund old-fashioned MCAs. Co-Founder and president Sean Feighan would tell you that having connections in payments pays off for both merchants and ISOs.
“The whole point is to add value to their business. By doing split funding remittance,” Feighan said. “It’s a much more comfortable way for the merchant to pay back the advance, it gives them some breathing room on the ebbs and flows of their volume, as opposed to having that hard fixed daily ACH that doesn’t care if they were closed on Monday, are slow on Tuesday, or we’re in a global pandemic.”
Feighan attests that the CC model still works great. He said alongside co-founder Brian Batt, they started Cash Buoy to give ISOs a better option. He boasts a renewal rate of 90% on his CC products, and his default rates for standard MCAs are a “night and day difference” with CC splits.
But operating heavily within the payments realm requires some expertise, something that long-time veterans of the MCA space are fortunate to have accumulated from the era of the product’s origin.
Steven Hunter, a multi-decade industry vet explained where the MCA concept came from. Hunter worked at CAN Capital back in 2000 when it was still was called AdvanceMe when he and the data team developed one of the first credit card factoring products.
“The idea came across to build a credit card-based product, because a lot of the original development team other than myself, were the First Data guys,” Hunter said. “And they said ‘okay well what if we could factor future sales, instead of three invoices or accounts receivable or inventory’, which we all know how to factor those things, that’s been in place since biblical times.”
So they built a model, aiming to fund merchants and take out a small amount of money from their credit card splits. Merchants would never see the money hit their bank, and the product just felt like free investing money paid for off of the increase in future sales.
When restaurants and other merchants shut down during the pandemic or rolled back to 25% capacity, many ACH funders found out their customers could not keep up with the pre-set debits. While defaults were on the rise, Cash Buoy was getting paid back, Feighan said, at an admittedly slower rate but still seeing returns.
Feighan has intentionally shied away from ACH. Cash Buoy is modeled on his and Batts’ connections in the payments space. They founded Cash Buoy after five or six years of experience in on-boarding merchant accounts. Feighan said he tried brokering but became disappointed with the process of working with an outside funder.
“[Other firms] may not have the relationships to get split funding at national processors,” Feighan said. “Maybe they didn’t have enough business or money in the bank when they went through the application process with different processors to get true split funding accommodations.”
Hunter agreed that without payment connections it is hard to factor CCs these days. Shortly after AdvanceMe began CC splits, other firms caught up and began developing similar products, with slightly changed terms like automatic set ACH draws. Eventually, he said this made MCAs more loan-like as opposed to a real variable product.
In 2021, there are many reasons that firms adopt ACH right off the bat, he said.
“Well, several reasons one, not every company takes credit cards,” Hunter said. “The thing is that some credit card processors, I’m not going to name any names, are very hostile to the product and they will not actually help people. They won’t help you manage the remittance, they won’t split for you, because they consider you to be a competitor, afraid you will take a portion away.”
 The final reason Hunter said is a lot less elegant. He said in order to make this work, as a direct funder, you have to exchange files with every credit card processor you work with every night on every deal you have.
“So you got to send them something out and say, populate this for us. ‘Joe’s Bait Shop, What did they do today? Today they did this much money, your split is 11%, here’s what’s coming to you,'” Hunter said. “Then you import that back into your system and Joe’s Bait Shop’s balance drops by this amount. Right, that’s hard. I mean it’s a pain in the ass to manage, and I have people who do nothing but exchange, you’ve got to have processors who work with you and you’ve got to have the expertise.”
Hunter now works as a consultant, known in the industry as a go-to for MCA funding help. As for Cash Buoy, after the pandemic year, things are only on the up and up. Covid could not have happened at a worse time right after a three-year bull run, Feighan said, but now that things are back, there are “high water funding amounts each month.”
“The biggest thing here in Cash Buoy are our partners, our ISO partners, and processors,” Feighan said. “And if anybody were to say, ‘tell me, what’s the most important thing to you, Cash Buoy,’ it is 100% Our agent partner program. That is number one. The whole point of the company was to be able to provide a ton of value to national processors and ISOs.”
Split-Funding MCA and Daily Debit Loans Are Spreading Across the World
July 4, 2016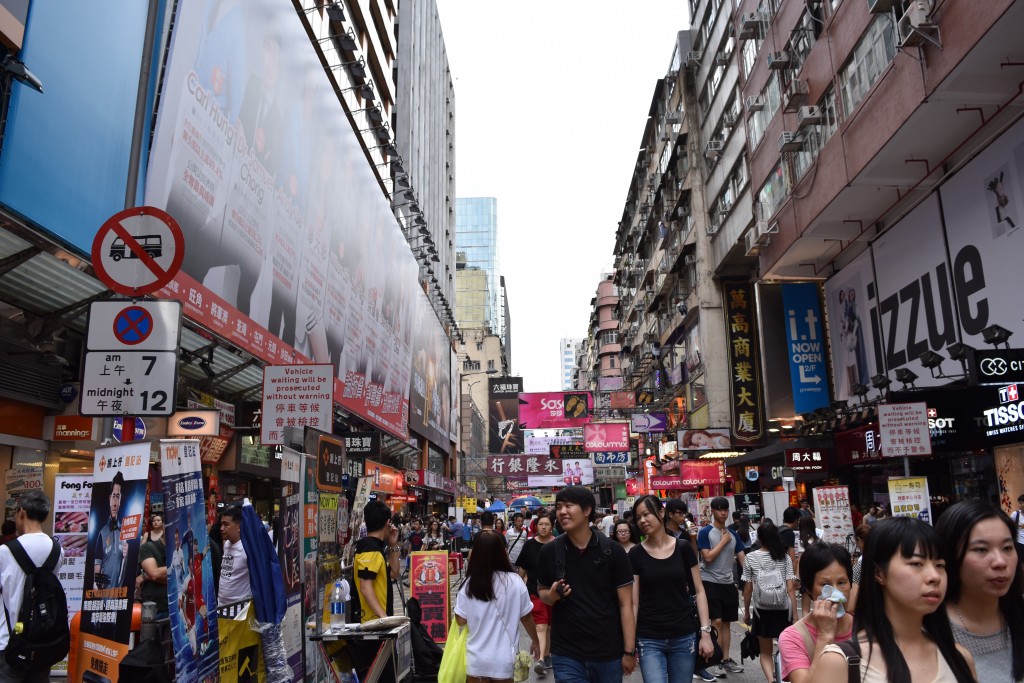
When banks say no, merchants all over the world are getting funded via non-bank alternatives that resemble products here in the USA. In Hong Kong for example, a special administrative region of China, there are non-bank businesses that offer merchant cash advances and/or daily debit loans.
Having had the opportunity to visit with some of those funders there last week, I was surprised to learn that we spoke the same language. By that I mean that they price deals with factor rates, work with local finance brokers, underwrite files using recent bank statements, do site inspections and more. They even a have decision issued by the highest court in the land that declared merchant cash advances to be purchases, not loans.
Even the pitch is basically the same. “Banks aren’t lending to small businesses,” I heard time and time again in Hong Kong. And that’s probably not going to change any time soon. While the non-bank business financing scene is starting to take off, merchant cash advances in particular have been around there for about seven years already.
Hong Kong’s population is a little less than a third of the size of Australia, where many US-based funders have been expanding to over the last couple years.
Splits Glitz or Fritz? – Transact 16 highlighted strange chapter in merchant cash advance history
April 21, 2016
It’s Opposite Day in the alternative business funding industry. Lenders are splitting card payments and merchant cash advance companies are doing ACH debits.
Jacqueline Reses was not an odd choice for Transact 16’s Wednesday morning keynote. Square, the company she works for, has continued to be a hot topic in the payments world for years. But what was striking is that Reses heads the lending division, the group that allows merchants to pay back loans through their future card sales. If that sounds very merchant-cash-advance-like, it’s because that’s exactly the product they used to offer before changing the legal structure behind them.
Split-payments, not ACH payments, have literally propelled Square and PayPal to the top of the charts of the alternative business funding industry. One individual on the exhibit hall floor posited that Square’s ability to originate loans through their payments ecosystem was the company’s real value; Payments itself was secondary. It’s a testament to the opportunities that split-payments affords to (as I argued 3 years ago on the ETA’s blog) a company well positioned to benefit from it.
Meanwhile, the companies at Transact that one would have historically described as merchant cash advance companies have mostly transitioned away from split-payments to ACH. Essentially, Square and PayPal embraced splits as an incredible strength while yesterday’s merchant cash advance companies viewed splits as a handcuff that limited scalability. The payment companies became merchant cash advance companies and the merchant cash advance companies became something else entirely, a diverse breed of loan and future receivable originators operating under a label people are now calling “marketplace lenders.” But even Square and PayPal, arguably the two companies at Transact doing the most split-payment transactions, claim to make loans, not advances.
Merchant Cash Advance as anyone knew it previously is dead
Ten years. That’s the average age of the small business funding companies that exhibited at Transact this week. They are but the last remaining players that probably considered the debit card interchange cap imposed by the Durbin Amendment of Dodd-Frank as being among the most significant legislation that affected their businesses.
A senior representative for one credit card processor told me at the conference that their biggest gripe with new merchant cash advance ISOs today is that they know almost absolutely nothing about merchant accounts. It’s not that they know less, they know nothing, he said.
One company was notably absent from the floor this year, OnDeck. They’ve since embraced the marketplace lending community as their home, just as many others have.
Nine years ago, I overheard a very influential person say that the first company to be able to split payments across the Global, First Data and Paymentech platforms would be crowned the “winner” of the merchant cash advance industry and by extension the wider nonbank small business financing space.
If one were to define the winner as the first company from that era to go public, well then those 3 platforms played no role. OnDeck was the first and they relied on ACH payments the entire way. They also refer to themselves these days as a nonbank commercial lender. If that doesn’t sound very payments-like, it’s because it’s not.
What cause is being Advanced?
At least four coalitions are currently advocating on the marketplace lending industry’s behalf, the Coalition for Responsible Business Finance, the Marketplace Lending Association, the Small Business Finance Association, and the Commercial Finance Coalition. The Transact conference is put on by the Electronic Transactions Association whose tagline is “Advancing Payments Technology.” In an age where new merchant cash advance ISOs know nothing about payments, it’s no wonder there’s a growing disconnect.
Could Transact now be one of the best kept secrets?
A few people from companies exhibiting say that they believed they stood a better chance to land referral relationships from payment companies by being there and that there was still a lot of value in landing those deals. Partnerships like these may be why the average exhibitor has been in business for 10 years while today’s new companies relying solely on pay-per-click, cold calling, or handshakes are falling on hard times.
Some payment processors acknowledged that merchant cash advance companies were still a good source to acquire merchant accounts, though the process by which that happens is not the same as it used to be. A lot of it is referral based now, according to one senior respresentative for a card processor. The funding company funds a deal via ACH and then refers them to the payment guy to try and convert that as an add-on. The residual earnings may not be as good as they used to be but that’s because they don’t have to do any work in this circumstance. In a sense, funders are still leading with cash but instead of the boarding process being mandatory, it’s an entirely separate sale that sometimes works and sometimes doesn’t. In that way, small business funding companies can be a good lead source for payments companies.
When I asked the senior representative if they really had success closing merchant accounts just off of a referral from a funding company, he looked at me incredulously, and said, “you used to do this, of course we do. that’s how this whole industry started.”
“What industry?” I asked.
What industry indeed…
Split Funding is Here to Stay
August 21, 2013 I’ll say it for the hundredth¹ time, the advantage of split-funding is the ability to collect payments back from a small business that has traditionally had average, weak, or poor cash flow. Let’s put that into perspective. There is a distinct difference between a working business with poor cash flow and a failing business. A failing business is typically not a candidate for merchant cash advance or similar loan alternatives.
Poor cash flow could be the result of paying cash up front for inventory that will take a while to turn over. A hardware store with a healthy 50% profit margin may be able to turn $10,000 worth of inventory into $15,000 in revenue over the course of the next 90 days. The only problem is that the full $10,000 must be paid in full to the supplier on delivery.
Enter the merchant cash advance provider of old that discovers the hardware store has had a fair share of bounced checks in the past, mainly because of the timing of payments going in and out. Cash on hand is tight, the credit score is average, but the profit margin is there. Most lenders would take a pass on financing a transaction that carries legitimate risk such as this one does, that is until the ability to split-fund a payment stream became possible.
Advocates of the ACH method tout that it’s just so much easier to set up a daily debit and scratch their heads and wonder, “man, why didn’t we think of just doing ACH in the first place?”
The thing is, people did think of it and they concluded that for a large share of the merchants out there that needed capital, it didn’t make financial sense to try and debit out payments every day with the hope that there would always be cash available to cover them. Banks have had a hard enough time collecting just one payment a month, so what makes 22 payments in a month so much more likely to work?
I’m not inferring that there is something wrong with the daily ACH system that has taken the alternative business lending industry by storm. There’s plenty of situations for which that may be the best solution, especially for businesses that take little or no credit card payments. My point is that the split-funding method isn’t going to shrivel up and die. It’s here to stay. So long as businesses have electronic payment streams, they will be able to leverage them to obtain working capital.
When it comes to splitting card payments however, it’s important for a business to have faith in the payment processor. Reputation, compatibility with payment technology, and the assurance that the business will be able to conduct sales just as it always has are important. If you’re a funder, ISO, or account rep, it’s your responsibility to make sure that those three factors are addressed. A lot of processors are willing to split payments but they haven’t all made a name for themselves in the industry. Integrity Payment Systems (IPS) comes to mind as one that almost everyone works with and I’ve been in touch with Matt Pohl, the Director of Merchant Acquisition of IPS for some time. He’s been nice enough to share a little bit about what makes a split partner special, and what has made them particularly stand out in the merchant cash advance industry.
Clearly, the role of the credit card processor has diminished over the last couple years when it comes to merchant funding. ACH/Lockbox models have become more prevalent which created a sales mindset that switching a merchant account was more of a hindrance than a necessity. Some argue the decline in profit margin on residuals, due to price compression, made it no longer worth the time and effort to make an aggressive pitch to switch the merchants processing. ISOs also argue that too often merchants have reservations to switch processors because of previous bad experiences, cancellation fees, or because they simply know its not necessary in order to be funded. This is where it’s important to have the RIGHT split partner, not just any split partner
What makes Integrity Payment Systems a “special” split partner is the fact we control the settlement of the merchants funds, in house. IPS is partnered with First Savings Bank (FSB), which allows us a unique way of moving money. Because of our state-of-the-art settlement system and direct access to FSB’s Federal Reserve window, we eliminate the necessity of having layers of financial institutions behind the scenes that merchants funds typically filter through. This is a HUGE benefit to cash advance companies for several reasons. First, we implement the fixed split % when we receive the request, in real time. This allows the deal to be funded quicker. Secondly, since we handle the settlement process we have access to the raw authorization data which allows us to provide comprehensive reporting on a daily basis from the previous days activity. But also we can do true next day deposits, including Friday, Saturday, and Sunday funds available for the merchant on Monday morning. This is especially valuable when selling to restaurants/bars, or any other industry with a lot of weekend volume. Lastly, IPS makes outbound calls to merchants, on behalf of the sales agent and cash company, to download and train the merchant on their terminal. A confirmation email is sent to the agent which includes any batch activity so the deal can fund.
As an added example of this, on the last week of every month, the merchant boarding and sales support team fully understands that our MCA partners have monthly funding goals they need to reach. The IPS team goes above and beyond to ensure merchants get setup properly in time so those accounts can be funded before the month is over. We have a motto at IPS that the sales force are our #1 customers, and nowhere is that more apparent than by the way we take over all the heavy lifting once the agent gets the signatures on our contract. We firmly believe that by helping the agent by taking over the boarding process, that this will allow them to do what they do best, sell more deals!! A lot of competitors expect the agent to be involved in the boarding process, and that’s valuable time that takes them away from selling.
IPS has opened their doors to every MCA company that wishes to have an exceptional split funding partner/processor. We have all the necessary tools to provide this service the right way, and we want the opportunity to earn the business of every working capital provider out there. You don’t have to listen to a sales pitch from me, because I strongly believe that our reputation in the cash advance space speaks for itself. We would love the opportunity to talk to any MCA provider about a few additional services we offer utilizing our settlement system that will allow ISOs to fund more deals.
– Matt Pohl
(847) 720-1129
Integrity Payment Systems
One thing I can personally attest to about Integrity is their human factor. You can actually meet some of their team and see inside their office in the fun youtube video below:
Getting deals done
Ultimately, the financing business is about getting deals done and there are countless small businesses that just won’t ever be a candidate for ACH repayment. Heck, for many years the merchant cash advance industry wasn’t even a financing industry of its own, but rather it was one of many acquisition tools for merchant account reps. (See: Before it Was Mainstream). Technically it still is. You don’t want to sign up a merchant for processing and then have to move the account because the processor doesn’t split or because there is no dedicated customer service. I’ve been in that situation before personally and it’s a nightmare.
There’s a reason this website which is dedicated mainly to merchant cash advance is called the Merchant Processing Resource. You can’t know everything about cash advance without knowing about merchant processing. Get acquainted!
If you’d like to read the lighter side of Merchant Cash Advance History, you just might want to check out MCA History in Honor of Thanksgiving. 😉
¹ I said it for the 99th time on the Electronic Transactions Association’s Blog in Preserving the Marriage Between Merchant Cash Advance and Payment Processing
Audit Season Is Coming: How to Get Your MCA Books Ready Before the Panic Starts
April 20, 2026David Roitblat is the founder and CEO of Better Accounting Solutions, an accounting firm based in New York City and a leading authority in specialized accounting for merchant cash advance companies. To connect with David or schedule a call about working with Better Accounting Solutions, email david@betteraccountingsolutions.com.
 Audits do not create problems. They reveal them. This distinction matters more than most funders realize, because the panic that accompanies audit season rarely stems from the auditor’s requests. It stems from the gap between the order a company believes it has and the order it actually keeps.
A funder in Chicago learned this one March when his auditor sent a routine request: ten funded deals, their supporting documents, and the corresponding bank activity. He expected the ask. What he did not expect was how long it took his team to assemble everything. Three merchant applications were missing pages. One deal had two payoff letters saved under different names. A renewal had been recorded without a clear link to the original advance. Nothing was catastrophic, but everything took longer than it should have. He looked around the conference table and saw the same realization on everyone’s face. The audit had not made the mess. It had simply exposed it.
This is how most MCA shops encounter audit season. The good news is that readiness does not require special software or a large finance team. It requires discipline in daily habits long before the auditor appears.
Reconciliation of RTR balances is a natural starting point. Many funders assume their balances are accurate because the CRM shows a clean number. In practice, reconciliation depends on tight alignment between the CRM, processor reports, and the accounting ledger. If any of these sources lag by even a few days, mismatches will begin to form. A merchant’s payment might fail on Friday, get resubmitted Monday, and post to the ledger Tuesday. Without consistent reconciliation, the funder sees one story while the auditor sees another. A steady daily or weekly routine of matching processor deposits to merchant balances prevents these gaps from widening into explanations nobody wants to give.
Wire activity demands the same attention. Funding wires, collections wires, reserve transfers, syndicator payouts: each touches different parts of the books. A company that does not document these movements as they occur eventually faces a stack of transactions labeled simply “funding” or “payout,” requiring backward reconstruction that consumes hours. One funder discovered that three wires recorded as syndicator payouts were actually renewals paid in error from the wrong account. Small mistakes, but they created lengthy explanations. A simple internal rule that every wire must carry an attached note and supporting detail at the moment it is sent eliminates that uncertainty before it takes root.
Syndicator splits introduce their own complications. When multiple investors participate in a deal, the funder becomes responsible for tracking each share of principal and returns with precision. Problems arise when the initial split is entered inconsistently, or when renewals process without correctly updating the syndicator’s residual balance. During audits, these discrepancies stand out immediately. One company maintained a separate spreadsheet for syndicator participation because their CRM could not display multi-party splits cleanly. The spreadsheet worked until the team member who managed it went on leave. No one else understood the logic. The audit revealed not a major error, but a process built around one person instead of a system. Auditors look for evidence that the company can reproduce its numbers without depending on any single employee.
Default classification is another area where funders frequently fall behind. A delayed payment can linger in active status for weeks because no one wants to mark it as default prematurely. But when the auditor reviews the file, unclear classification becomes a problem. The funder must show when the merchant became delinquent, what outreach occurred, and how the remaining balance is being treated. A restaurant in Texas once stopped paying for three weeks. The collections notes lived in the account manager’s personal notebook instead of the CRM. The auditor flagged the discrepancy because the books still showed the merchant as active. Proper classification helps the funder understand portfolio behavior and demonstrates to the auditor a clear, consistent process.
Underlying all of this is documentation quality. Merchant applications should align with the funded terms. Bank statements should be complete. Contracts should be saved with names that make sense across the team, not names that make sense only to the person who downloaded them. Renewals should show the payoff, the redeployment of capital, and the new terms in one complete package. Missing pages, duplicated files, and vague naming conventions do not cause financial harm directly, but they slow the audit and weaken the impression of professionalism. A well-organized document library is one of the simplest ways to make an audit move smoothly.
Internal controls play a larger role than many funders expect. An auditor does not expect a small MCA company to maintain the same segregation of duties as a large financial institution, but they do expect clear responsibilities. If the same person initiates payments, reconciles bank accounts, and approves adjustments, the company has created unnecessary risk. Even a small team can separate duties by establishing checkpoints. One person prepares the payout. Another reviews it. A third reconciles the bank activity. These controls do not exist to catch wrongdoing. They exist to make wrongdoing difficult in the first place.
The habits that lead to a smooth audit cannot be assembled the month before it begins. They must be woven into ordinary operations throughout the year. A weekly ten-minute review of aging reports reveals shifts early. A monthly check of syndicator exposure confirms whether splits were entered correctly. A simple rule that every merchant contact must be logged before the end of the day prevents confusion when questions arise later. At Better Accounting Solutions, we encourage clients to think of these routines not as audit preparation but as as the proper way to run a business. The audit simply confirms what healthy habits have already produced.
Audit readiness benefits the team in ways that extend beyond the audit itself. When systems are disorganized, staff spend more time defending their work than improving it. When information scatters across folders and inboxes, no one feels fully in control. A clean, disciplined financial environment reduces stress for everyone. New employees learn what good work looks like because the system teaches them. Managers spend less time searching for answers and more time interpreting what the answers mean.
Audits also shape how capital partners view the company. Syndicators and institutional investors frequently request audit reports before deepening their commitments. A clean audit signals stability and transparency. A messy one does not automatically disqualify a funder, but it raises questions that take time and credibility to resolve. A funder who treats the audit as part of their annual rhythm presents a stronger case to partners than one who treats it as an interruption to be survived.
Many funders approach audits with dread. The dread usually fades once the process begins, because audits do not invent problems. They surface them. And once surfaced, problems can be fixed. Funders who treat findings as guidance rather than criticism tend to grow faster. They catch issues earlier. They build stronger infrastructure. They develop habits that improve performance year-round rather than only during preparation season.
In an industry where capital moves quickly and margins shift without warning, reliability becomes a competitive strength. A company with clean books makes better decisions. It moves faster because it spends less time reconciling its own history. It communicates more clearly with partners because its numbers are organized and honest. Audit readiness has less to do with pleasing an auditor and more to do with strengthening the structure that supports every advance.
The calmest funders during audit season are not the ones with perfect portfolios. They are the ones who built habits long before the auditor arrived. They did the small things consistently. They documented what they did. They noticed discrepancies and addressed them. Audit season becomes a checkpoint instead of a crisis. And the company emerges stronger each year because clarity became part of how it operates.
No, Texas Did Not Ban Merchant Cash Advances
January 28, 2026 When Texas passed HB 700 last June, deBanked was among the first to point out that its most notable component was a prohibition on automatic debits of a recipient’s deposit account by a commercial sales-based financing provider unless they had a perfected first position. Some observers were quick to tell us that we had it all wrong, that MCAs had effectively been “banned” entirely and that we should have reported it that way. This was premised on a belief that perfecting a true first position on a recipient’s deposit account was a near-insurmountable obstacle (for MCAs that rely on ACHs instead of credit card splits) and thus a nuanced discussion of how to comply with the new law a moot debate.
But if the state legislature had intended to ban sales-based financing outright, it simply could have done so. Instead, it codified a framework for how to legally provide sales-based financing. It provided guidance on registration, disclosure, and oversight. And it even went as far as to say that the Finance Commission of Texas cannot “adopt a maximum annual percentage rate, finance charge, or fee for commercial sales-based financing transactions.” This was an incredible signal: No cost cap on sales-based financing.
The Texas Office of Consumer Credit Commissioner (OCCC) even held an open forum this past November to hear from impacted parties on the best way to craft and enforce the rules going forward. And so while they’re now busy promulgating those precise rules, collective minds have returned back to the original language surrounding that “certain automatic debits” are “prohibited.”
CERTAIN AUTOMATIC DEBITS PROHIBITED.
A provider or commercial sales-based financing broker may not establish a mechanism for automatically debiting a recipient’s deposit account unless the provider or broker holds a validly perfected security interest in the recipient’s account under Chapter 9, Business & Commerce Code, with a first priority against the claims of all other persons.
This language does not say that merchants cannot pay sales-based financing providers entirely. Others agree. deBanked spoke with one company, MCA Pay, which analyzed what the law says and they created a tool for merchants to pay sales-based financing providers in an orderly easy manner so that funders do not in fact have to automatically debit a recipient’s deposit account at all. Though there are some layers to how it’s done, merchants are, on their own volition, setting up a system to initiate payments to whichever funder they choose. They’re in control.
Far from theoretical, this methodology is already being used by merchants in Texas to pay sales-based financing providers, according to MCA Pay.
“We’re comfortable from a regulatory perspective, but I encourage everybody who uses this platform to run this by their counsel,” a representative said. “We’re putting the control back into the merchant’s hands.”
The two main partners at MCA Pay, Gavriel Kalfa and Moshe Klar, do not hail from within the industry, but they worked with experienced operators in the industry while building out the system. MCA Pay is not the payments provider or a law firm, they’re just the platform that loops the pieces together.
“Hopefully we’ve made a product here that’s going to allow MCA to continue in Texas compliantly for everybody,” they said.
See Post... splits exclusively.... |
See Post... split/lockbox., , i wish. mostly cash. but found a home so thank you all for responding.... |
See Post... split/lockbox.... |