Banking
nCino Partners With Santander
July 24, 2018
nCino partnered with Santander Bank last week, its latest in a string of partnerships with major banks.
“Innovative institutions such as Santander Bank understand the importance of ensuring the customer experience is as fast, easy and intuitive as possible,” said Pierre Naudé, CEO of nCino. “[Santander] also recognizes that a shiny front end means nothing if the middle and back office doesn’t embrace at least the same degree of automation and intelligence.”
nCino is a cloud-based lending platform that grew out of Wilmington, North Carolina-based Live Oak Bank in 2012. Its founder, James Mahan III, then CEO of Live Oak Bank, along with his team, recognized a need to make the commercial lending process less time-consuming. So they created the nCino Bank Operating System internally for Live Oak Bank. But it soon attracted the interest of other financial institutions, in the US and beyond.
Last year, nCino told deBanked in that in addition to working with Live Oak Bank, it was working with more than 150 other financial institutions in multiple countries, including nine of the top 30 US banks. Now, according to the nCino website, over 200 banks and credit unions of varying sizes use the company’s Bank Operating System. TD Bank and SunTrust are among their largest bank partners.
An nCino spokesperson told deBanked that its Bank Operating System is sold on a subscription-basis that is driven by individual annual user licenses. This allows employees, executives and other stakeholders of a financial institution to access the benefits and functionality of nCino’s solution. nCino spun off from Live Oak Bank and became its own entity in 2014. Separately, Live Oak Bank (NASDAQ: LOB) went public in 2015.
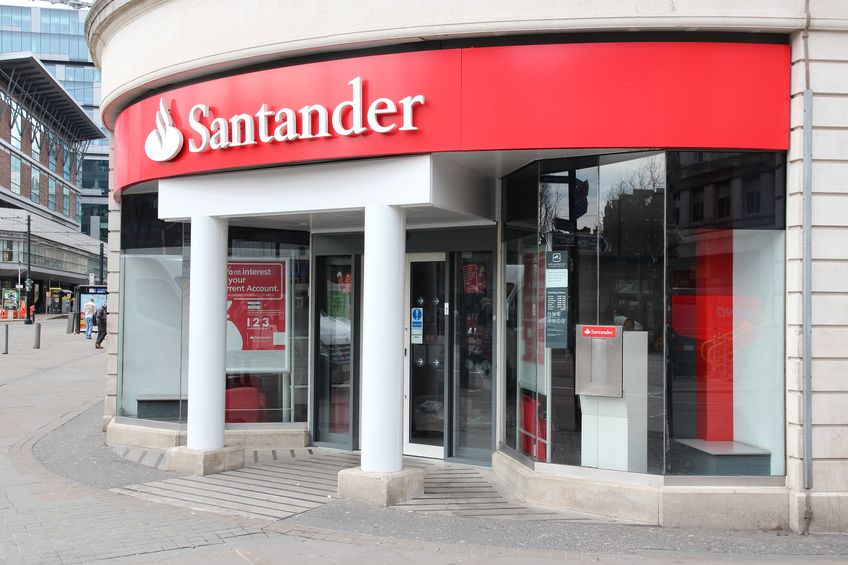 Santander will be using nCino’s platform for its business banking clients. Santander says that nCino’s cloud-based platform is accessible to customers from any device and will reduce the time it takes Santander to deliver loan decisions from start to finish by approximately 40 percent. In conjunction with a partnership with Accenture, Santander will be using nCino’s platform to help with customer relationship management, loan origination, account opening, workflow, enterprise content management, and instant reporting capabilities.
“Respecting our customers means giving them more insight into the loan process and getting them their money faster without any impediments so they can focus on running their businesses,” said Amir Madjlessi, Executive Vice President and Managing Director of Business Banking at Santander. “nCino’s platform automates the lending process from start to finish in a way that ensures a seamless, transparent experience for our customers that reduces delays and inefficiencies and securely connects our clients to our bankers whenever they need them with the touch of a button.”
nCino employs 500 people and is headquartered in Wilmington, North Carolina. The company recently opened an office in London and has plans to open additional offices in Australia and Canada later this year, according to a company spokesperson.
Texas Man Defrauds Banks with Cattle
July 18, 2018 A Texas man was arrested last week on allegations of using 8,000 heads of cattle he did not own as collateral for outstanding loans of more than $5.8 million, according to Dallas News.
The arrest was the culmination of a 16-month investigation carried out by the Texas and Southwestern Cattle Raisers Association. They were contacted by bank officials at the First United Bank in Sanger, Texas, who said that Howard Lee Hinkle had not made payments on loans with balances totaling more than $5.8 million. The bank obtained a court order to collect the 8,000 cows that Hinkle put up as collateral, but they were unable to find any of the cattle at the locations he had given the bank. Hinkle allegedly presented fake documentation.
Fintech lenders have also been victims of fraud whereby a merchant provides false documents, sometimes claiming to own property they do not own
Charged with first degree felony charges of theft, the 67-year-old Hinkle could serve a life sentence in jail. He was arrested last Thursday and brought to the Wichita County Jail, where he was released on bond pending trial.
FCI Implements Factoring Solution That Is Islamic Law-Compliant
July 17, 2018The FCI, an international trade group focused on factoring, implemented changes to its General Rules of International Factoring so that they are now compliant with Islamic (Shari’a) law. The Amsterdam-based factoring group, which just celebrated its 50th anniversary, worked with Dubai-based Noor Bank and other constituents, to create amendments to its rules that would make it Shari’a law compliant, according to a recent FCI announcement.
While the details of the changes to FCI’s rules were not immediately available, deBanked spoke to Abed Awad, founding partner at New Jersey-based Awad & Khoury, who is an expert in Islamic law.
Awad said that Shari’a law’s fundamental problem with factoring is that it involves collecting interest, which is prohibited. While factoring might not seem to involve interest, Awad said that offering less cash upfront for a receivable that is worth more in the future, is essentially a reverse form of interest.
But Awad said that in recent years, people have developed a somewhat controversial concept, called Tawarruq (or monetization) that abides by the prohibition of interest rule while yielding the same result. This is how it works:
A merchant in need of cash goes to a bank. Rather than offering cash to the merchant, the bank instead arranges for a merchant to buy a commodity (like oil or sugar), on credit. The merchant doesn’t have to pay for the commodity until a future date. Meanwhile, the merchant quickly sells the commodity for cash to a third party. The merchant now has cash and will not be paying interest of any kind. The bank still makes money. It gets paid for structuring the arrangement between the merchant and the seller of the commodity, and for evaluating the creditworthiness of the merchant.
The end result is the same for the merchant. The merchant gets cash quickly, albeit a little less quickly because there are multiple parties involved. Noor Bank currently offers an Islamic law compliant factoring product. Tawreeq Holdings, which has offices in Luxembourg, United Arab Emirates and Morocco, specializes in the Tawarruq alternative to factoring.
“Islamic Factoring is an increasingly important element in the finance of international trade and our ability to support Shari’a compliant business is particularly important for our global member base, said Peter Mulroy, Secretary General of FCI. “This development is another real enhancement of the support we can provide for our members.”
Walmart Not New to Financing
July 17, 2018 Walmart is considering switching its branded credit card business partner from Synchrony Financial to Capital One Financial Group, according to a Bloomberg report. Accordingly, the change in banking partner is related to the retailer’s vision for Walmart Pay, Walmart’s current checkout payment system.
In light of this, it is worth noting that Walmart is no stranger to working creatively and ambitiously with banks. In fact, aside from currently having independent bank branches that operate from inside Walmart stores – including Fort Sill National Bank and City National Bank and Trust – Walmart once had aspirations to become a bank.
In 2006, using an old and now controversial statute, the behemoth retailer attempted to get a charter to become an Industrial Loan Company (ILC) Bank. Chris Cole, Senior Regulatory Counsel at Independent Community Bankers of America (ICBA), a trade group, told deBanked that banks and other anti-Walmart groups banded together to thwart the retailer’s plans.
Recently, two fintech companies, SoFi and NelNet, have submitted applications to become ILC banks.
Lendistry Becomes a Member of the Federal Home Loan Bank of San Francisco
July 11, 2018
Lendistry announced yesterday that it has been approved for membership by the Federal Home Loan Bank of San Francisco. This will allow the lender to expand its commercial real estate loan business, which Lendistry launched in January.
“It’s an honor to be a member of the Federal Home Loan Bank of San Francisco, an organization committed to community development by expanding availability of credit,” said Lendistry CEO Everett K. Sands. “We look forward to leveraging our unique business model of being a hybrid of a community bank and a fintech company to expand access to capital to all.”
Lendistry offers SBA loans (up to $250,000), traditional small business, or term, loans (up to $1 million), bridge and short-term loans (up to $500,000), and most recently, commercial real estate loans (up to $2 million). Sands told deBanked that about 65 percent of its business is derived from SBA loans, about 30 percent comes from term loans, and the remainder is a mix from the other loan types. Of the term loans, Sands said that the average is a four year loan with a 12 percent interest rate.
About 70 percent of Lendistry’s business comes from a combination of bank referrals and commercial loan brokers, or ISOs. Otherwise, Lendistry obtains customers from affiliate partners, like Lending Tree, and from its own direct efforts. Out of a 22 person team, Lendistry employs eight salespeople. And Sands said that about 70 percent of the team has a banking background.
Lendistry customers come from a variety of industries including healthcare, restaurants and home improvement. Sands said that the bulk of its business comes from merchants in the medical and manufacturing industries because these are the types of companies that their bank partners have been sending them lately. The lender also makes a fair amount of loans to restaurants, Sands said.
Lendistry has a partnership with The Center, a nonprofit that provides small business owners with educational resources, such as workshops, training videos, coaching sessions, and networking opportunities. Founded in 2015, Lendistry is based in Brea, California, outside of Los Angeles.
The Past, Present and Future of the ILC Bank
July 9, 2018 Last Thursday, Square confirmed that it withdrew its application to the FDIC for depository insurance, which would allow it to take deposits from customers in all 50 states. The company said it plans to refile.
This is not the first time that a fintech company has withdrawn a bank application from the FDIC. Last October, SoFi withdrew its application in the wake of sexual harassment allegations against its then CEO Mike Cagney. SoFi has not explicitly stated that it plans to refile.
Regardless of the reason for withdrawing the application, this news revives the debate over whether fintech companies should be allowed to become banks in the first place – at least in the manner that Square and SoFi have sought to attain bank status. Both companies have submitted applications to the Utah Department of Financial Institutions to become Industrial Loan Company (ILC) banks.
This is controversial because ILC banks are not subject to the same regulations that other banks are. For instance, an ILC bank can engage in commercial activity outside of banking which could jeopardize the bank, critics contend. Under the 2010 Dodd-Frank Act, which came in response to the Great Recession, there was a moratorium on establishing ILC banks because they were deemed to be a risk to the U.S. banking system. The moratorium was lifted in 2013.
Chris Cole, Senior Regulatory Counsel at Independent Community Bankers of America (ICBA), a trade group, is a big opponent of ILC banks. He maintains that companies seeking to become ILC banks are simply taking advantage of an old policy that is no longer relevant. He explained that ILCs were created as banks for industrial workers in the early 1900s.
“They were meant to serve a certain type of industrial worker that had trouble finding a commercial bank they could bank with,” Cole said. “Now we don’t have that problem anymore. Industrial [or other lower paid] workers have plenty of opportunities to bank. This charter is completely outdated [and is] a loophole that should be closed so that the owners of these bank-like institutions are restricted in the same way that commercial banks are restricted.”
Last year, deBanked spoke to Richard Hunt, president and CEO of the Consumer Bankers Association, who echoed Cole with the regard to the initial purpose of ILC banks.
“No one envisioned when they wrote the ILC charter that we would have fintech companies that finance mortgages and student loans from private equity capital and not deposits. It’s a new world. Like with all rules and regulations, federal regulators should periodically review longstanding policy,” Hunt said.
Cole said that in addition to Square and SoFi, another fintech company recently applied to become an ILC bank. That company is NelNet, which services students loans, and it submitted an application to the FDIC less than two weeks ago.
So far, the FDIC has not approved of any ILC banks since Dodd-Frank. (There are only about 30 of them right now.) But that may soon change under the leadership of the agency’s new Chairman, Jelena McWilliams.
“I am hopeful that Jelena McWilliams will follow the same course as her predecessors have [and not issue ILC charters],” Cole said. “Issuing a moratorium is what I’d like to see.”
But McWilliams, who assumed the new role on June 5, may be more open to approving these applications than her predecessors. She said during a recent conference:
“The agency has a duty to the public to actually proceed [with the applications.] Now, that doesn’t mean that we will approve every application. That doesn’t mean that we will deny every application.”
American Express Partners with Amazon on SMB Credit Card
June 28, 2018 American Express announced plans this week to partner with Amazon to introduce a co-branded Amazon credit card for small businesses. Amazon does have a co-branded card with J.P. Morgan Chase for consumers shopping on Amazon’s site, and elsewhere. But this would be Amazon’s first card for small business owners.
“At American Express, we have been helping business owners grow for more than 50 years and we know that millions of them rely on Amazon,” said Glenda McNeal, President of Enterprise Strategic Partnerships at American Express in a statement. “We’re delighted to expand our partnership with Amazon by offering a new cobranded small business card, and by also harnessing the collective insights and expertise of our companies to deliver tangible value to our mutual customers who use Amazon’s services.”
This was quite a win for American Express as J.P. Morgan was competing for this partnership as well, according to CNBC. This deal puts American Express in an enviable position to court more small business customers in its effort to become a leading lender to small and mid-sized companies. Small business cards can be very lucrative for banks. Compared to consumers who might spend a few thousand dollars a month on credit cards, businesses can spend up to hundreds of thousands of dollars in monthly bills, according to CNBC.
“We selected American Express as our partner for the upcoming small business credit card because of our shared commitment to helping small businesses grow,” said Max Bardon, Vice President at Amazon in a statement. “Offering the best of both brands, the cobranded small business credit card program will combine the buying power, convenience and value small businesses have come to know and love from Amazon backed by the world-class service, benefits, access and security of American Express.”
Amazon launched Amazon Lending in 2011 to help small businesses finance and sell more goods on its platform. From the 2011 launch to June 2017, Amazon Lending reported that it issued $3 billion across 20,000 business in the US, Japan, and the UK. And the bulk of the growth has been from small businesses in the US, where the company originated $1 billion in loans in 2017 alone. So small business lending, particularly in the US, is big business for Amazon.
This new co-branded Amazon/American Express card for small businesses is part of a series of new partnerships between the e-commerce behemoth and banks. In February of this year, it was reported that Amazon had partnered with Bank of America Merrill Lynch to provide loans to merchants (on an invitation-only basis) from $1,000 to $750,000.
HSBC Bank and SoftBank Robotics America Welcome “Pepper” the Robot
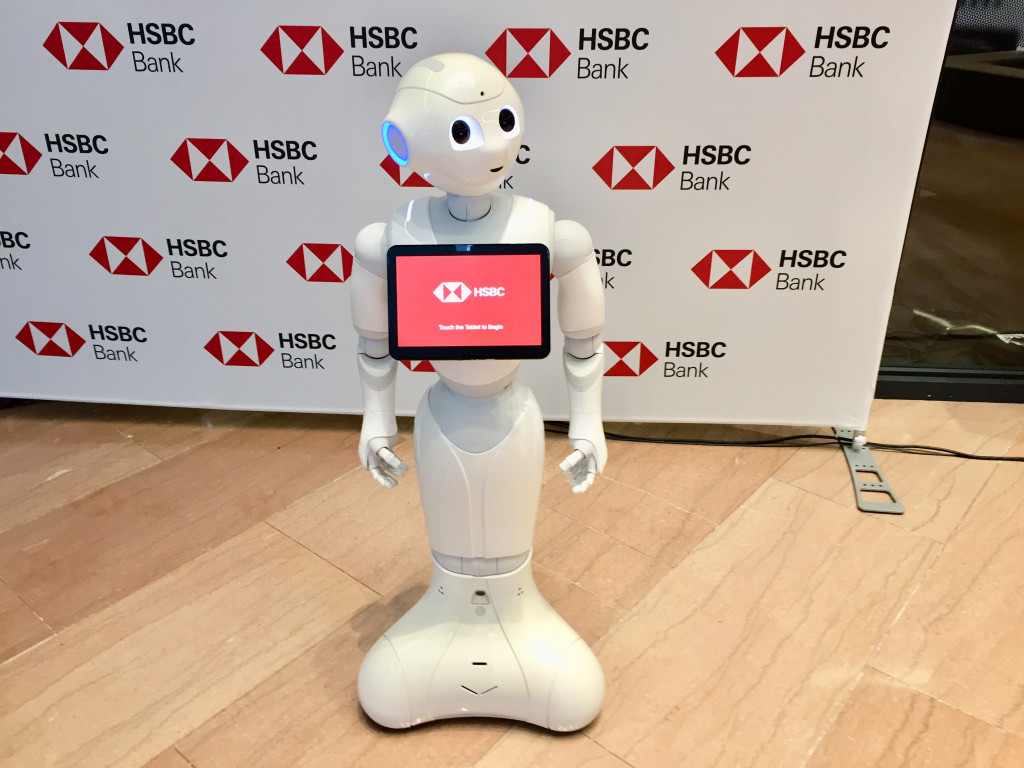
June 26, 2018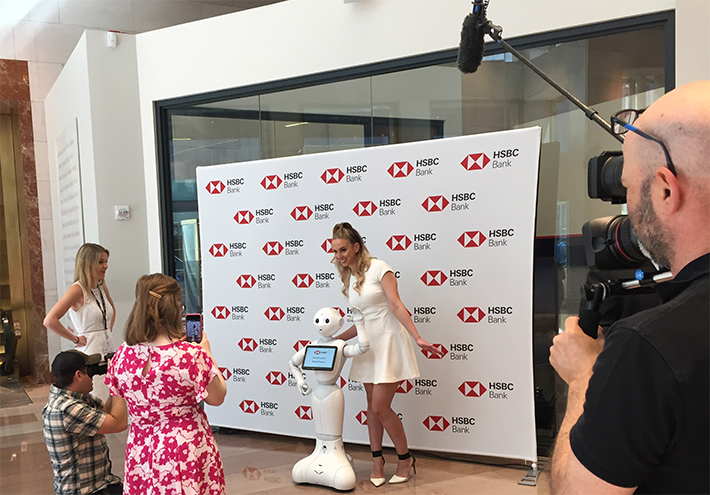 A partnership between HSBC Bank and SoftBank Robotics America came to fruition this morning when a robot named Pepper was introduced to media at HSBC’s North American flagship retail branch on Fifth Avenue in midtown Manhattan.
“Thank you for joining us to make history today,” HSBC Head of Innovation Jeremy Balkin said at the flagship bank.
Pepper is the first robot to operate at a retail bank in North America, according to Julien Seret, VP of Global Product at SoftBank Robotics America. Pepper is four feet tall and can hear, speak and move its head to simulate eye contact. You can interact with Pepper by speaking to it or by tapping the tablet on its chest.
“We’re not replacing people, we’re giving them more time to do what they’re good at,” Seret told deBanked.
Seret said that there are already 15,000 Pepper robots being used in throughout the world, many of them in the hospitality industry. There is a Pepper robot that greets visitors at the Mandarin Hotel in Las Vegas and at least one at the Oakland airport in California. They are helpful to provide any repetitive information and are also used at hospitals.
 “Pepper is great for engagement with kids,” Seret said of children at hospitals.
Pablo Sanchez, Head of Retail Banking at HSBC, said that HSBC staff brought Pepper outside on the street yesterday for two minutes and 200 people surrounded the robot. Of the onlookers, one came in to learn more about HSBC’s products and then opened multiple accounts. With foot traffic at the Fifth Avenue flagship branch of 18 million people a year, part of Pepper’s appeal is to draw in potential customers.
“But [Pepper] is not just a gimmick,” Sanchez said.
Right now, Pepper mostly serves the role of a knowledgeable greeter, answering questions like “Where can I deposit a check?” Pepper will tell people where to find the ATM machines. But Sanchez said that down the road Pepper could help people open accounts.
While Pepper is capable of facial recognition and collecting and storing other data, Pepper doesn’t that because of privacy laws that SoftBank Robotics and HSBC must abide by and are very respectful of, said Head of Studio at SoftBank Robotics Omar Abdelwahed. But Abdelwahed said that Pepper would be capable of recognizing a regular hotel guest, knowing that the guest is part of a loyalty program and then upgrading the guest’s room.
A Pepper robot is $25,000 to buy, although SoftBank is mostly using a leasing model where users pay about $16,000 for the robot.