US Business Funding Will Retain Name & Special Sauce in Wake of Fora Deal
June 8, 2018Fora Financial’s announcement yesterday that it acquired a sizable stake in US Business Funding (USBF) will create one of the “largest, broadest reaching direct sales organizations in the small business alternative lending space,” the company said in a statement.
USBF is a direct sales and marketing company of about 40 to 50 people. Fora Financial founder and CEO told deBanked that his company started working with USBF to obtain leads two years ago and that this acquisition has been in the works for between 12 to 18 months.
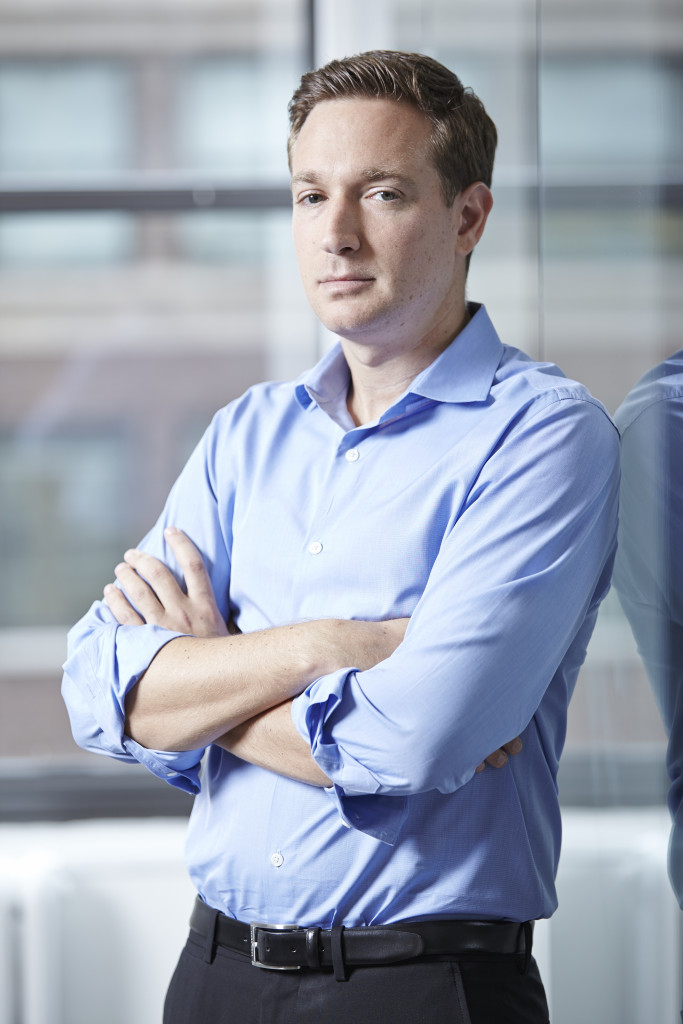 Jared Feldman, CEO, Fora Financial
“We were looking for a team that does direct sales and marketing that complements what we do,” Feldman said. “And they’re one of the best at [direct marketing] in the business.”
USBF is based in Santa Ana, CA, and has connected customers to financing since 2008, with an emphasis originally on equipment financing. In 2012, they started facilitating working capital deals and that now makes up 85 percent of the company’s business, according to its CEO Peter Ribeiro.
They provide financing solutions ranging from $10,000 to $10 million. Fora Financial, also established in 2008, is a New York-based funding company that funds MCA deals and provides small business loans up to $500,000.
Consistent with yesterday’s announcement, Feldman said that with Fora Financial and USBF combined, they will likely originate $400 million year. Feldman told deBanked today that, of this amount, about $300 million should come from direct sales.
“We’re more heavily weighted towards direct sales,” Feldman said.
Formerly a company of 100, the new entity will now include about 150 employees and will share resources like capital, technology and access to help with compliance, Feldman said. USBF will retain its name, location and all of its employees.
“We wouldn’t have done this deal unless Peter [USBF founder and CEO] and his team agreed to stay on,” Feldman said. “They have a fantastic brand and we want to avoid getting in their way. We just want to help them to continue doing what they do.”
Feldman said that while USBF will retain its name, “we’re now a combined entity with an east and west coast operation.”
Fora Financial acquired USBF because it did something unique, and Feldman said that Fora is looking for opportunities to acquire other companies that do uniques things in the financing space.
How Gibraltar Capital Advance Became Wellen Capital
June 4, 2018 Gibraltar Capital Advance announced today that it has changed its name to Wellen Capital. The company had been a sister company of Gibraltar Business Capital, but since that company was acquired in March of this year, Gibraltar Capital Advance has operated independently.
“The Gibraltar name has been well-regarded as a leader in the alternative finance market for many years,” said Jim Teppen, President of what is now known as Wellen Capital. “We entrust it to our former colleagues at Gibraltar Business Capital, knowing they’ll successfully carry the brand’s tradition forward.”
Wellen is no one’s surname at the company, according to Chief Revenue Officer Steve O’Connor.
“One of the things that makes us unique in the capital advance space is that we’re from Chicago,” O’Connor said. “We’re a midwestern company, and the way that we crafted this name had a lot to do with words and phrases and images that were midwestern, even though it’s not obvious.”
O’Connor also noted that Wellen is easy to say and easy to type. In addition to the name change, the company also announced today the WellenScore Application Scoring System, Wellen’s proprietary, data-driven system for evaluating applications.
O’Connor acknowledged that alternative finance companies have been using algorithms to make funding decisions for years, with varying degrees of success.
“Our approach was always to gather enough data first to make sure that we had enough information to inform a data enabled decisioning model,” O’Connor said of Wellen, which was founded in 2012. “And that’s not the kind of thing you can just do overnight.”
The company has been using this system now for more than six months. This doesn’t mean that Wellen now relies exclusively on computers to make funding decisions.
“Our process leverages automation and data-enabled decisions, but isn’t just a ‘black box,’” said Wellen Chief Operating Officer Ed Job. “Good funding decisions are made by working with our sales partners to gather needed data and decide how to best structure a capital solution for our customers.”
Wellen, which provides merchant cash advance exclusively, is based in Chicago and employs 30 people.
Why Small Businesses Sought Financing in 2017, and Why They Were Denied
May 24, 2018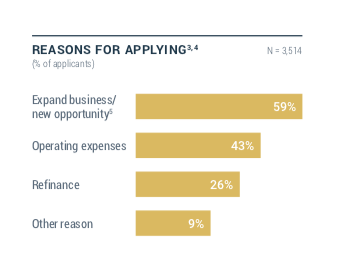 Nearly 60 percent of small businesses applied for financing in 2017 because they wanted to expand their business or pursue new opportunities, according to the latest report by the Federal Reserve. Forty-three percent of small businesses sought financing for operating expenses while 26 percent sought capital for refinancing. Nine percent had a different reason.
Of course, not all applications are funded. Forty-six percent of small businesses received all the financing they sought, 12 percent received most (more than 50 percent) of it, 20 percent received some (less than 50 percent) of the financing they desired and 23 percent were denied financing altogether.
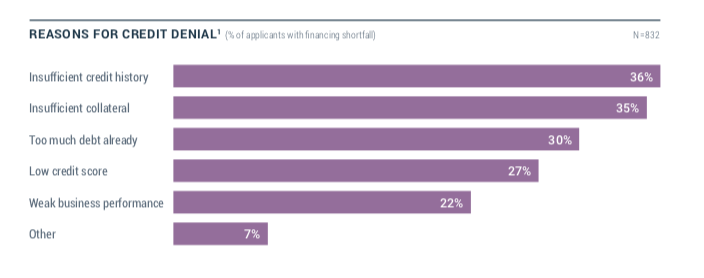
Of the reasons why merchants were denied funding, “Having insufficient credit history” ranked number one, according to the report. A very close second was “Having insufficient collateral,” followed by “Having too much debt already.” After that, in descending order, came “Low credit score,” “Weak business performance” and “Other.”
The “Having insufficient collateral” category does not apply for MCA financing, but the other categories do. According to Nick Gregory, founding partner at Central Diligence Group, which provides MCA underwriting services, “Having too much debt already” is perhaps the main reason why merchants seeking cash advances get declined.
“A lot of times the merchants are overleveraged,” Gregory said.
He explained that if a merchant also has something like two MCA arrangements (or positions) already, that merchant likely has taken on too many contractual obligations which will often be a reason to decline the application. In Gregory’s experience, another common reason for declining an MCA financing application is “Weak business performance.”
Contradictory to the Federal Reserve report’s top reason for denying financing to a small business borrower, Gregory said that “Having insufficient credit history” is seldom a reason to deny MCA financing. This disconnect likely comes from the fact that the report includes all types of small business financing, with MCA accounting for just seven percent. The number maybe seem small, but it continues to increase while small business applications for factoring have decreased.
More Small Businesses Seeking Merchant Cash Advances Than Factoring
May 23, 2018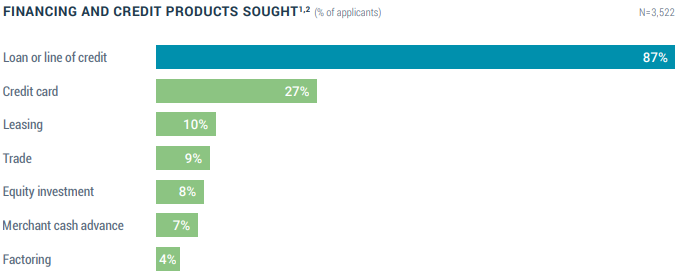 Seven percent of small employer firms in the US that applied for financing in 2017 applied for a merchant cash advance, the latest report by the Federal Reserve shows, while only 4% applied for factoring. Small employer owned firms were defined as businesses that have 1 to 499 full-or part-time employees. 69% of those surveyed generated less than $1 million in revenue last year. That revenue demographic may be on the low end for the factoring industry though. Factoring’s popularity in that demographic, however, decreased in 2017, according to the report. The 4% figure of small businesses that applied for factoring in 2017 was down from 7% in 2016.
Auto and equipment loans had the highest approval rates among all financing options available to small businesses, at 82%. Merchant cash advances followed behind them at 79%. Lines of credit and business loans carried approval rates of 69% and 62% respectively. SBA loans came in at 54%.
When it comes to satisfaction, online lenders such as Lending Club, OnDeck, CAN Capital, and PayPal, have markedly improved over time, the report shows. The net satisfaction score of online lenders has increased from 19% in 2015 to 35% in 2017.
On transparency, online lenders rank at about the same level as large banks, though applicants were more likely to be dissatisfied with the interest rates of an online lender and the long and difficult application process with a large bank.
Missed Broker Fair? Get the Kit and Presentations
May 21, 2018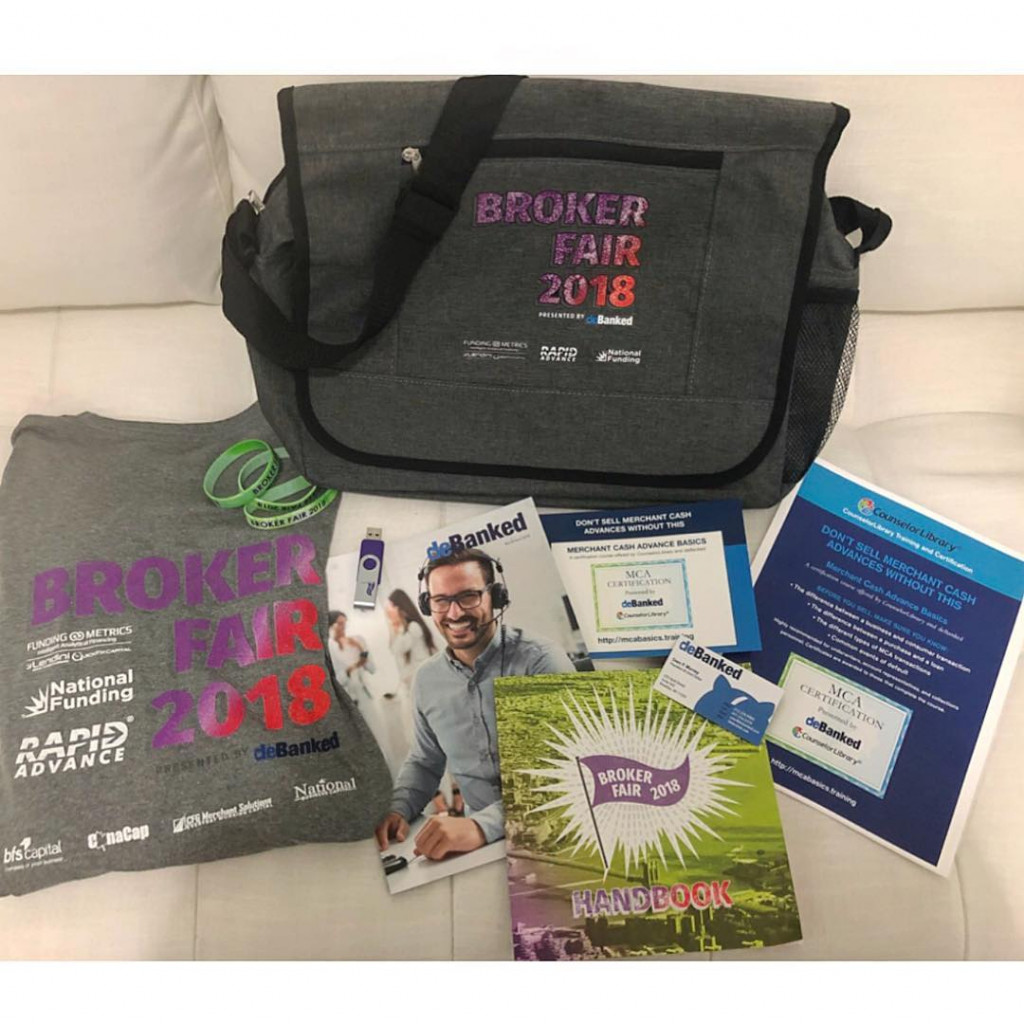
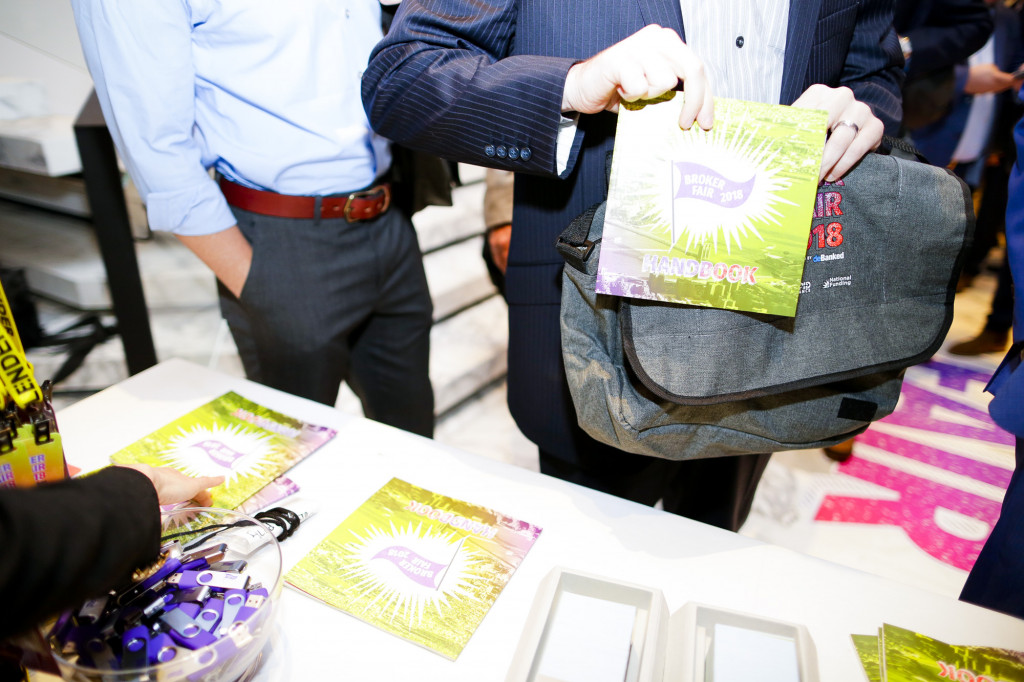
If you missed Broker Fair, you can still get your hands on some of the gear and the presentations. Simply email info@brokerfair.org and ask to be shipped a copy of the Broker Fair Kit. The accessories, which will only be provided while supplies last, include a USB drive with the day’s presentations, a Broker Fair bag, a Broker Fair shirt, a deBanked magazine, a Broker Fair handbook, and more.
Also, don’t wait too late to REGISTER for deBanked’s half-day event in San Diego on October 4th. deBanked Connect: San Diego will connect funders, brokers, and folks from the industry for networking and cocktails!
Broker Fair 2018 Story Continued
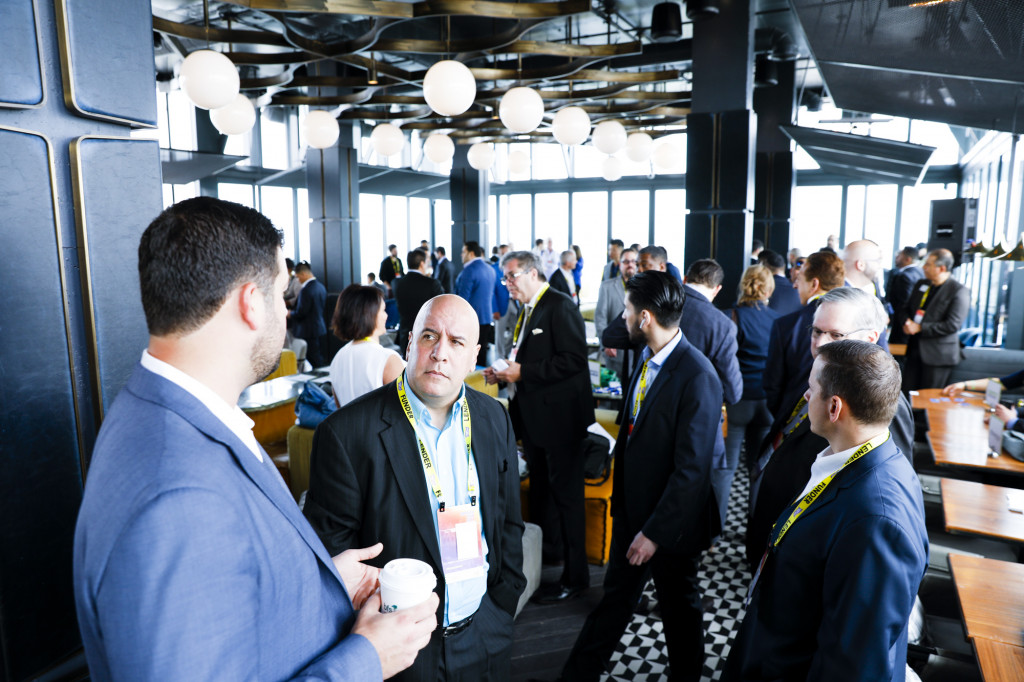
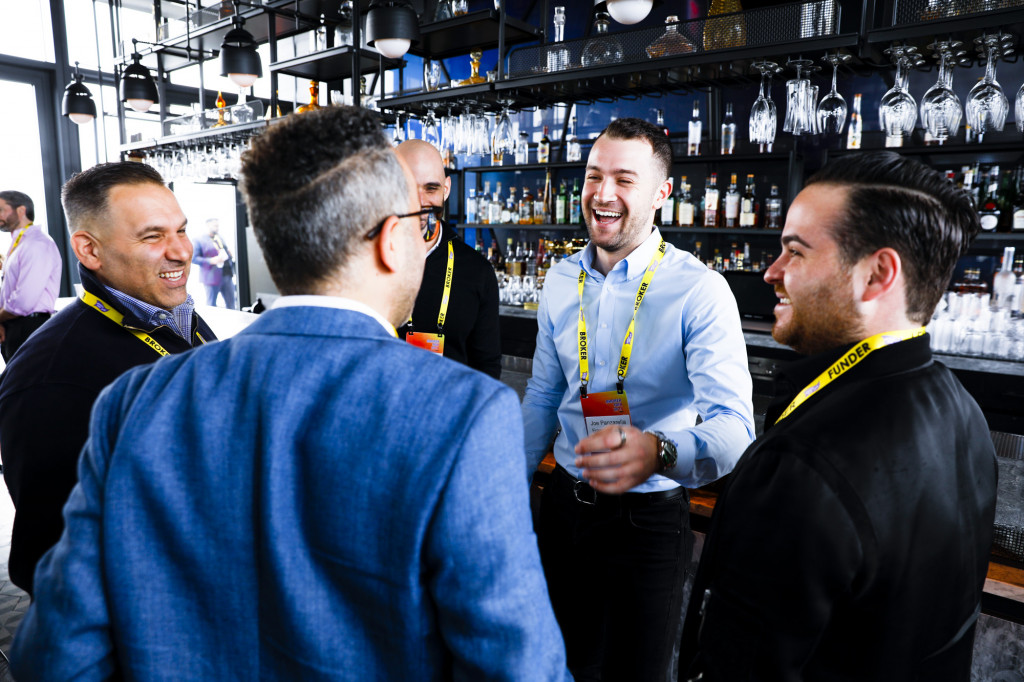
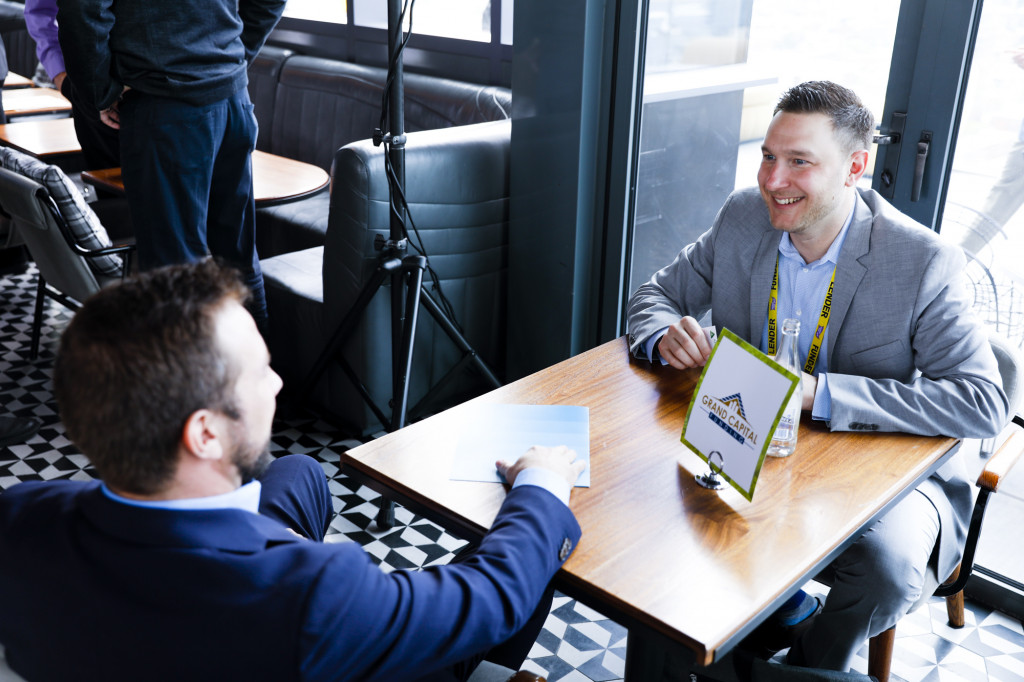
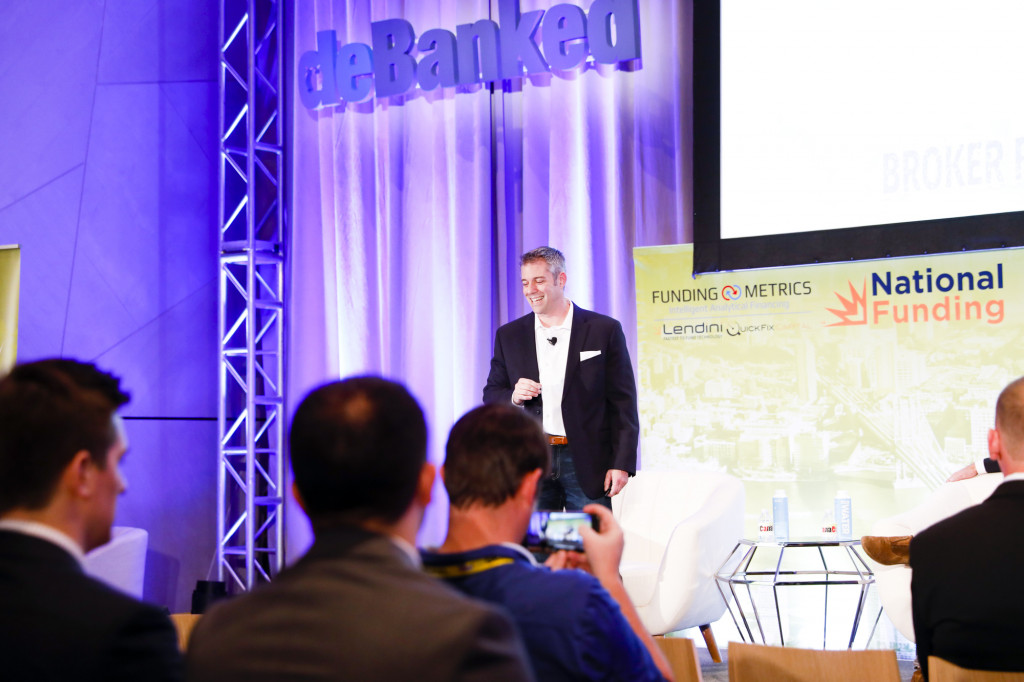
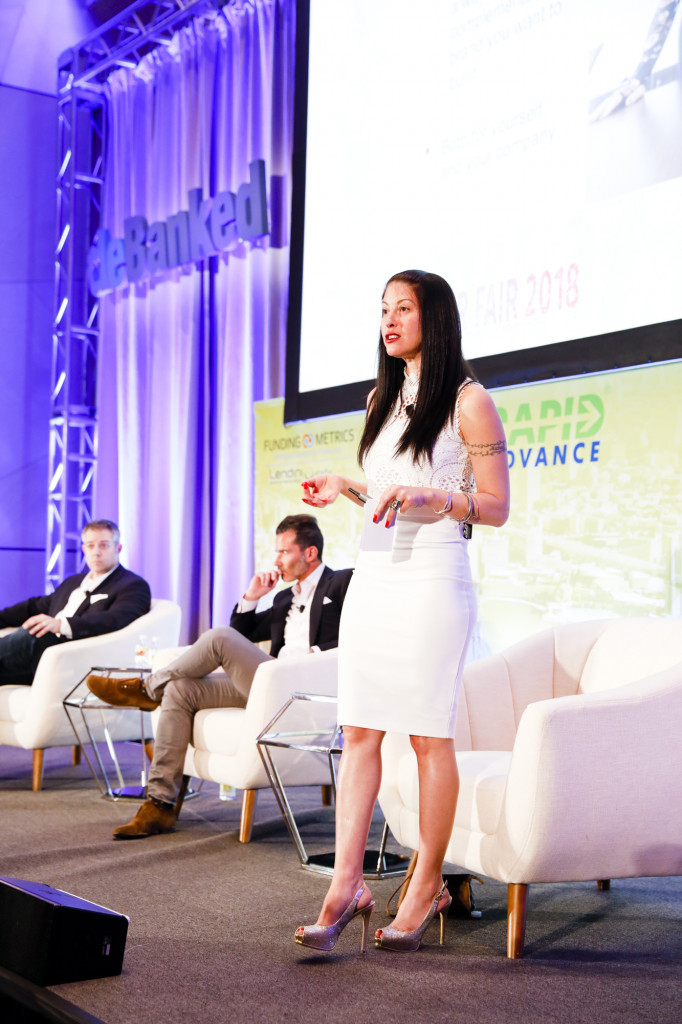
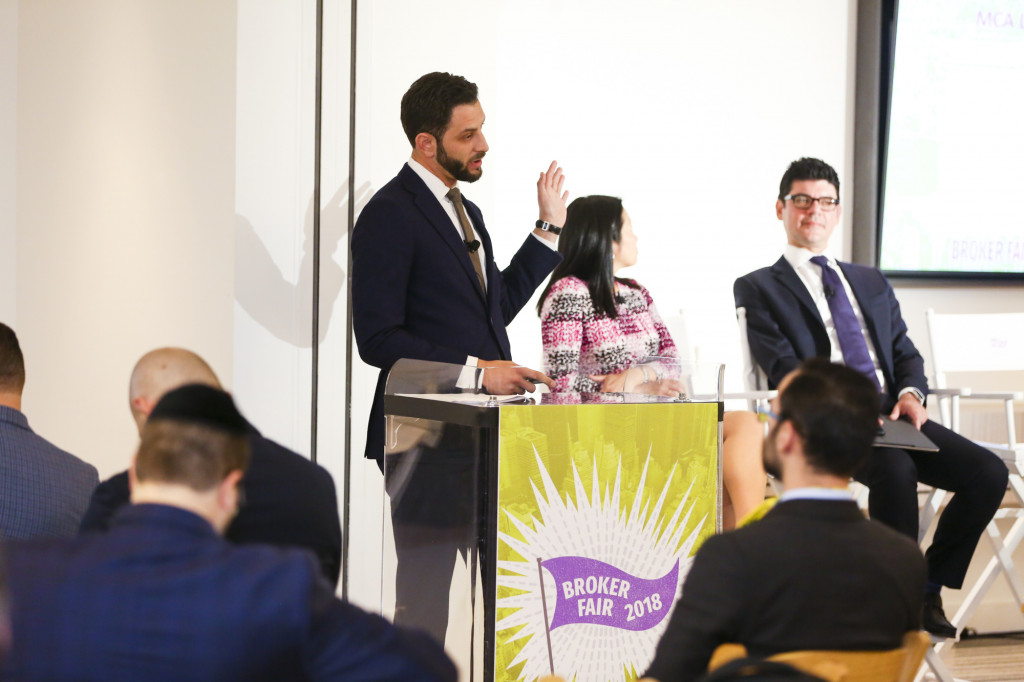
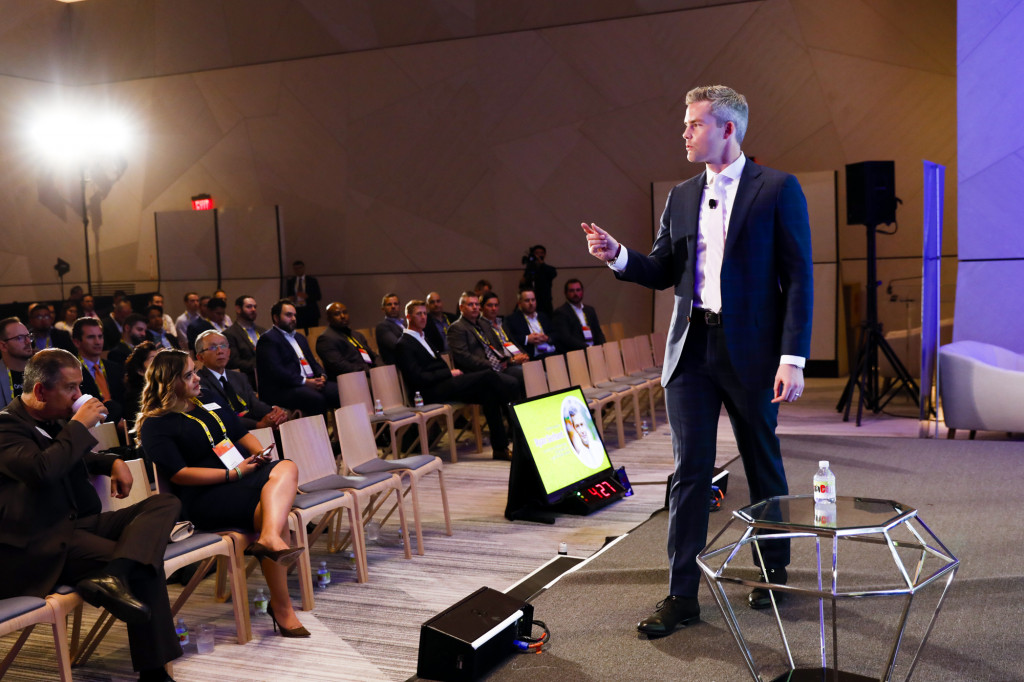
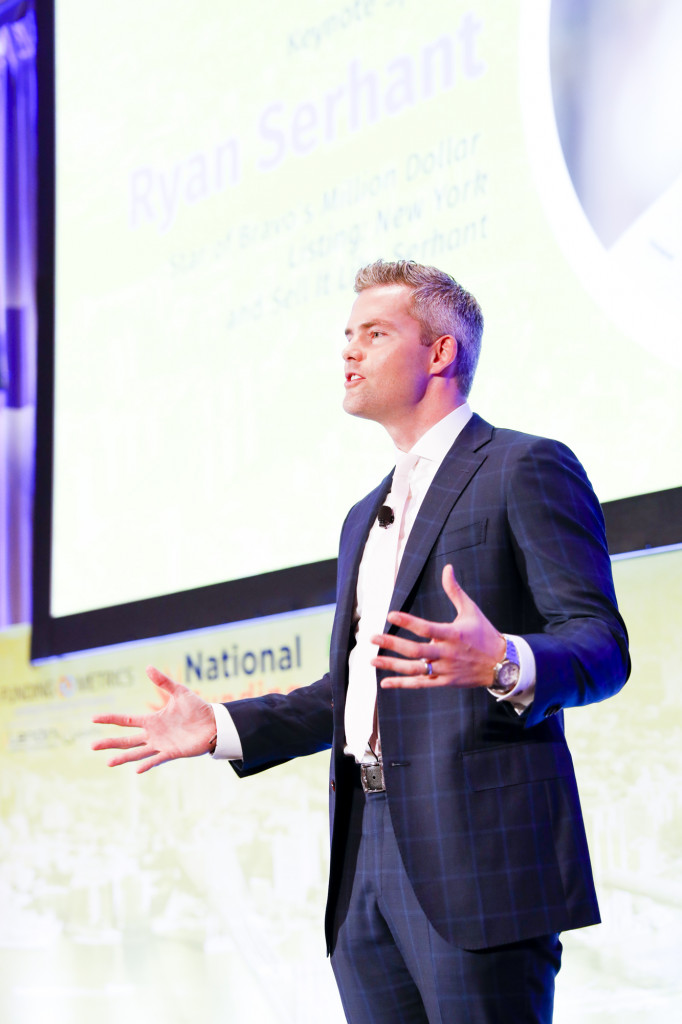
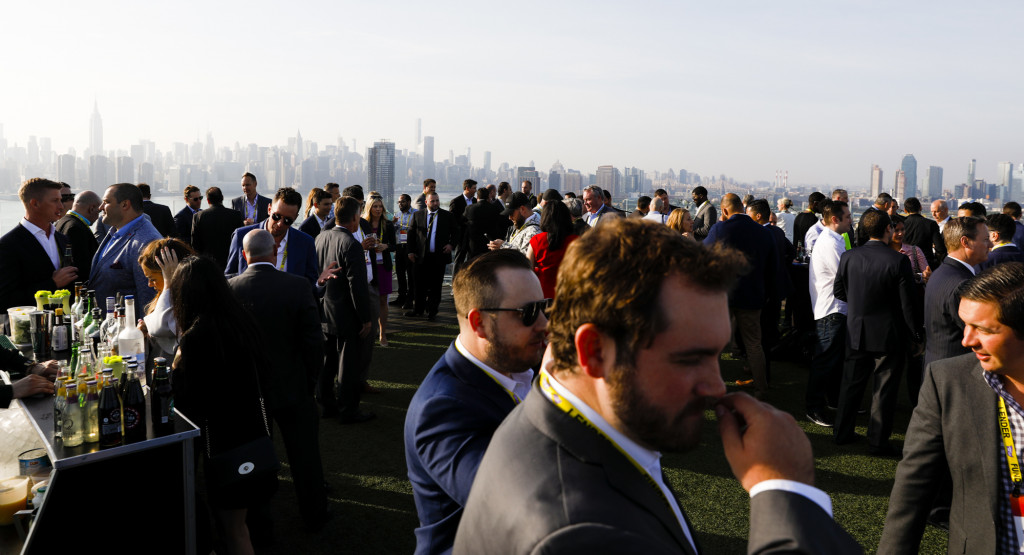
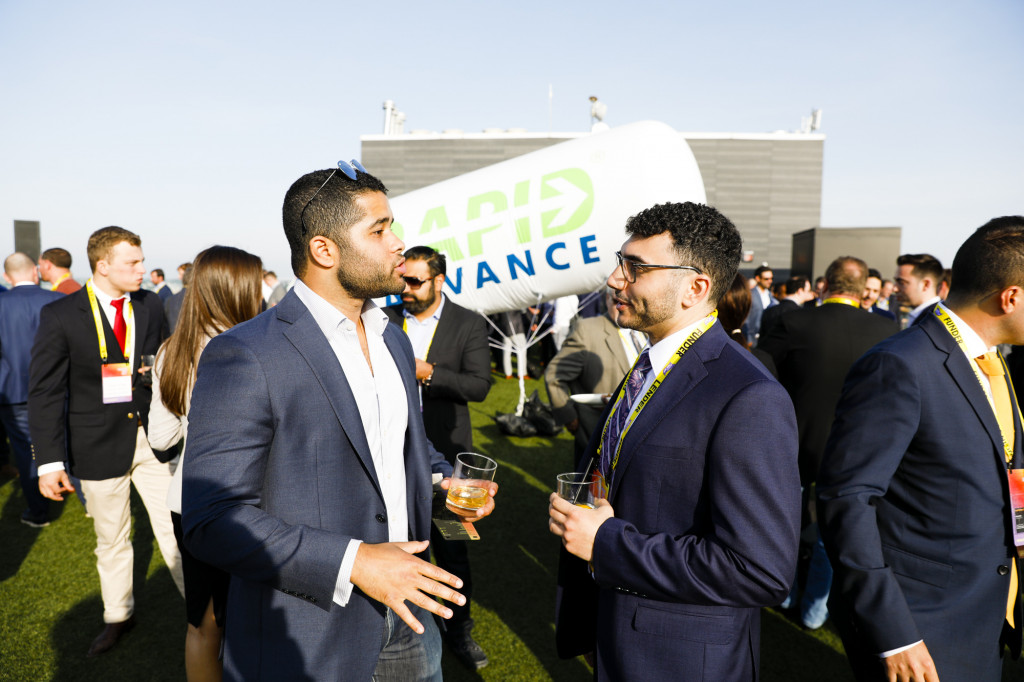
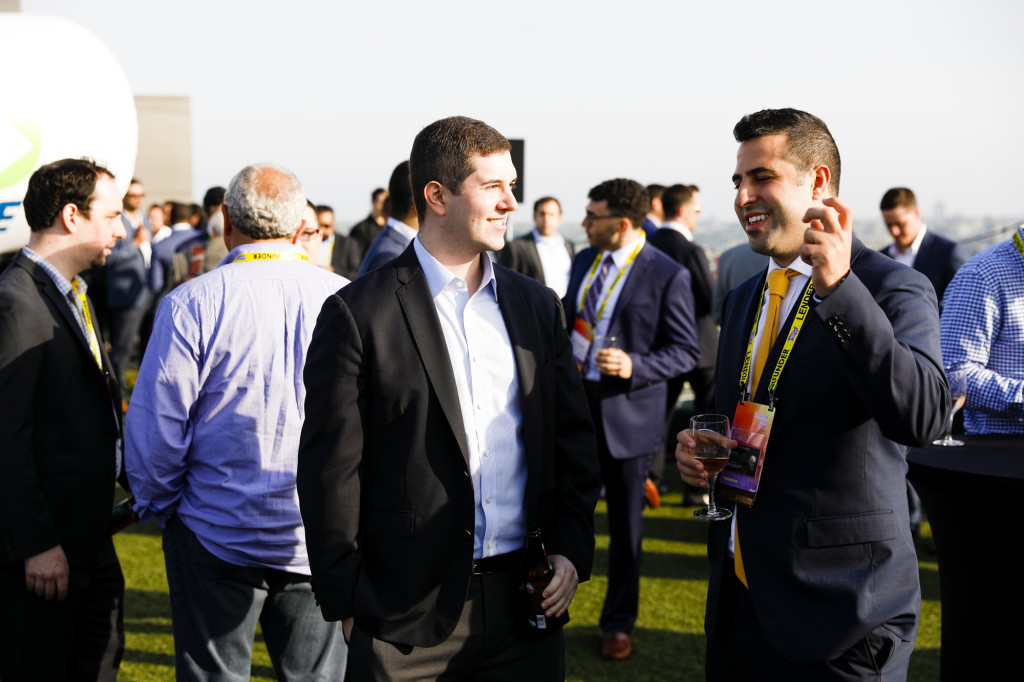
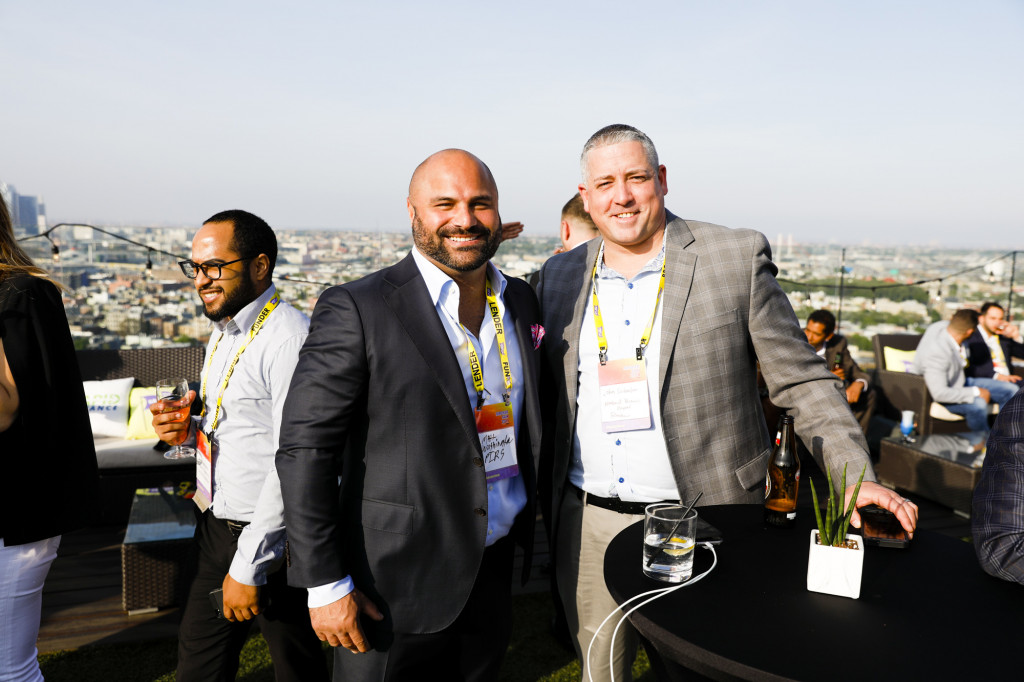
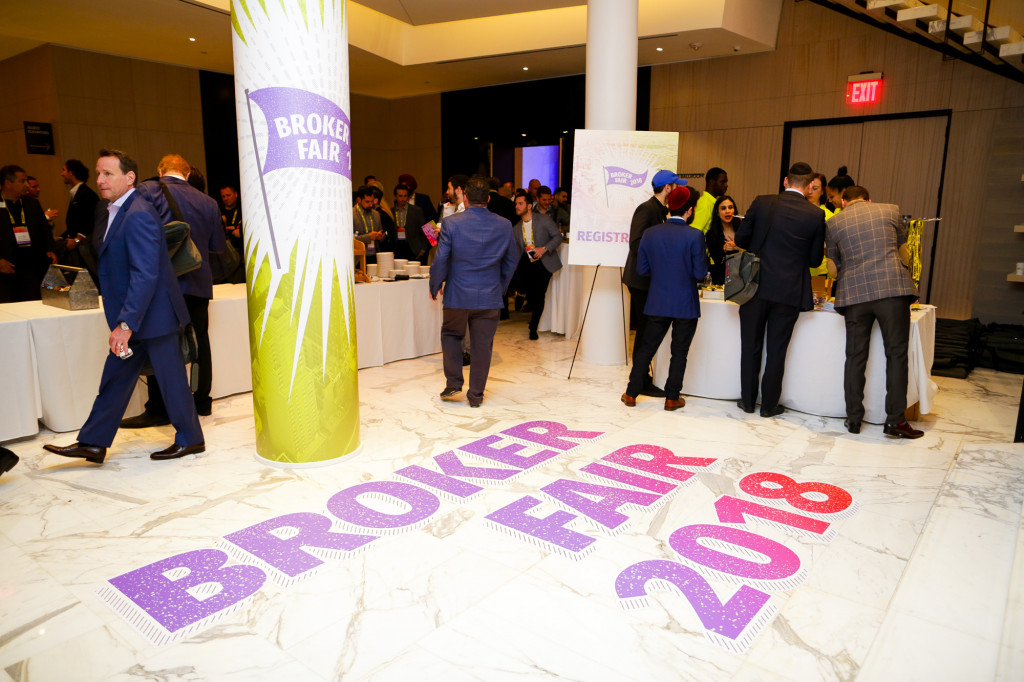
May 18, 2018A continuation of Broker Fair 2018 through photos:
We’ll publish the entire cache of them in the coming weeks.
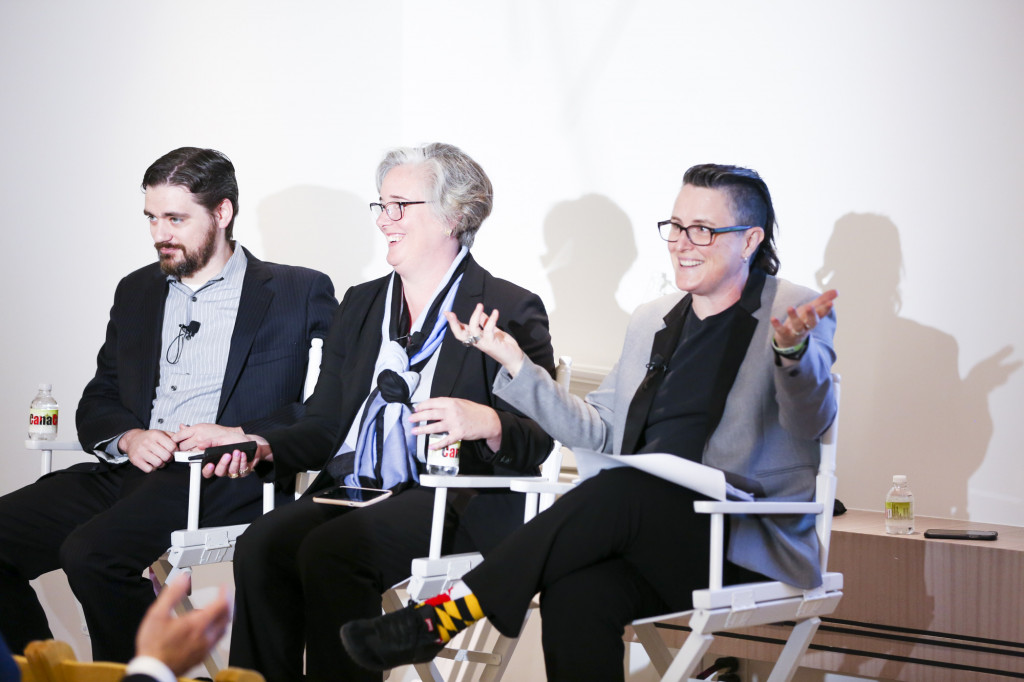
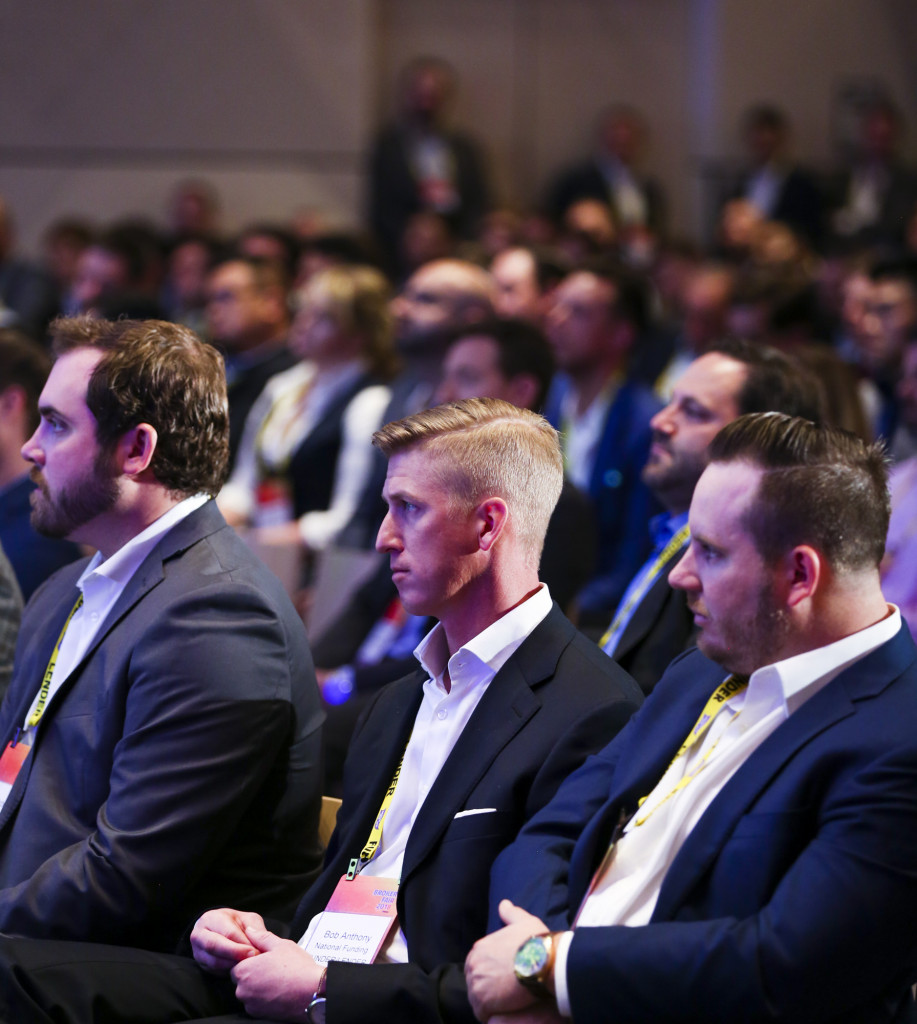
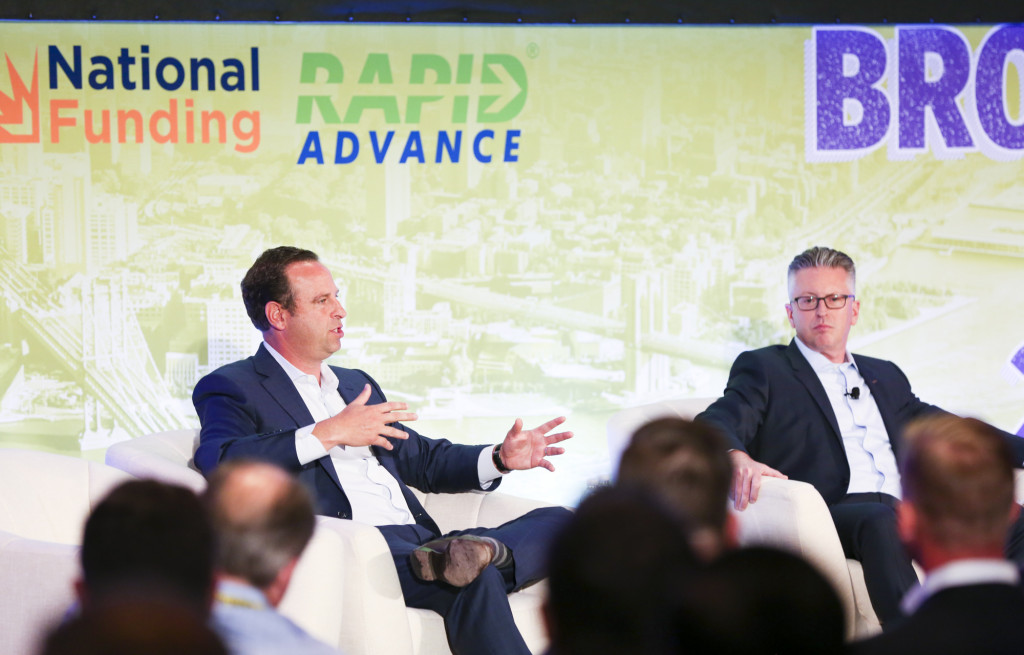
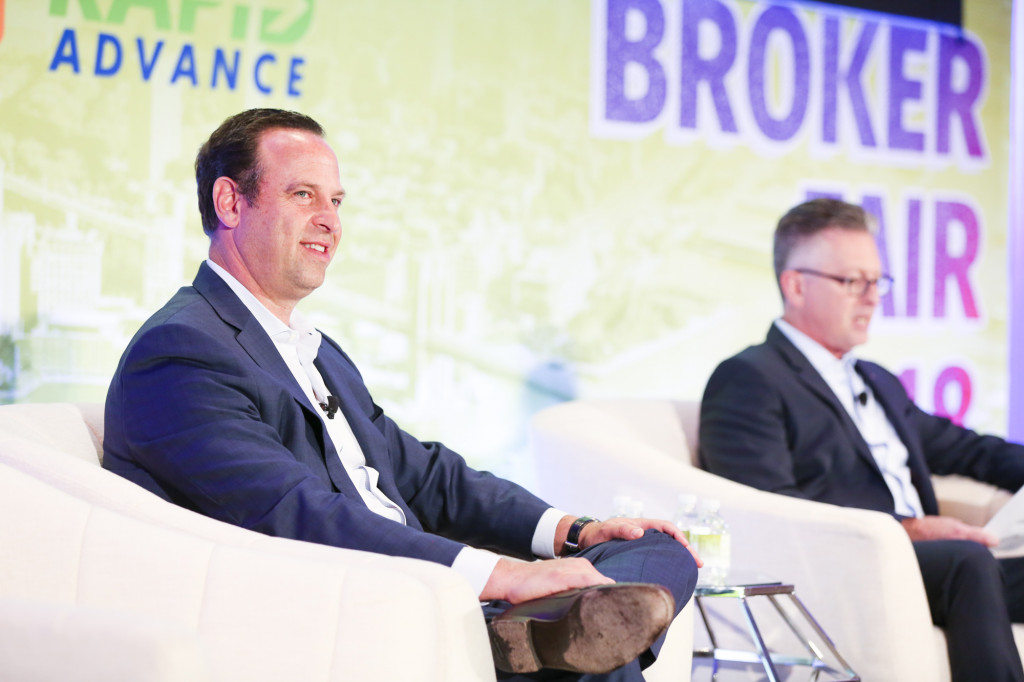
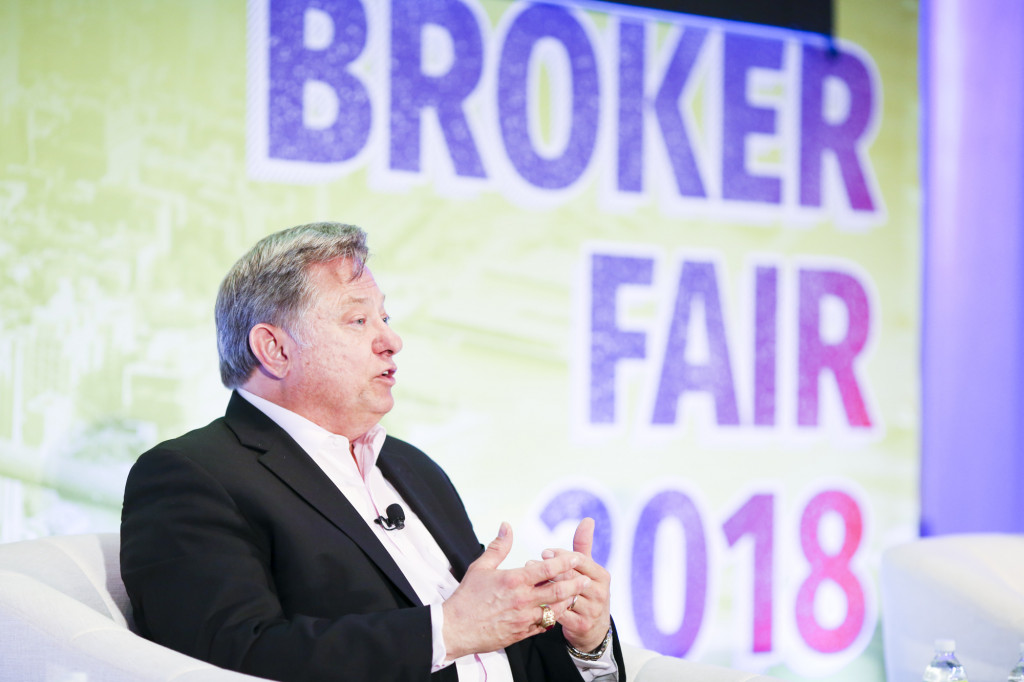
JOIN US OCTOBER 4TH IN SAN DIEGO AT THE ANDAZ FOR A SPECIAL HALF-DAY INDUSTRY NETWORKING EVENT
Couldn’t find yourself in any of our photos? We’ll publish the full album in the following weeks.
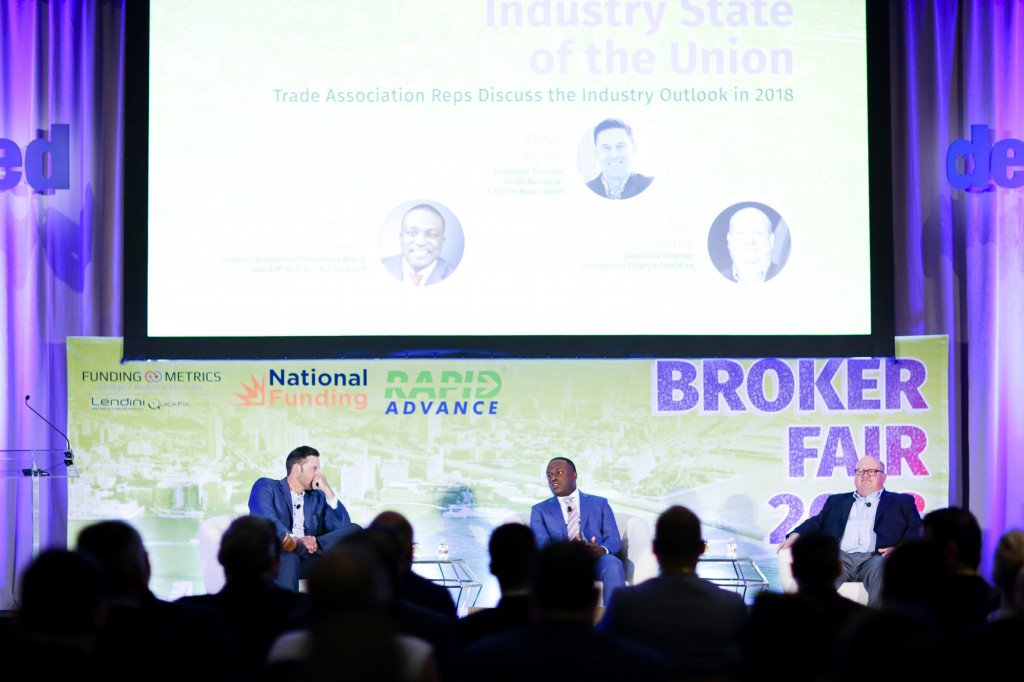
The Broker Fair 2018 Story Through Photos
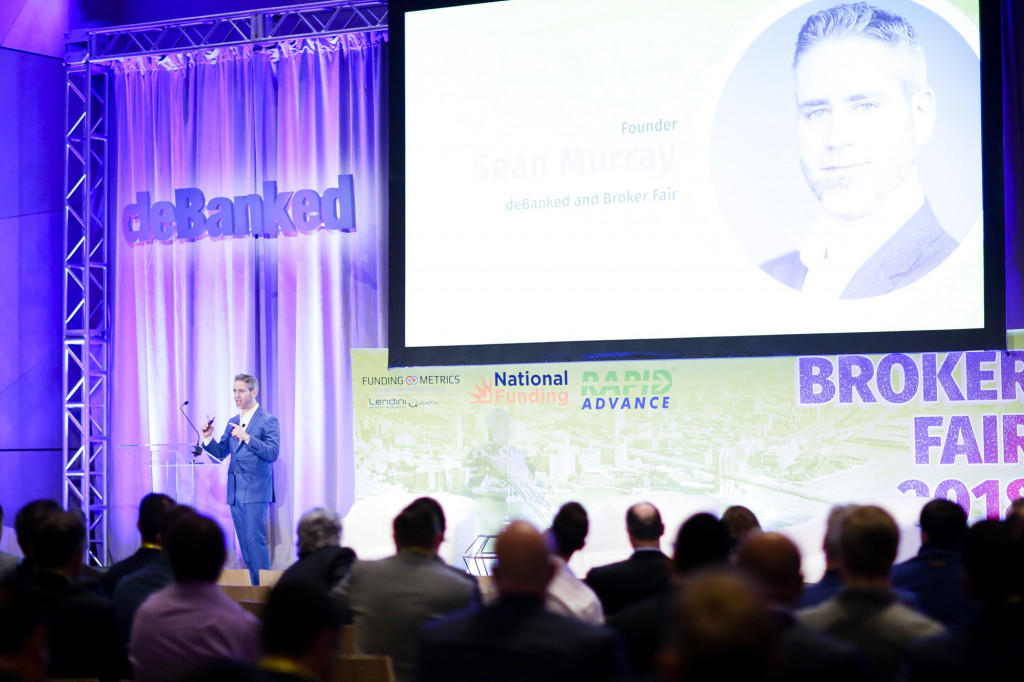
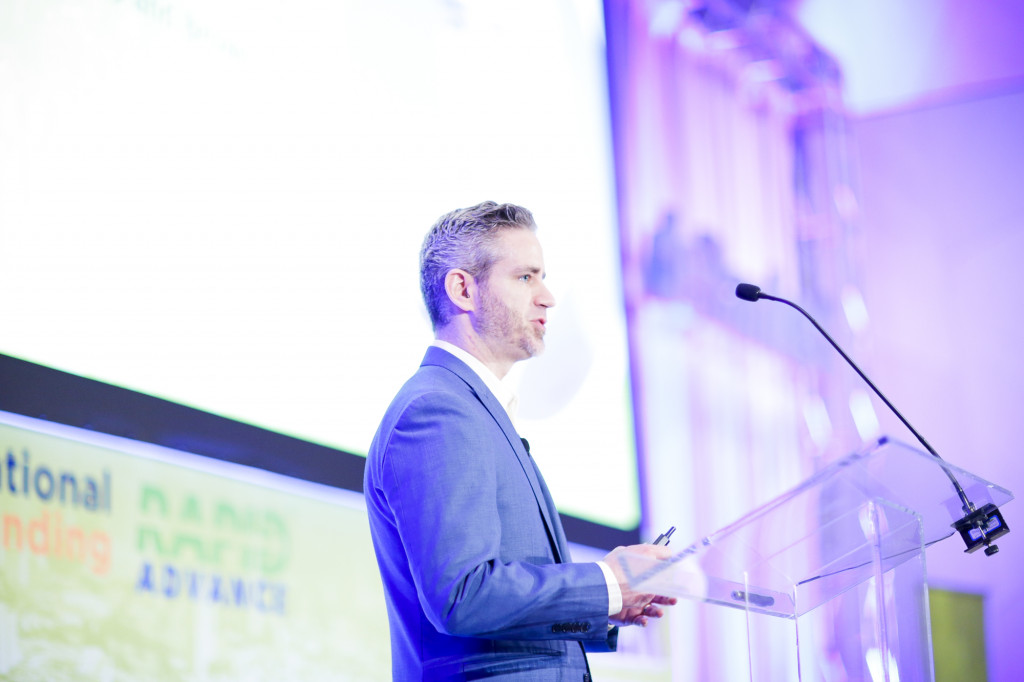
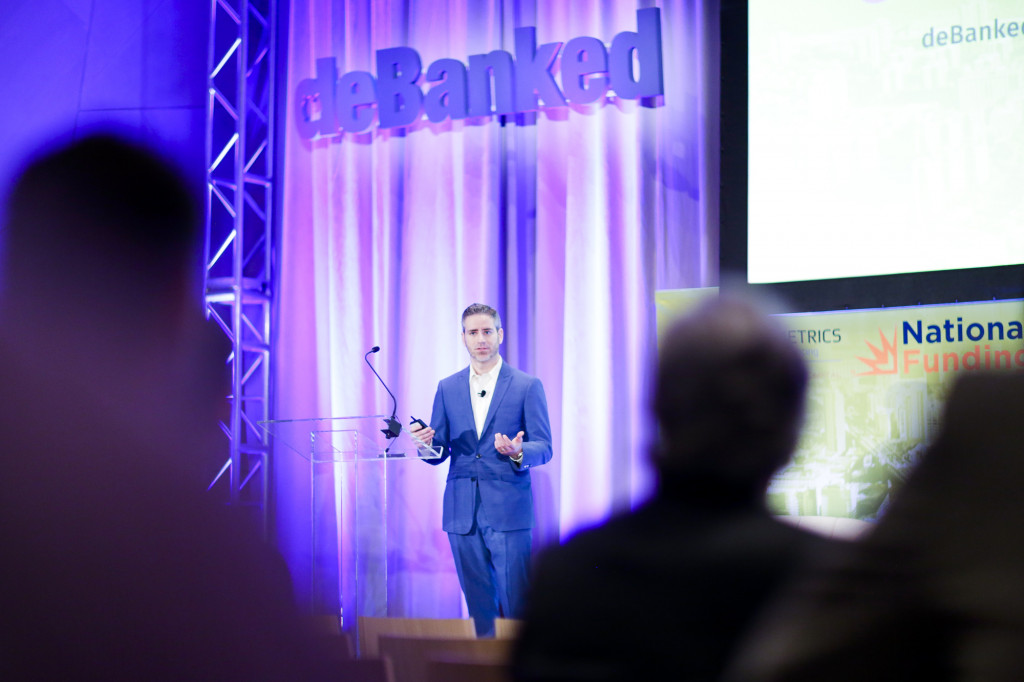
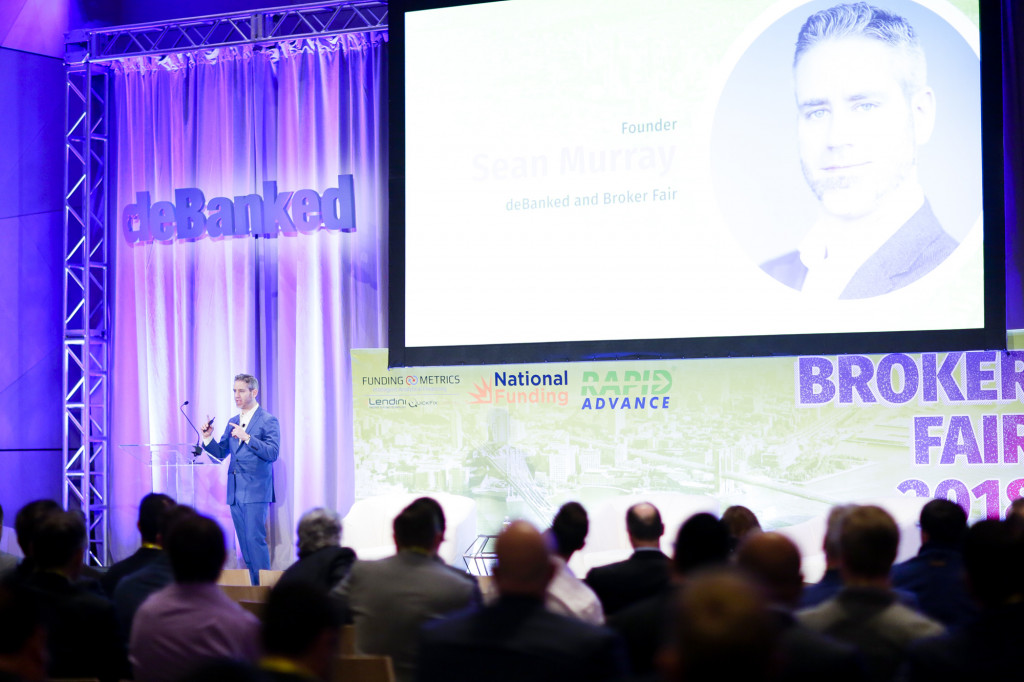
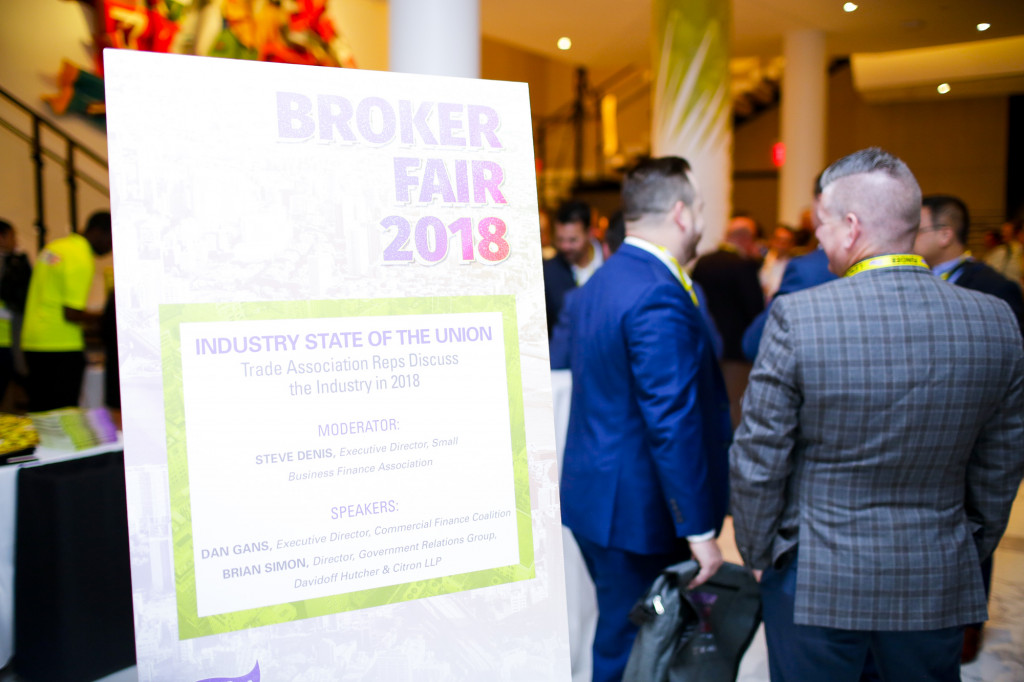
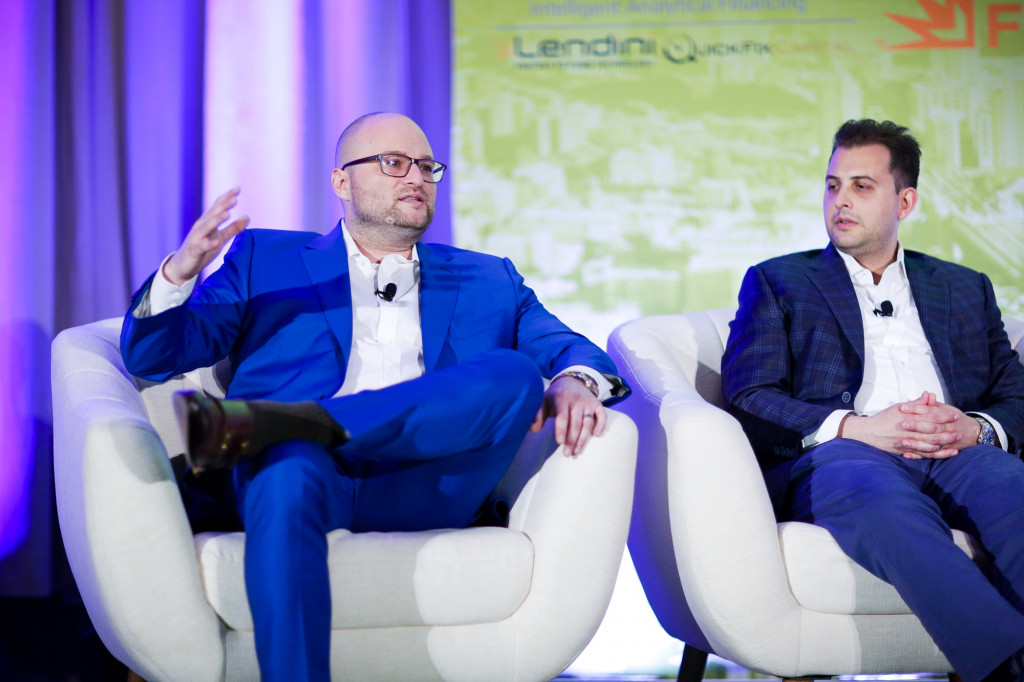
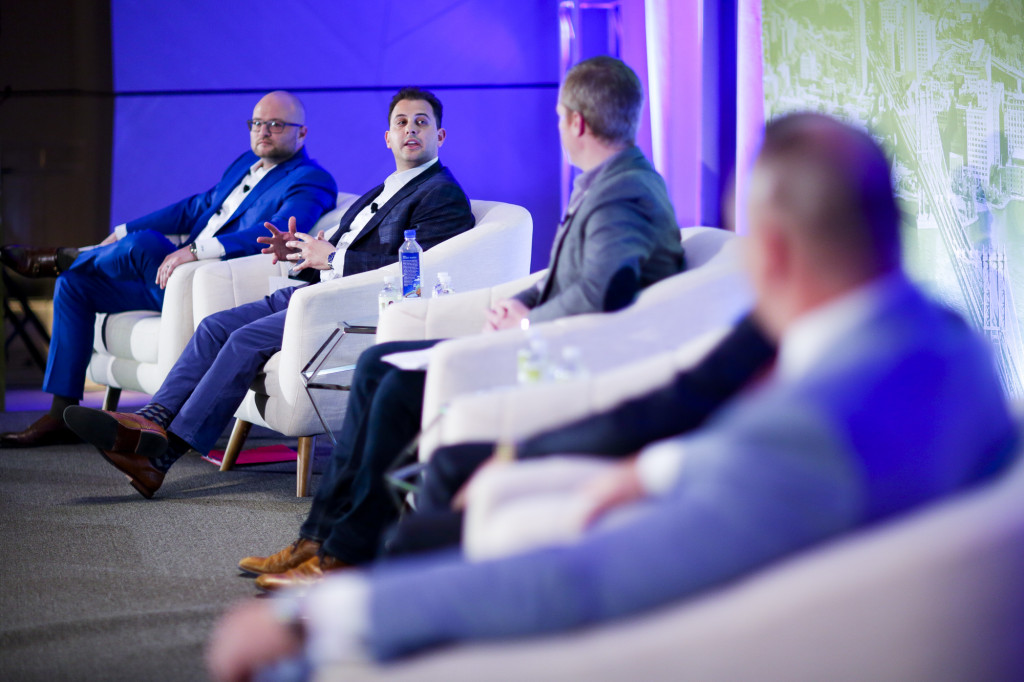
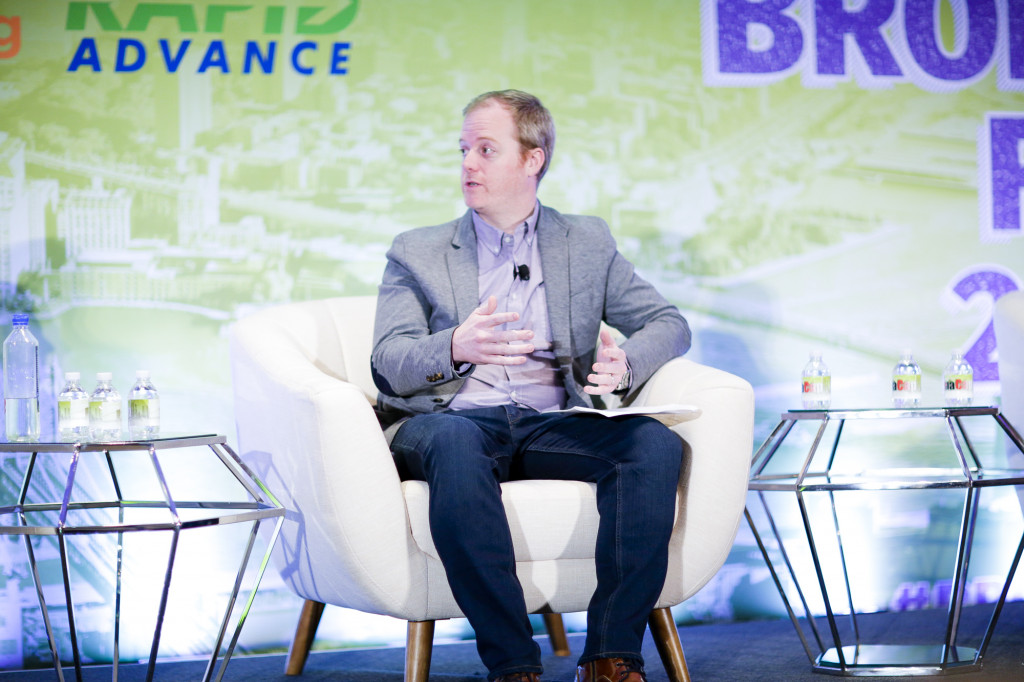
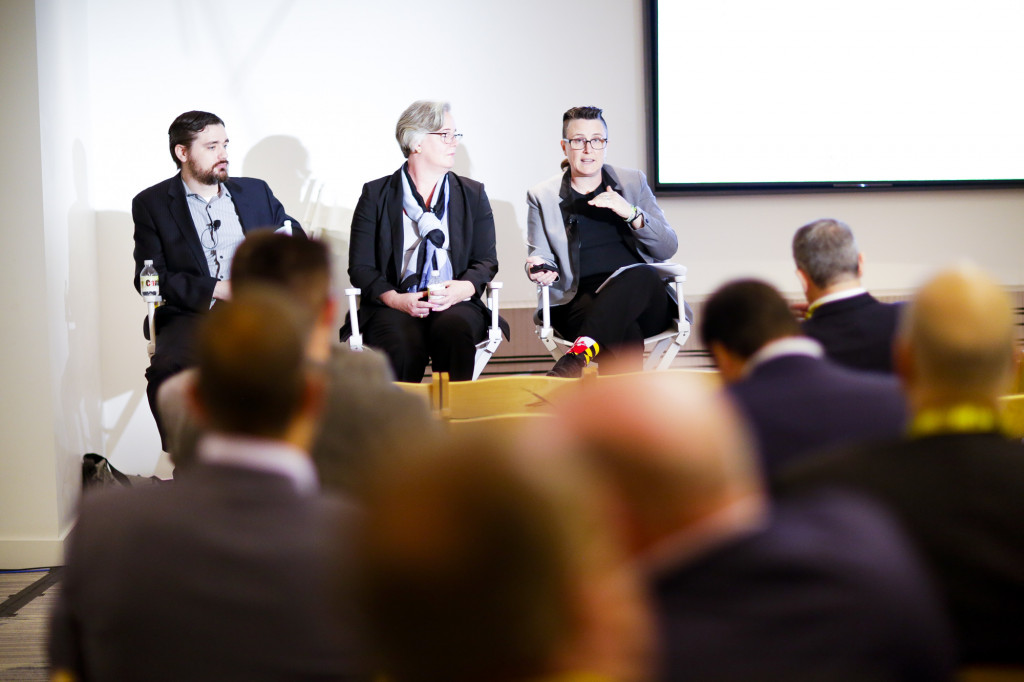
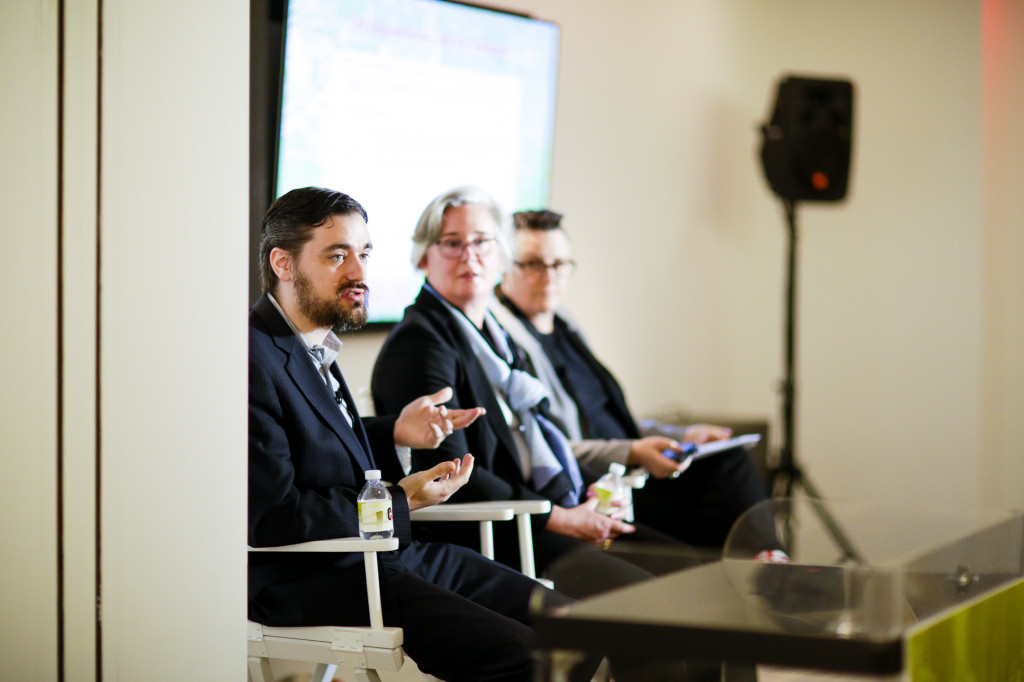
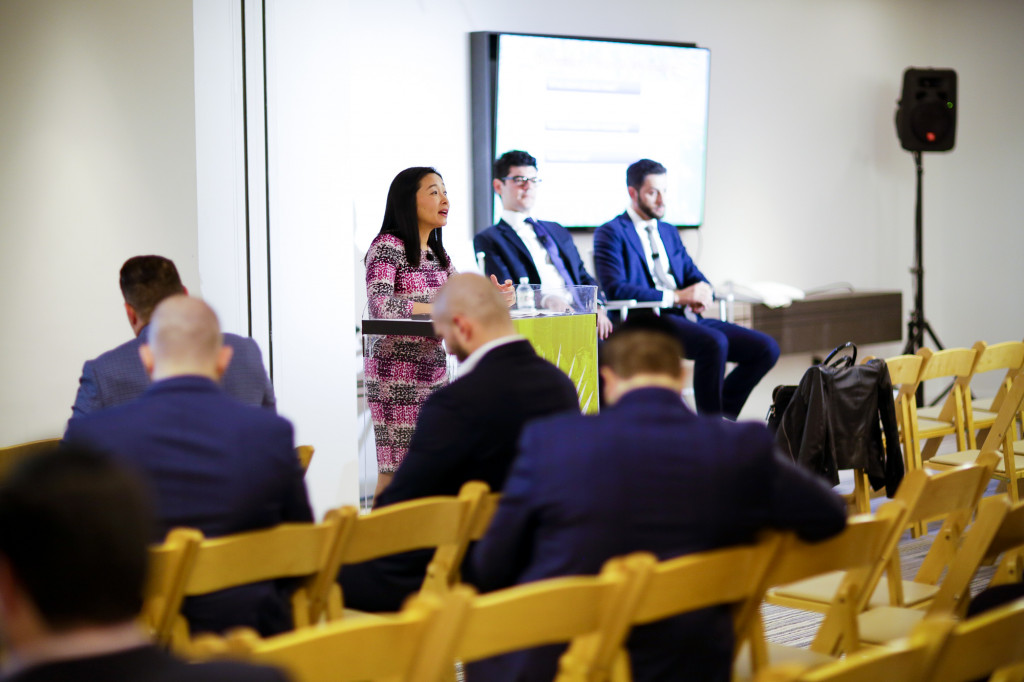
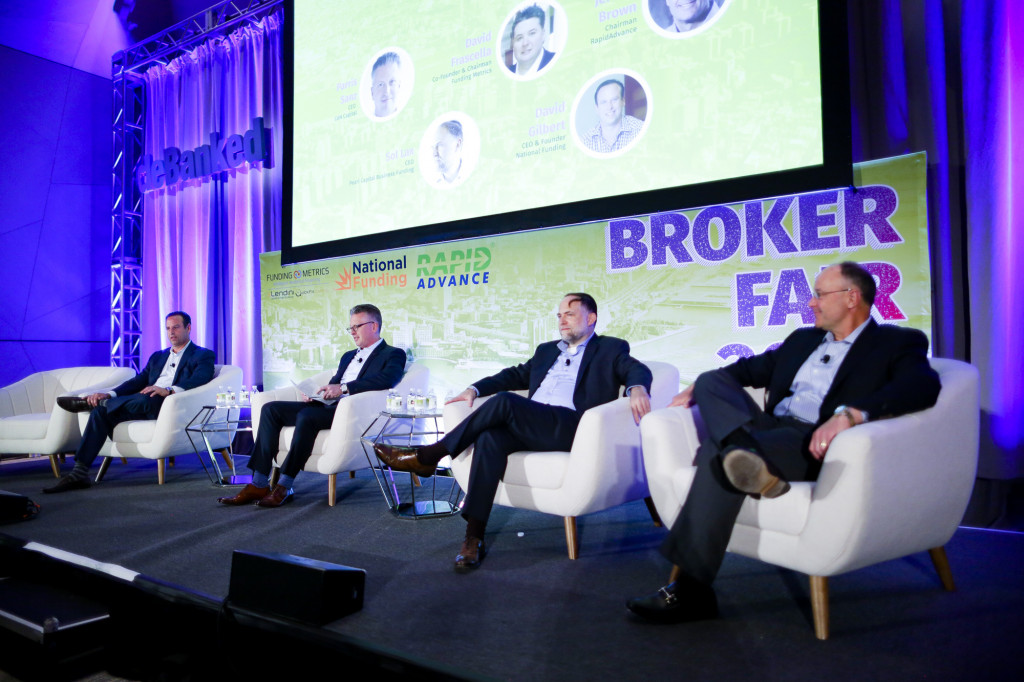
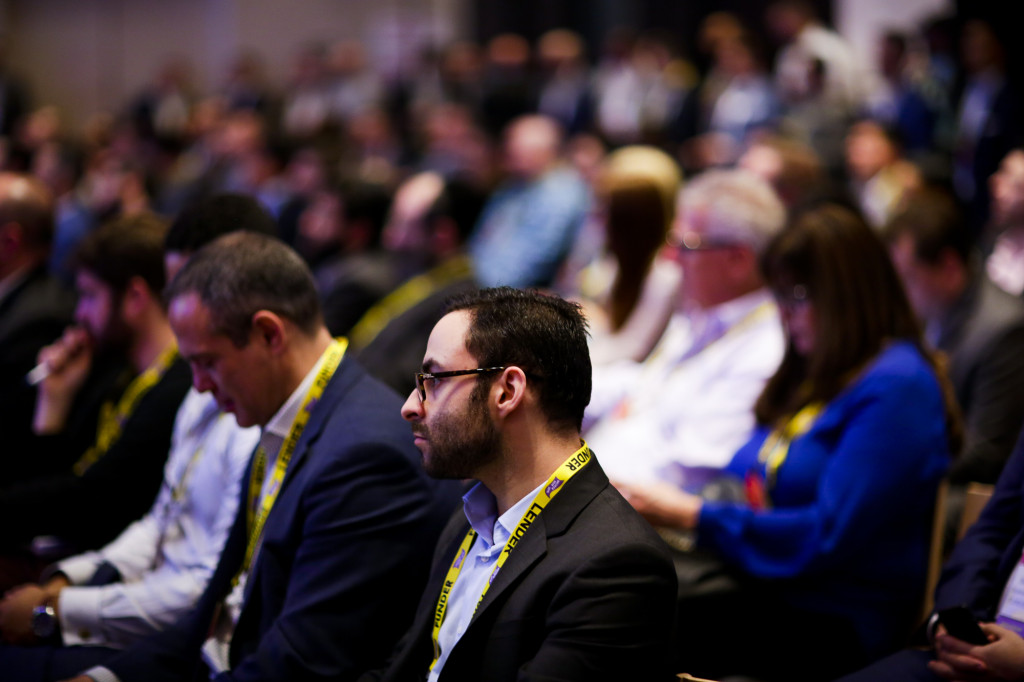
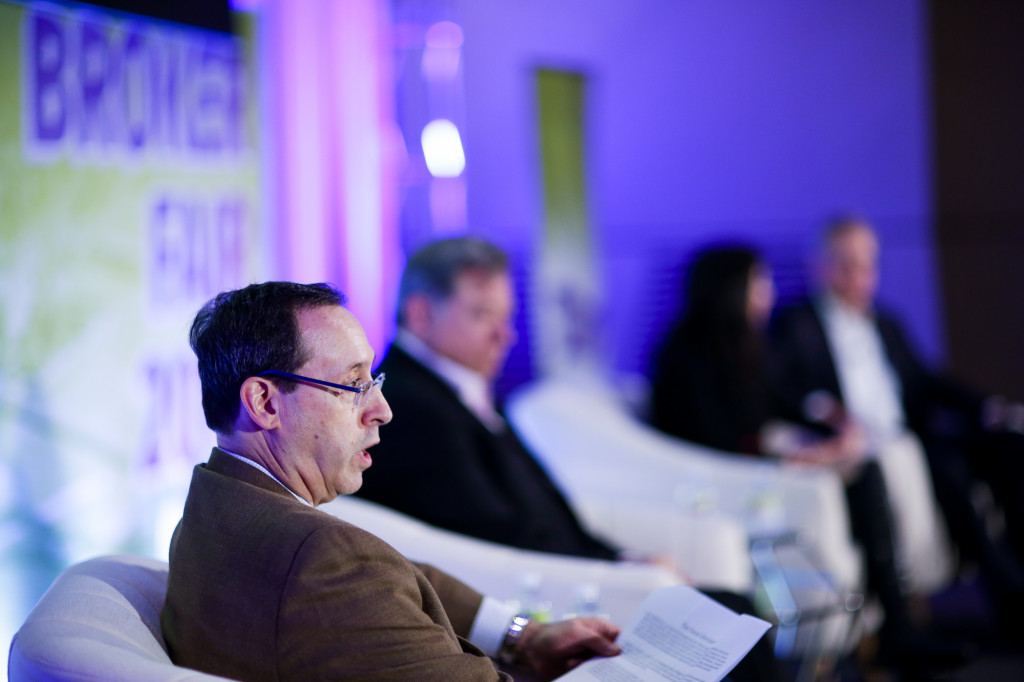
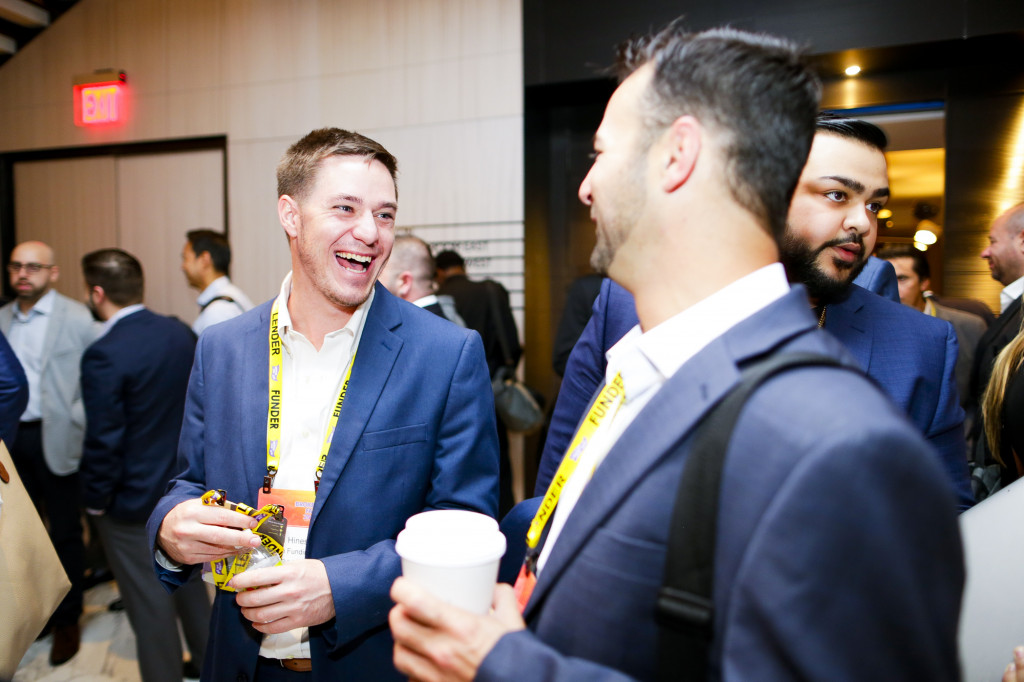
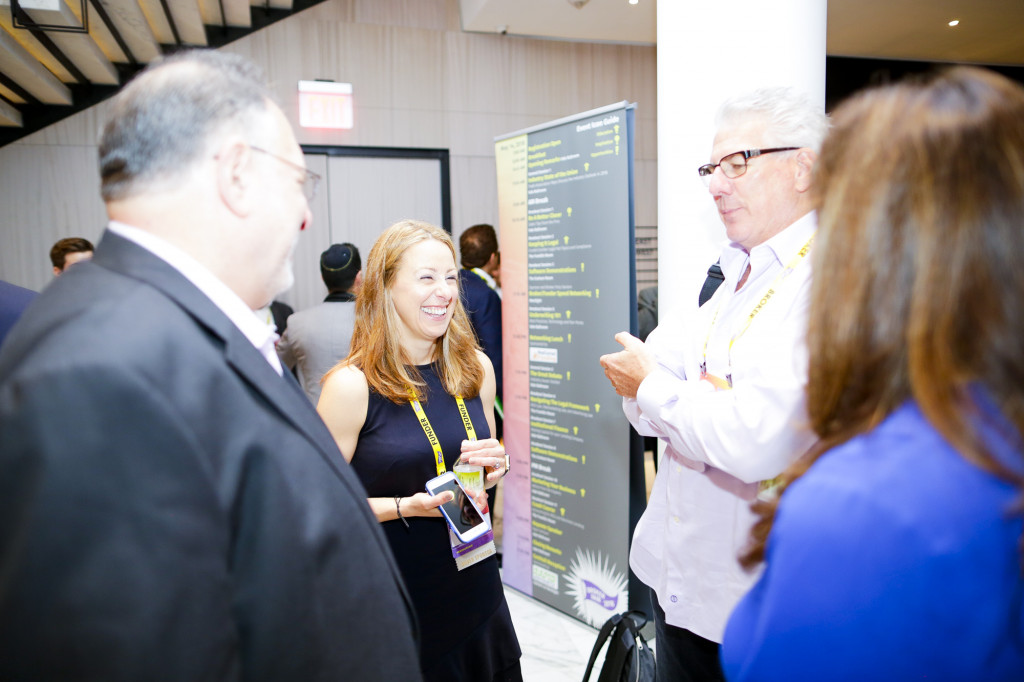
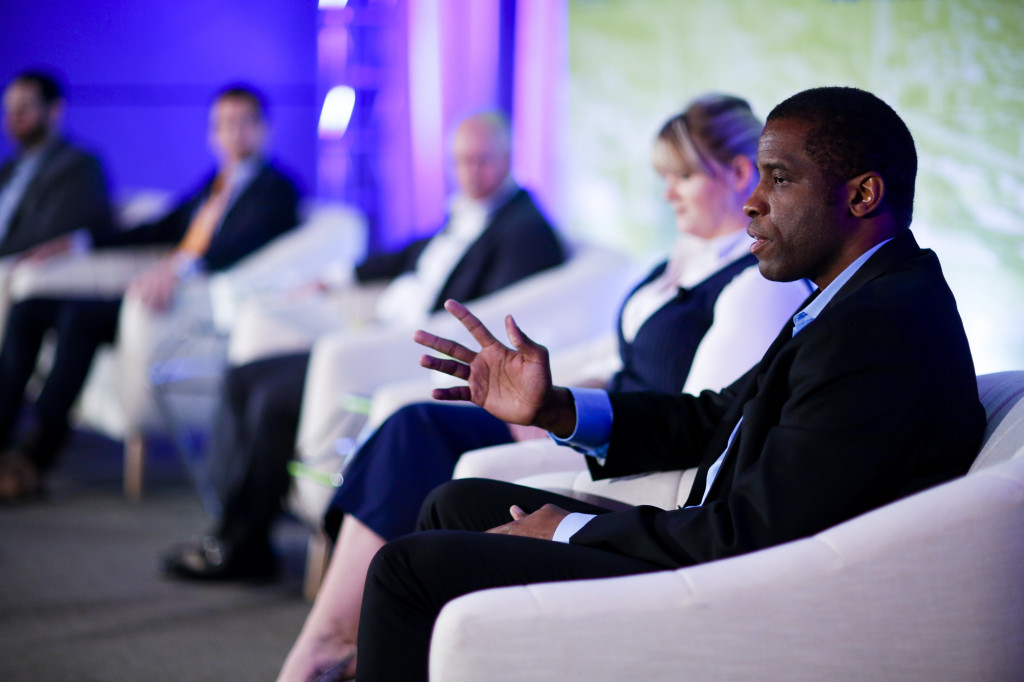
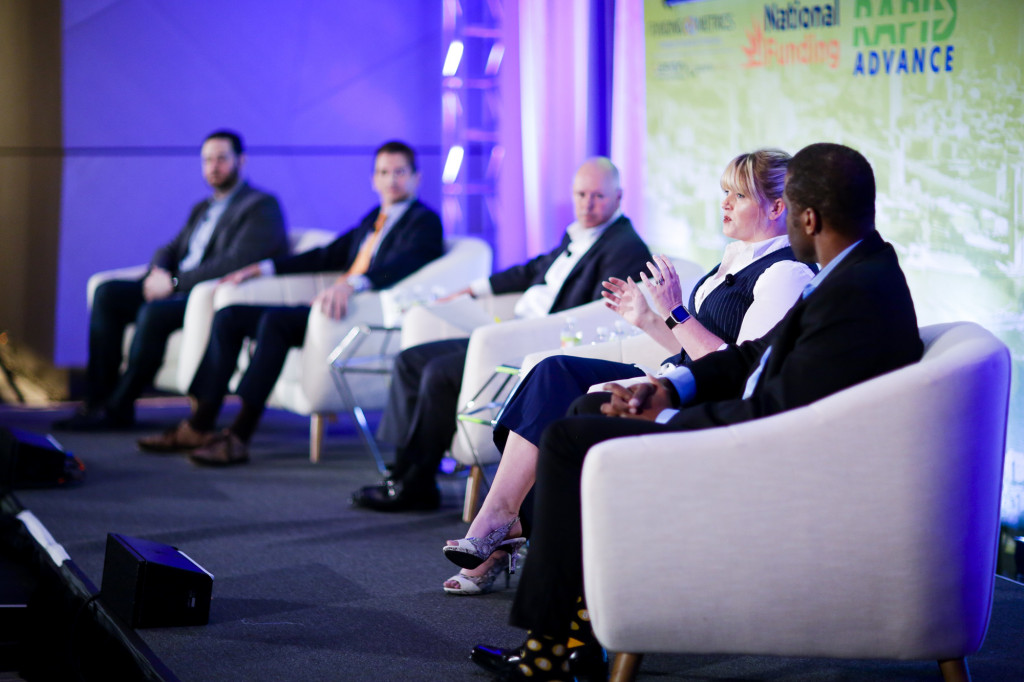
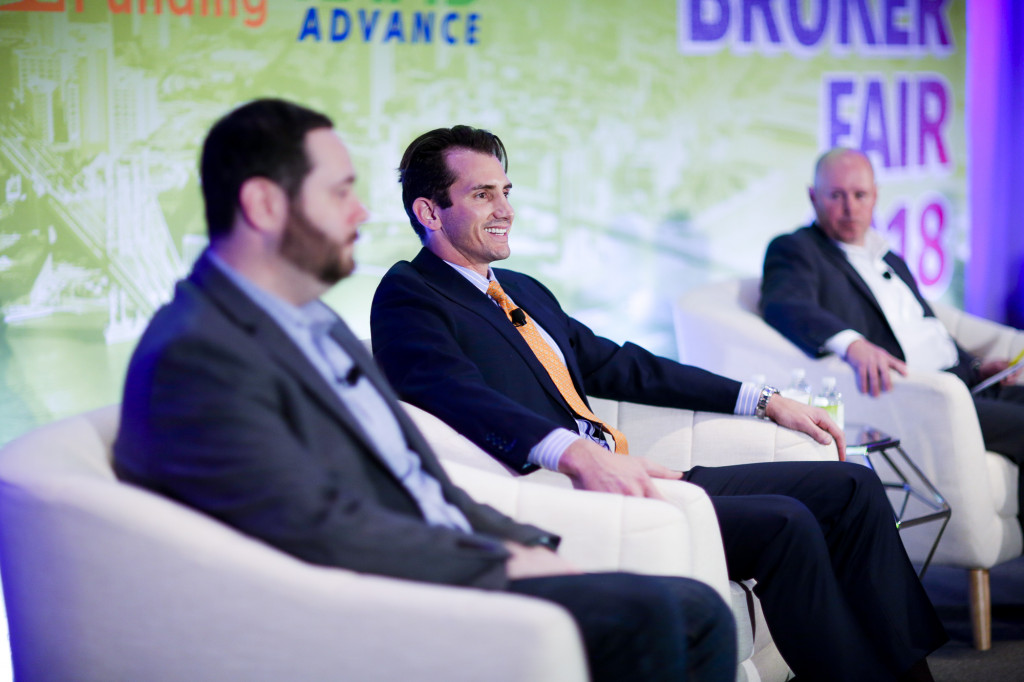
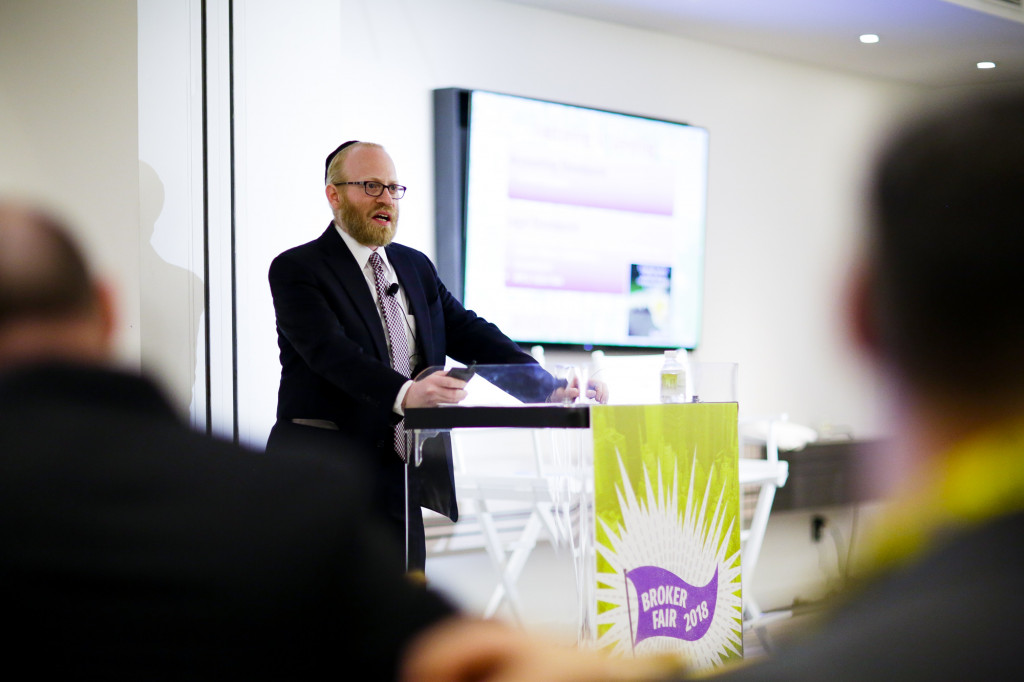
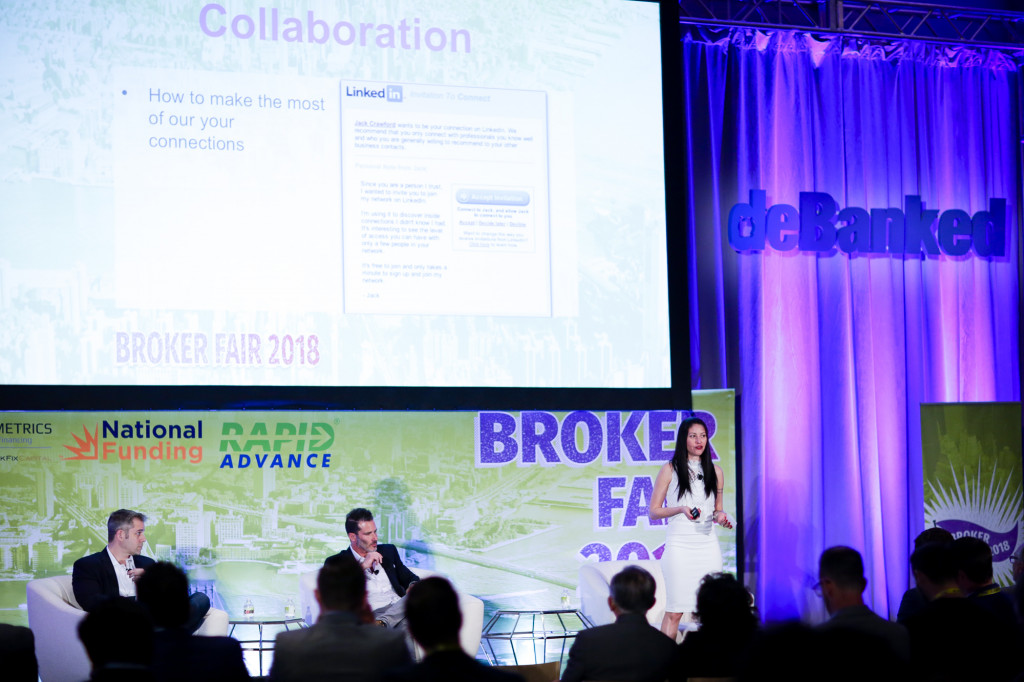
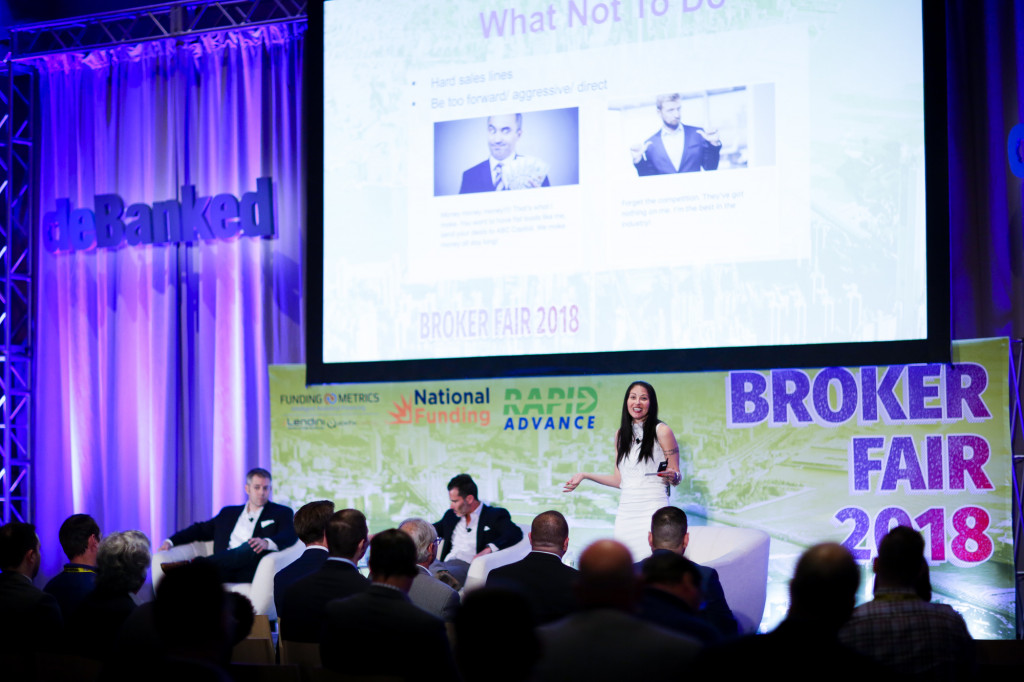
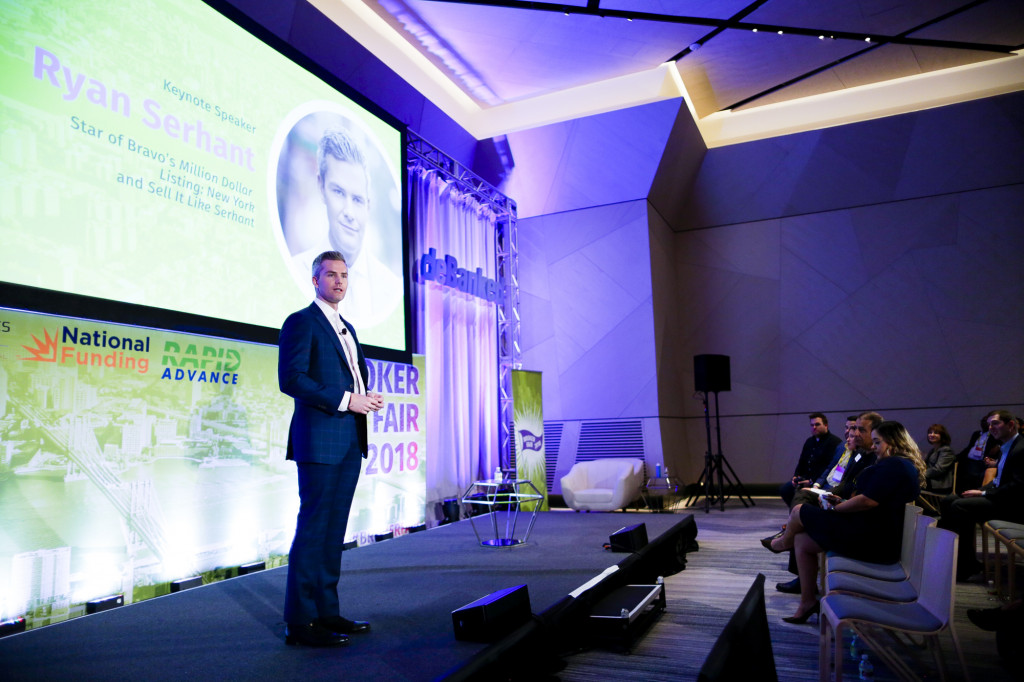
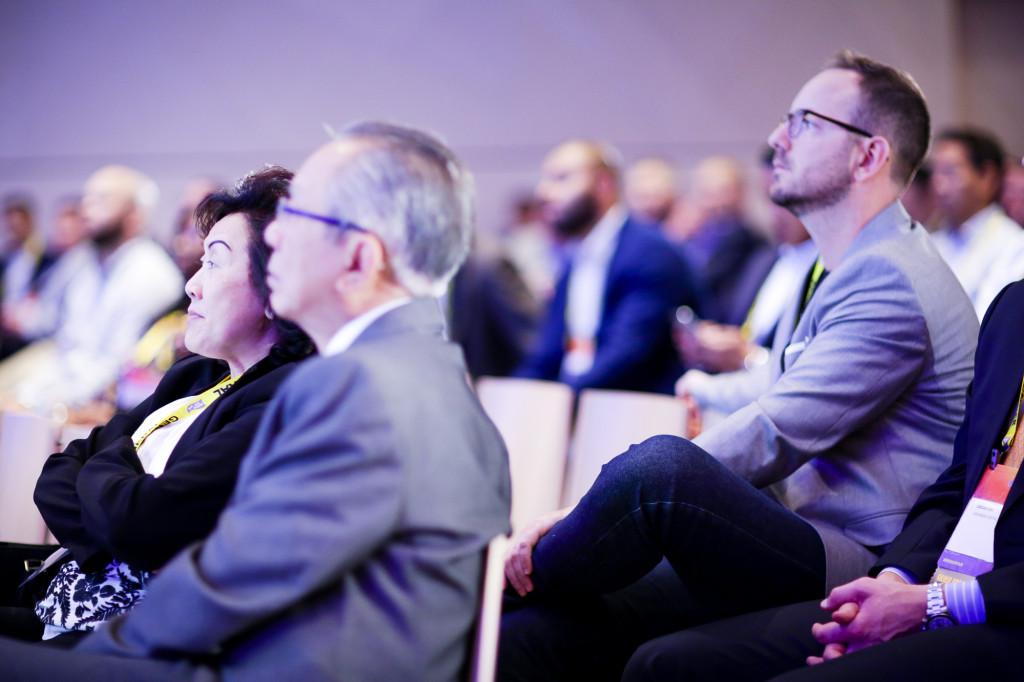
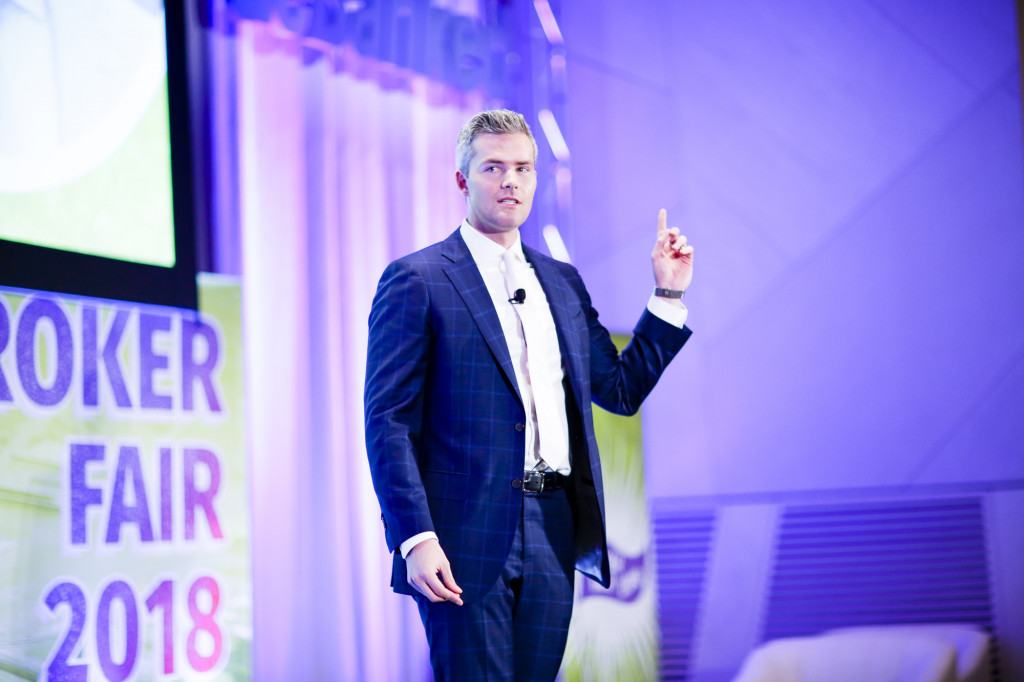
May 18, 2018Broker Fair 2018 was an amazing day of inspiration, education, and opportunities. We’ve posted some of our photo footage below:
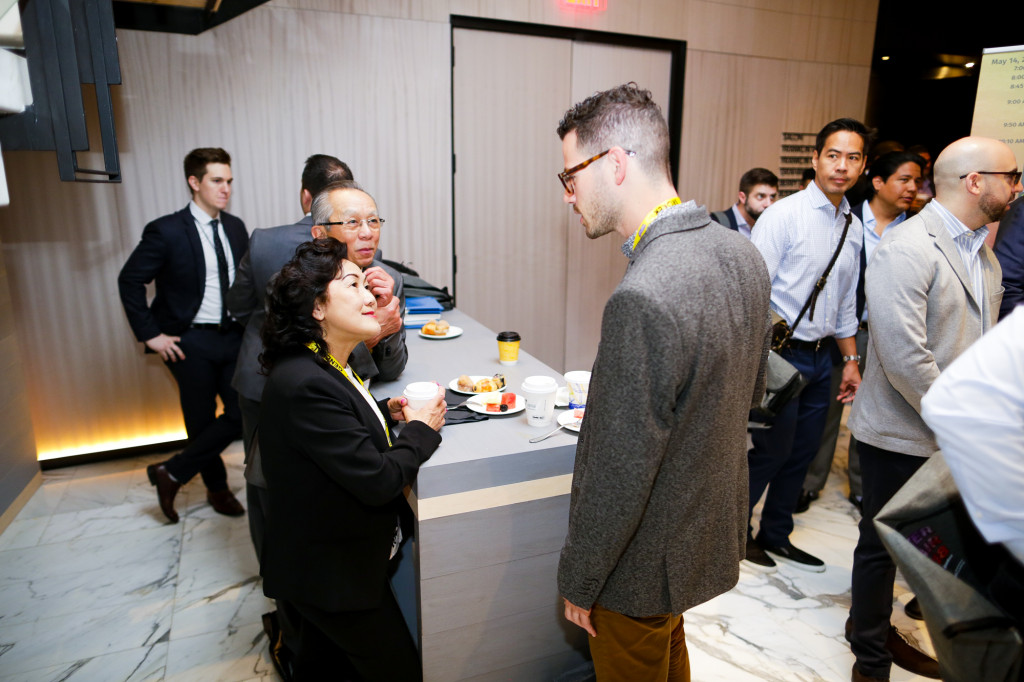
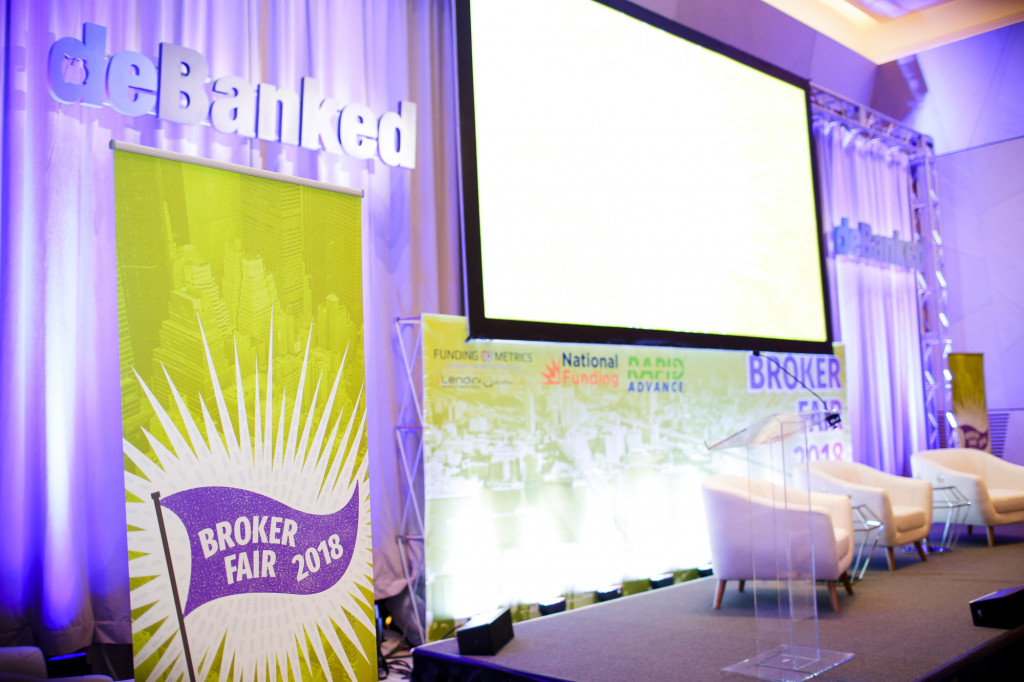
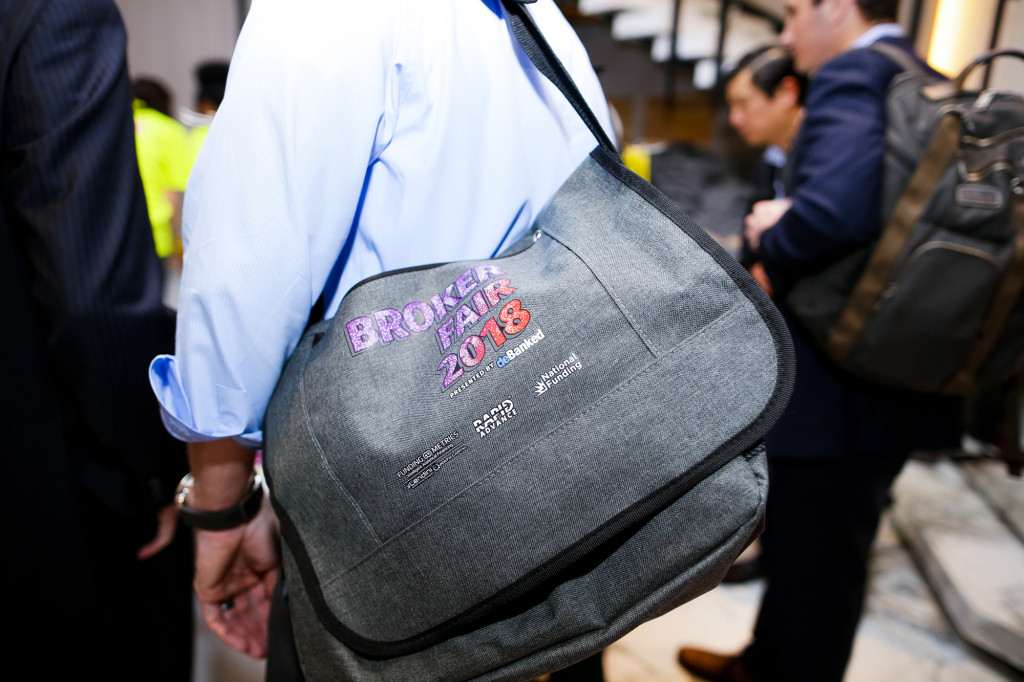
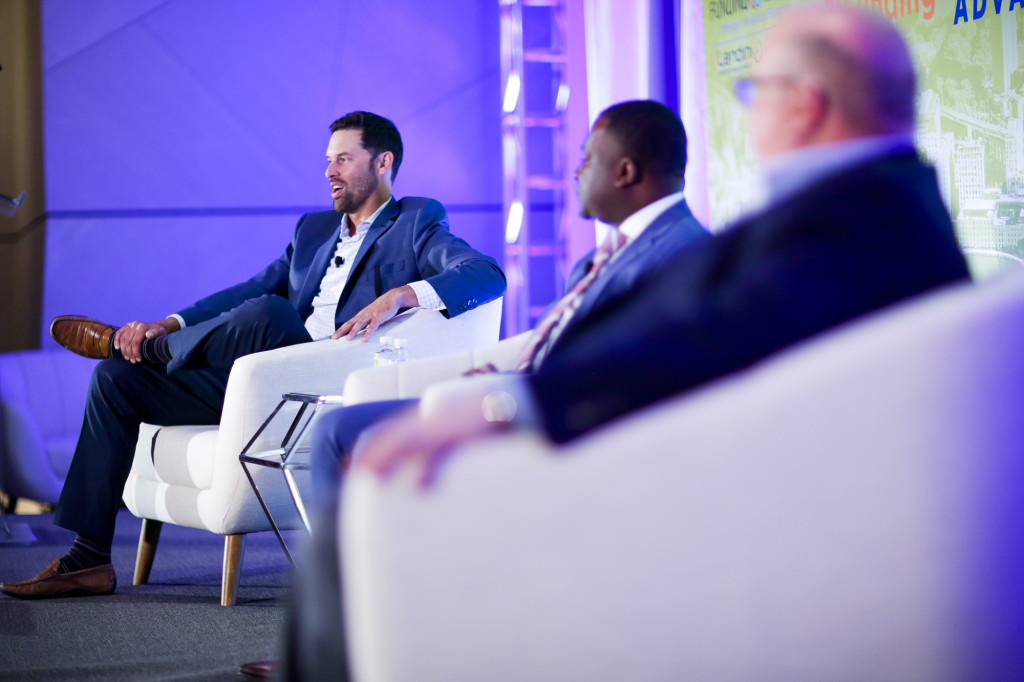
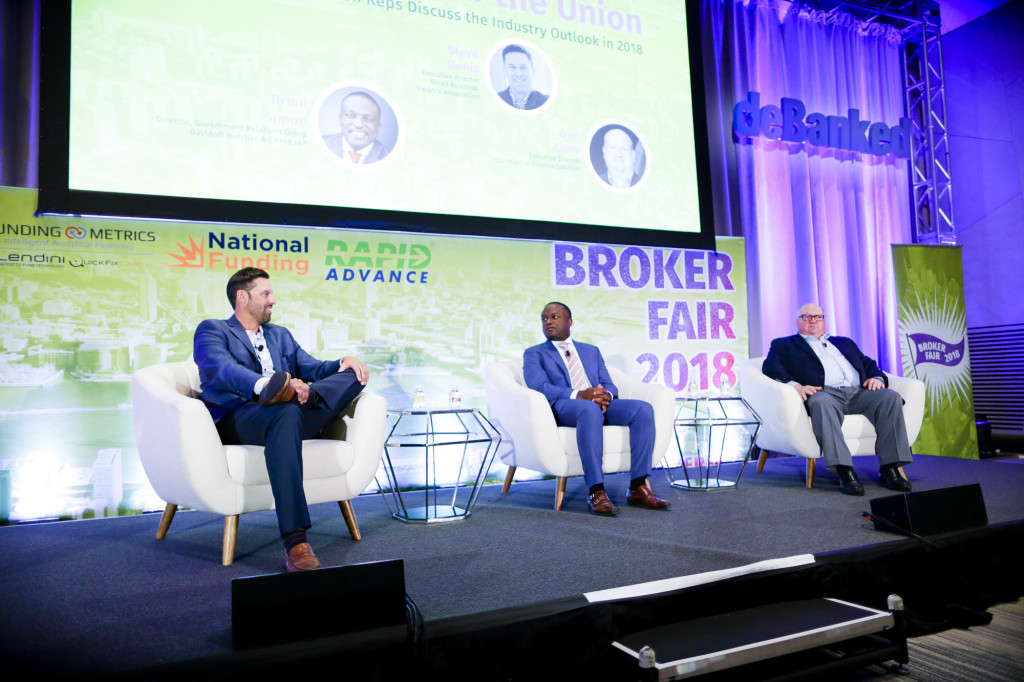
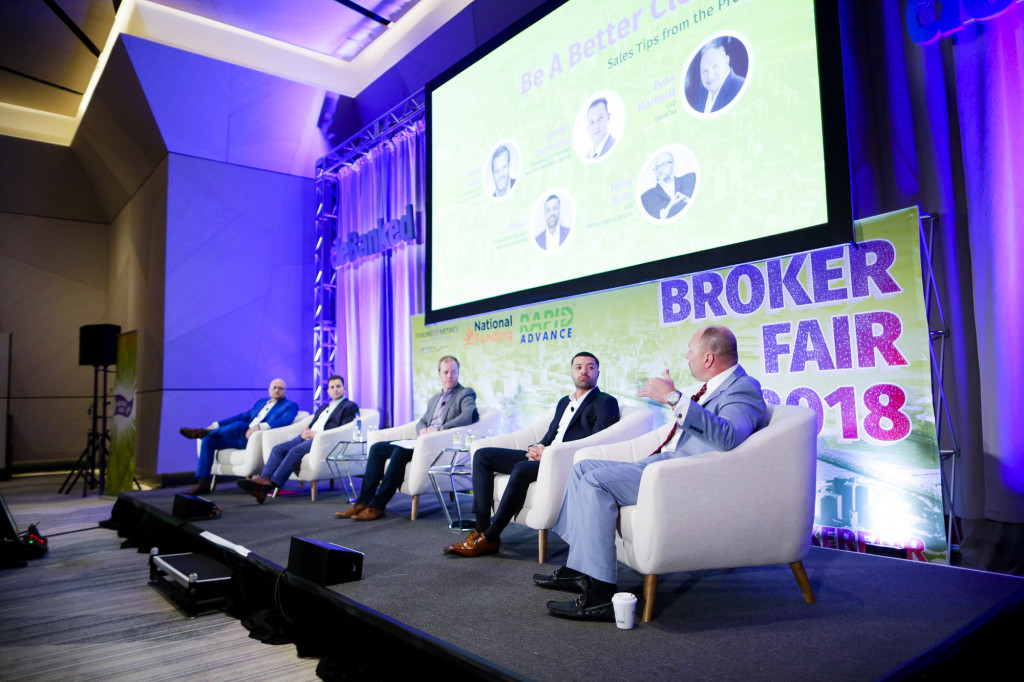
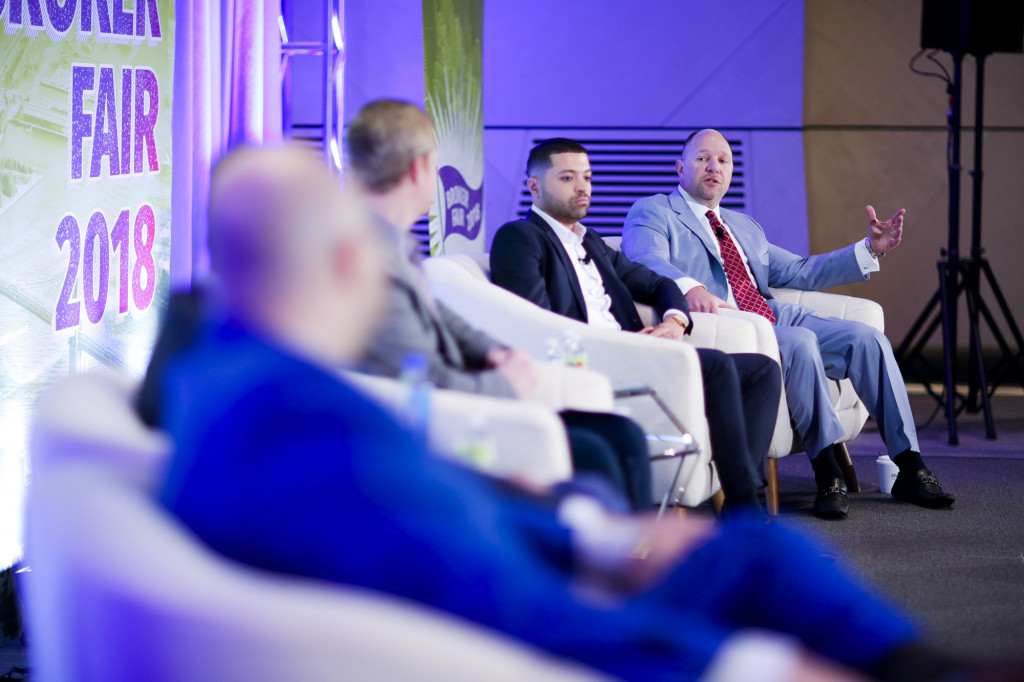
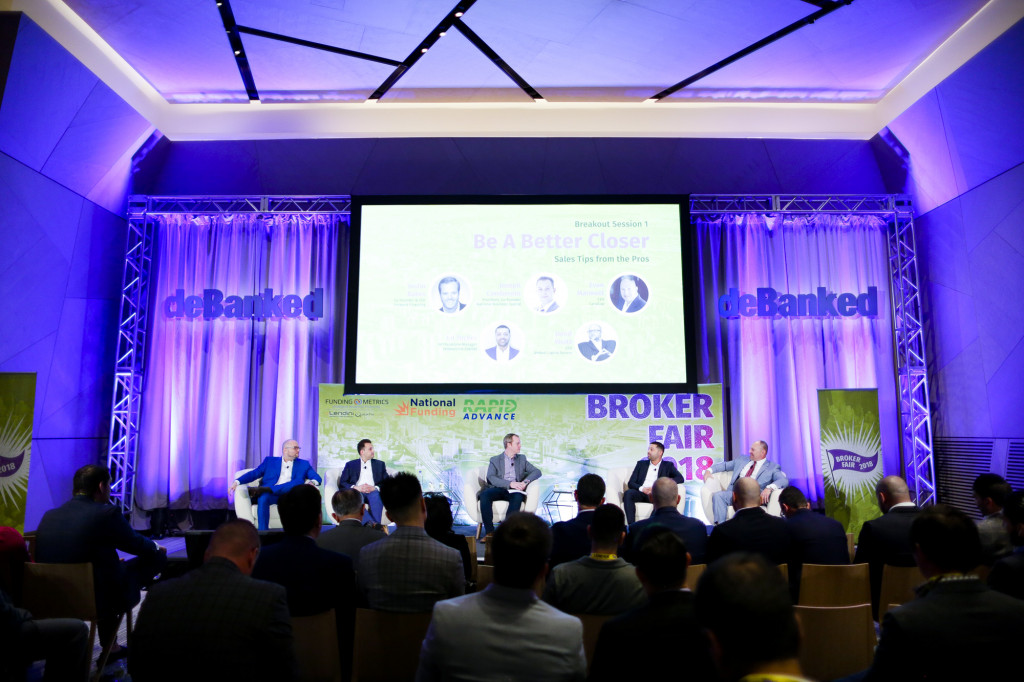
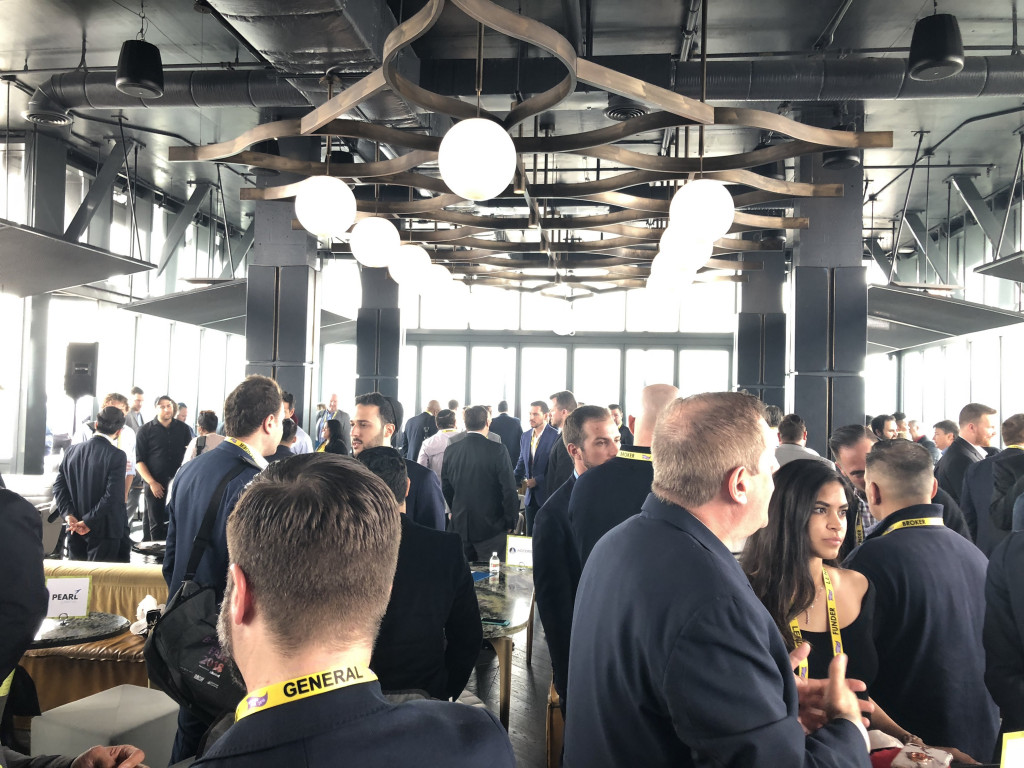
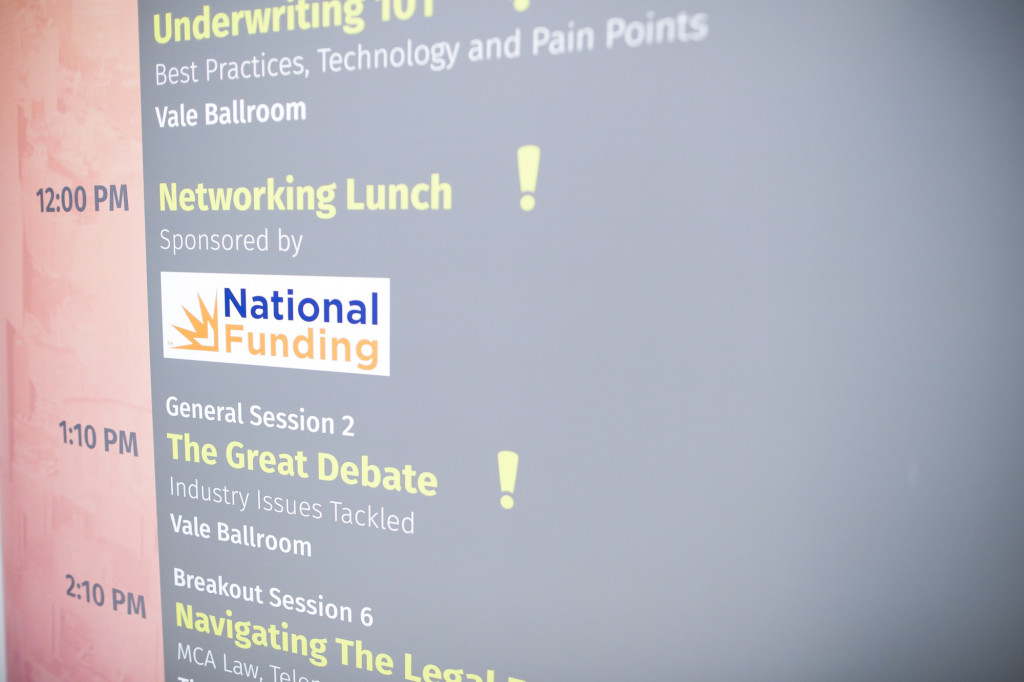
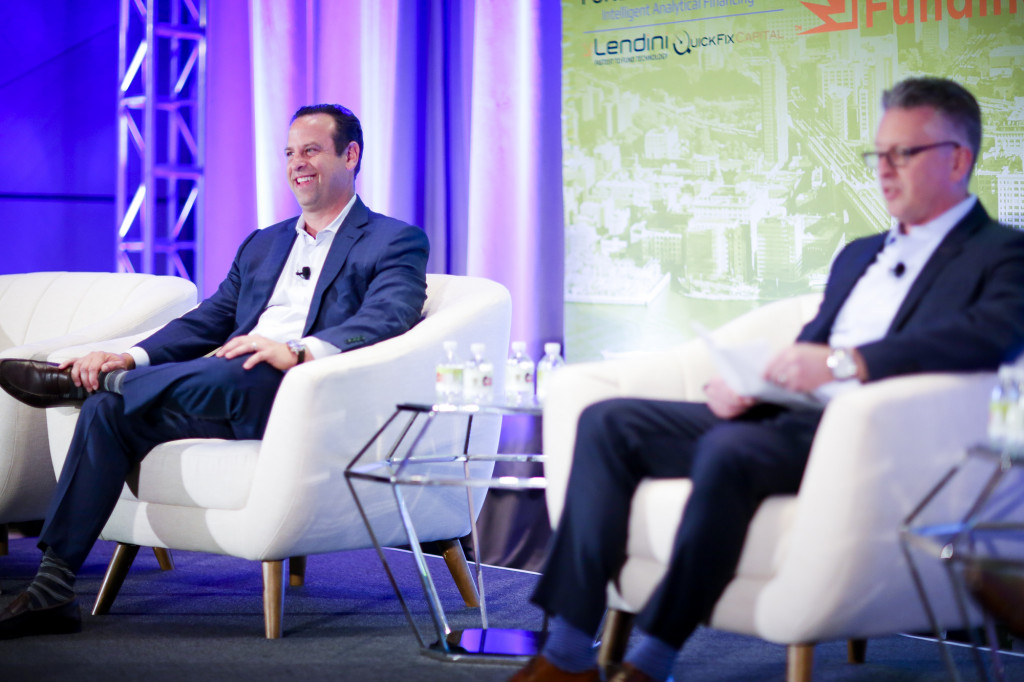
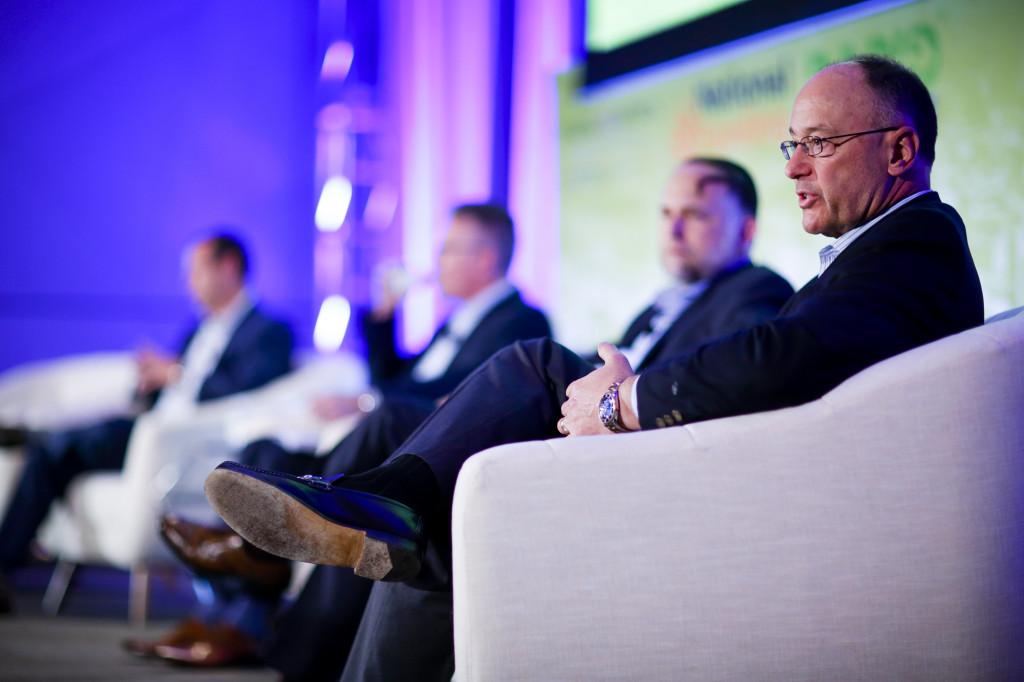
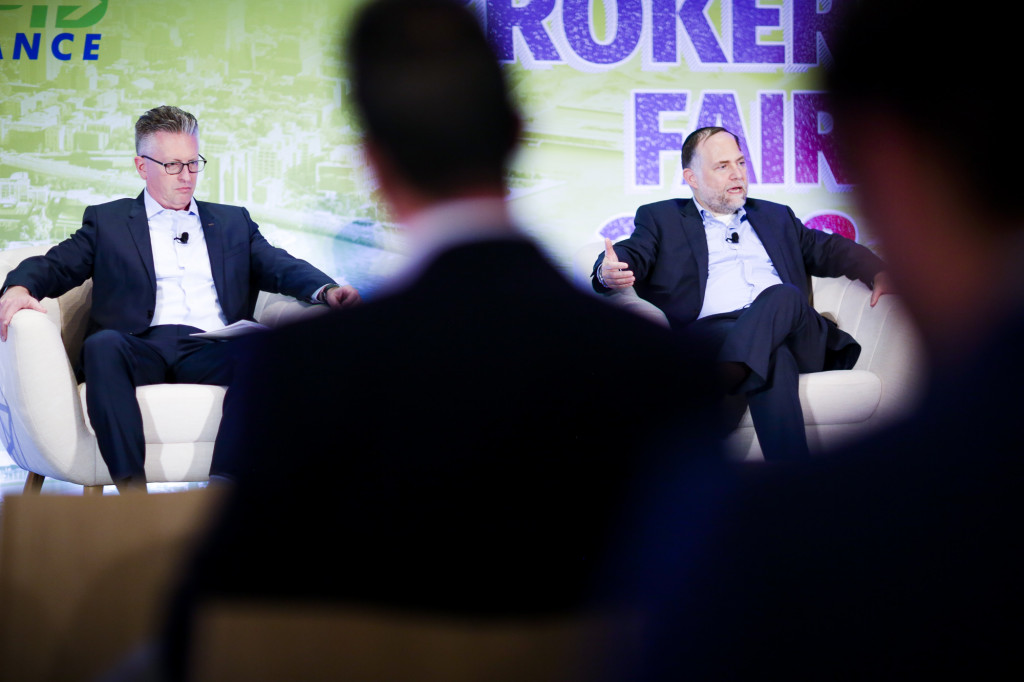
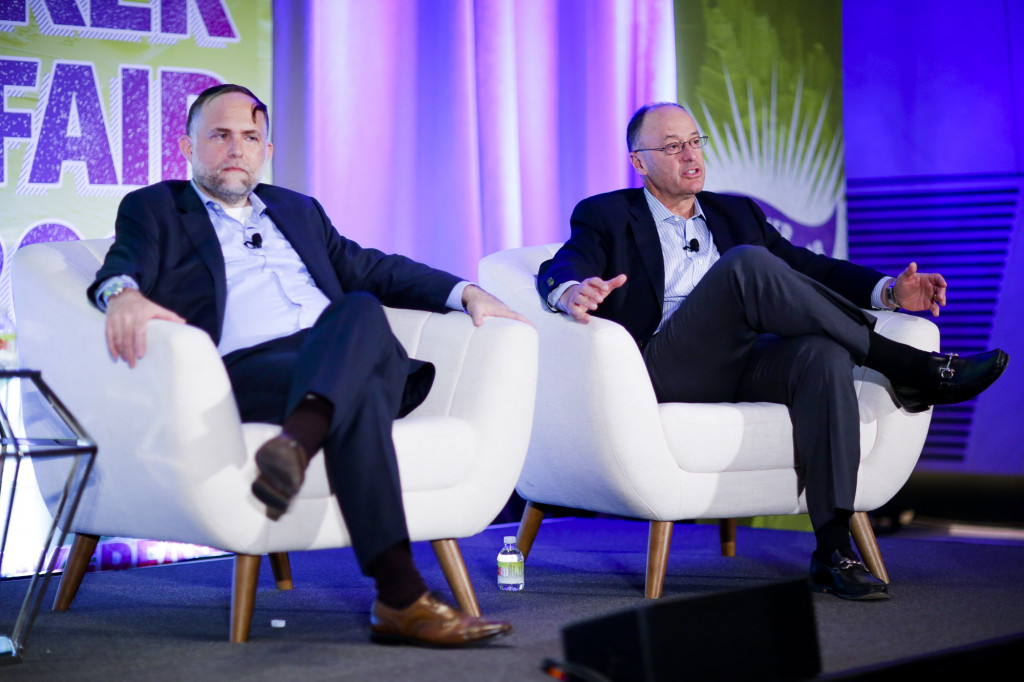
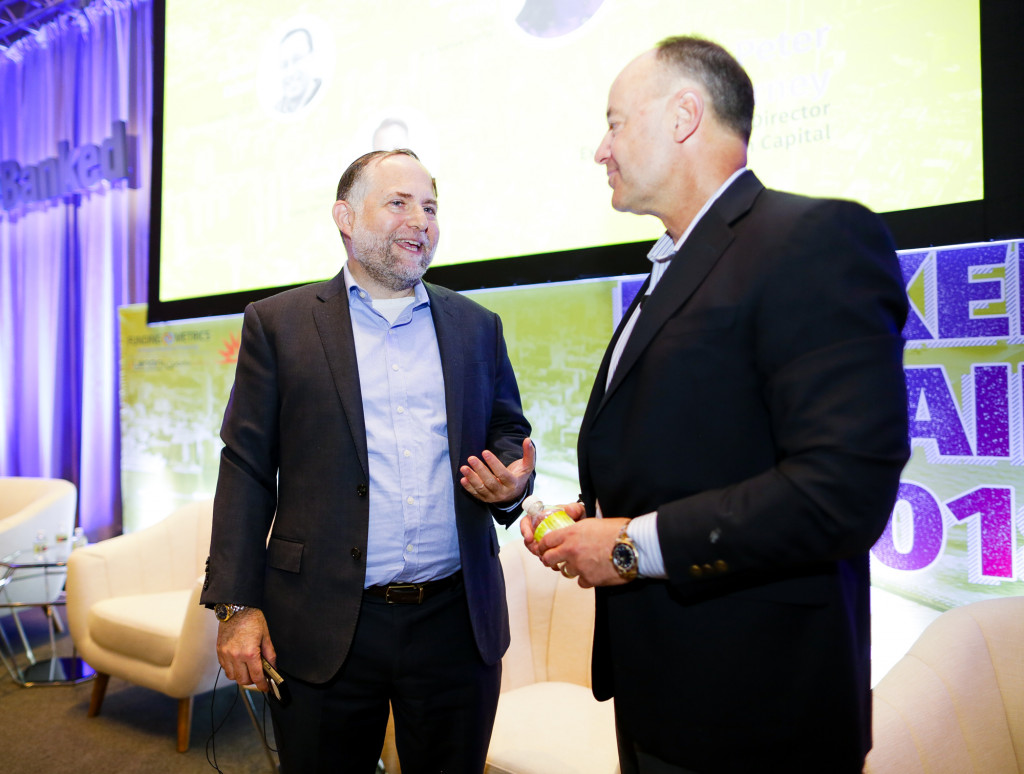
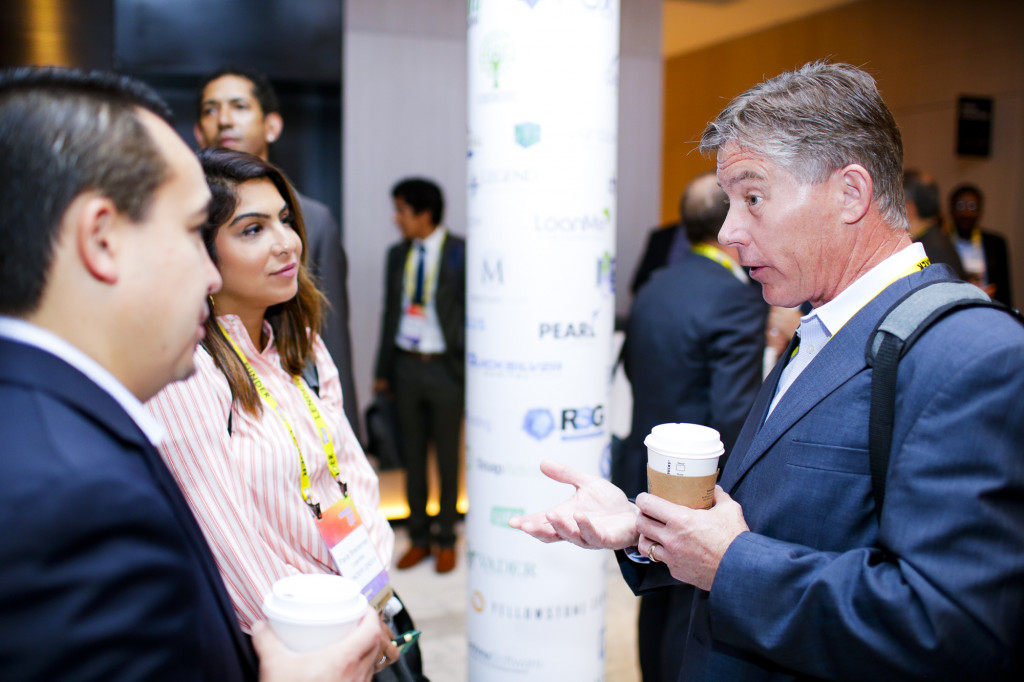
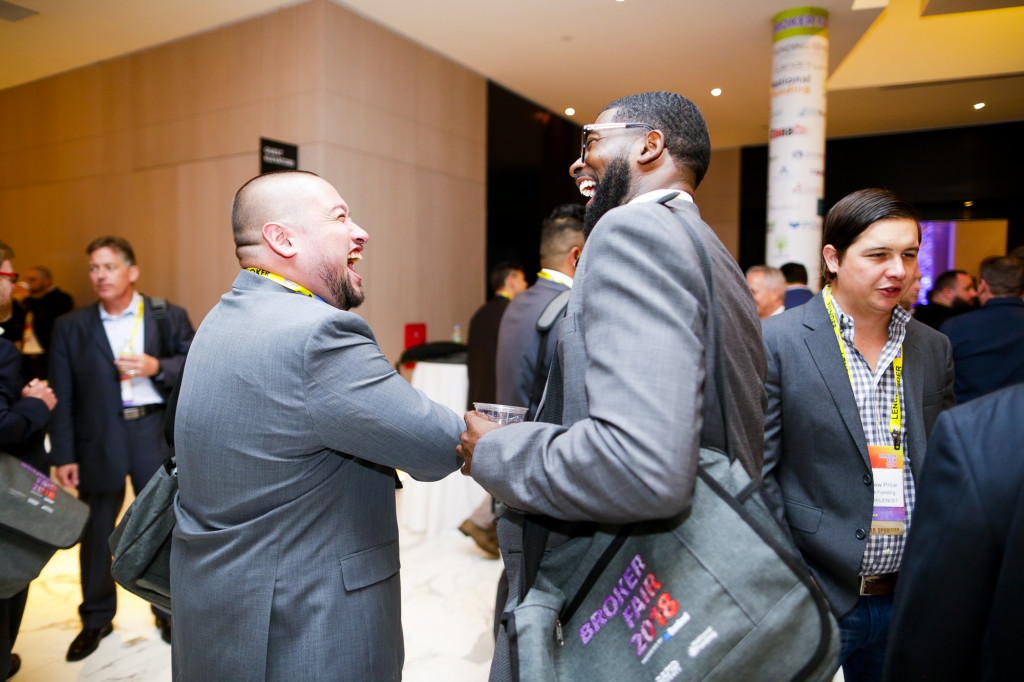
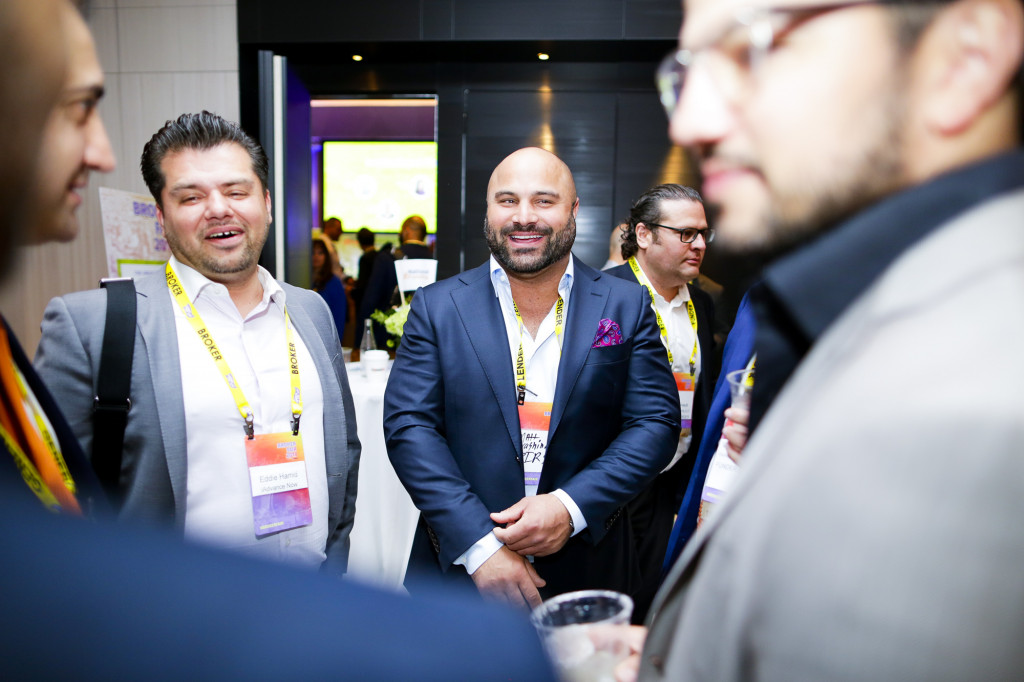
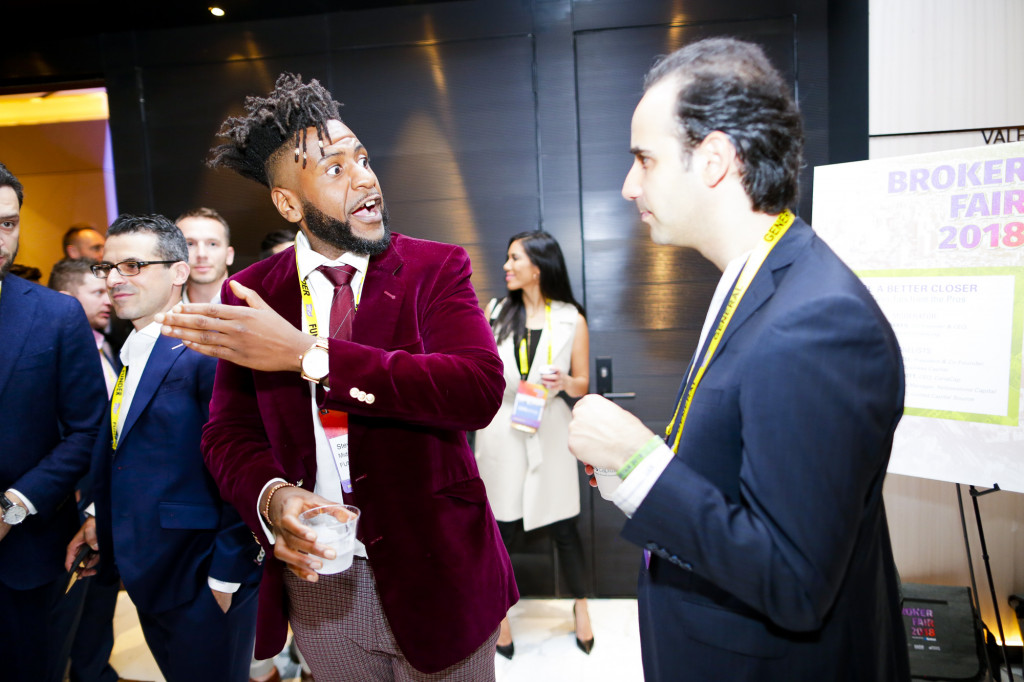
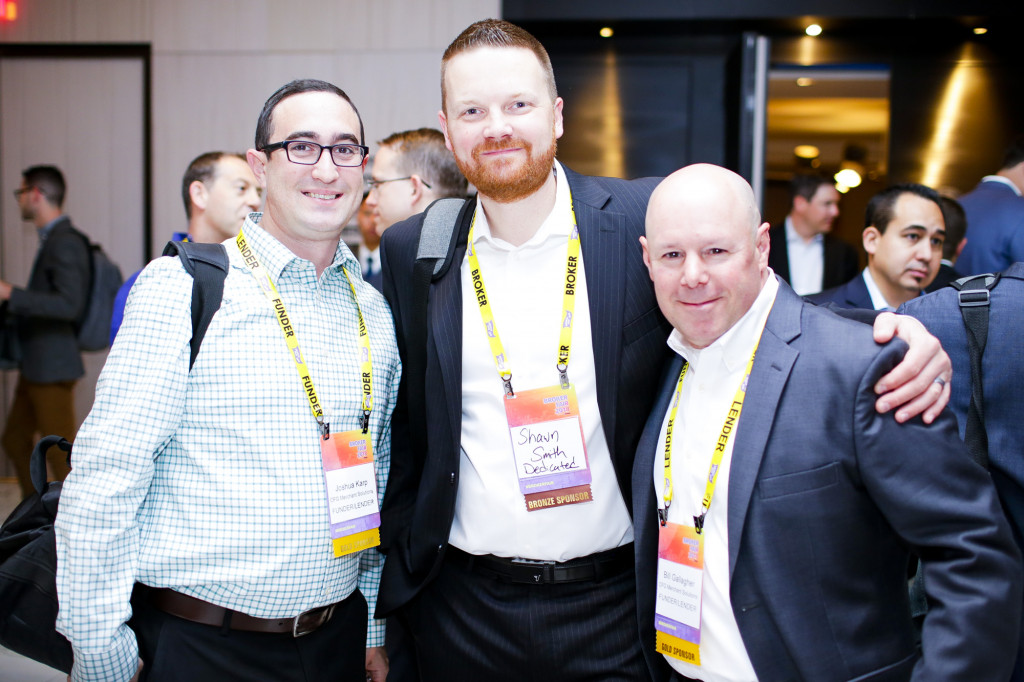
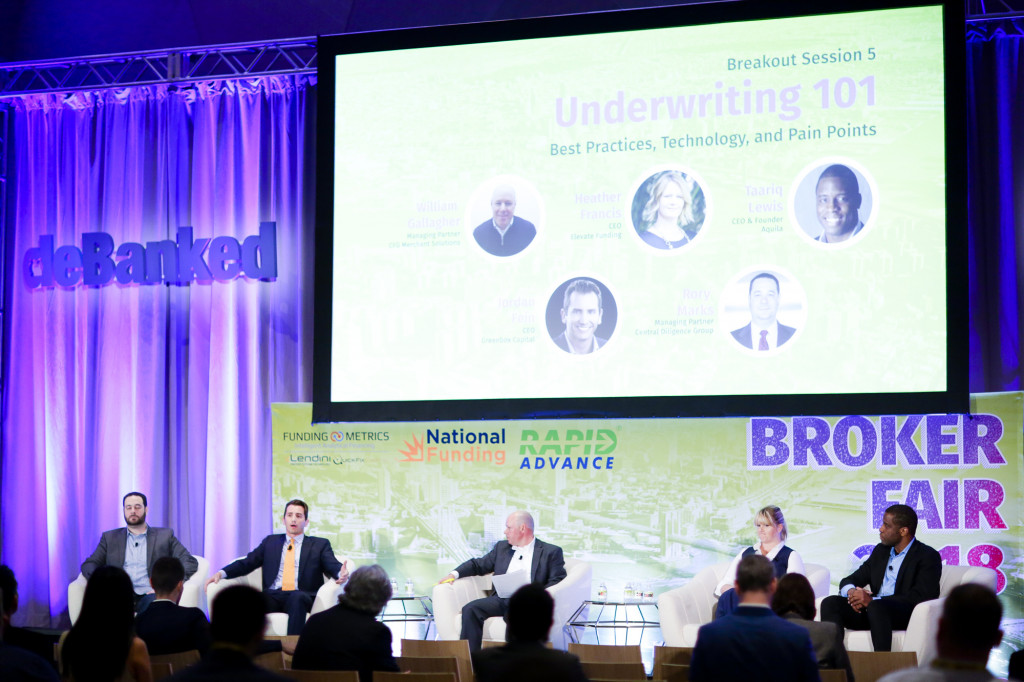
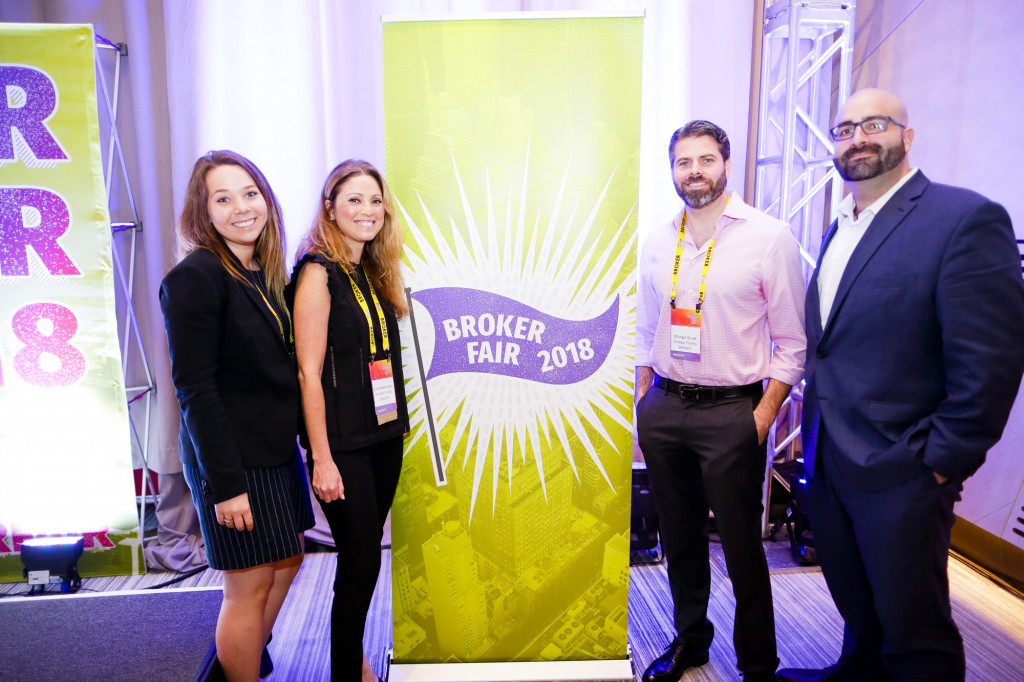
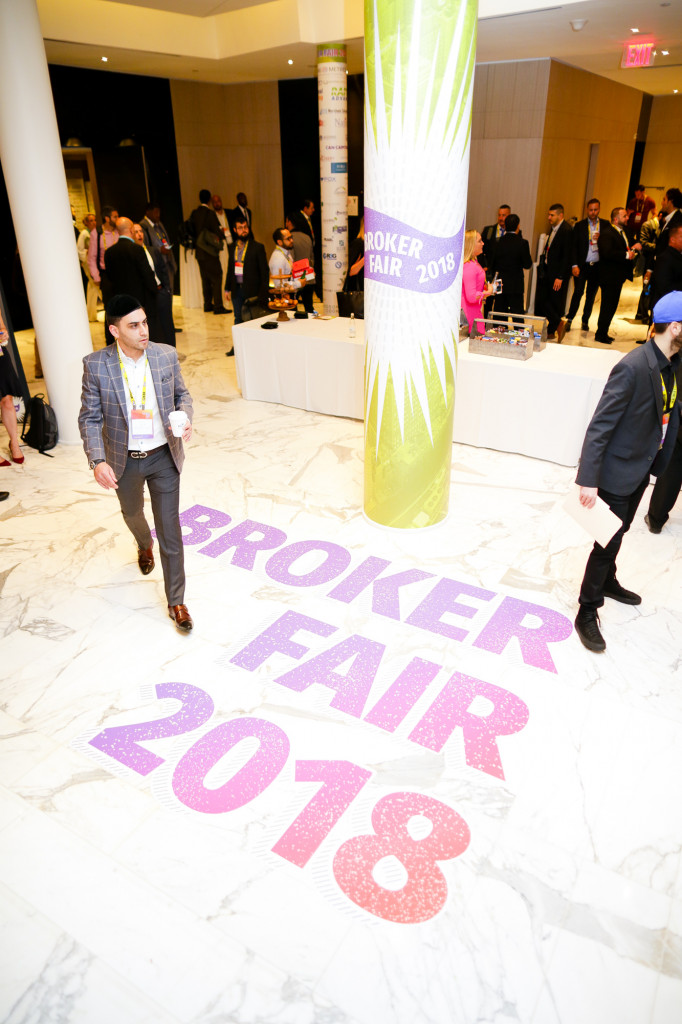
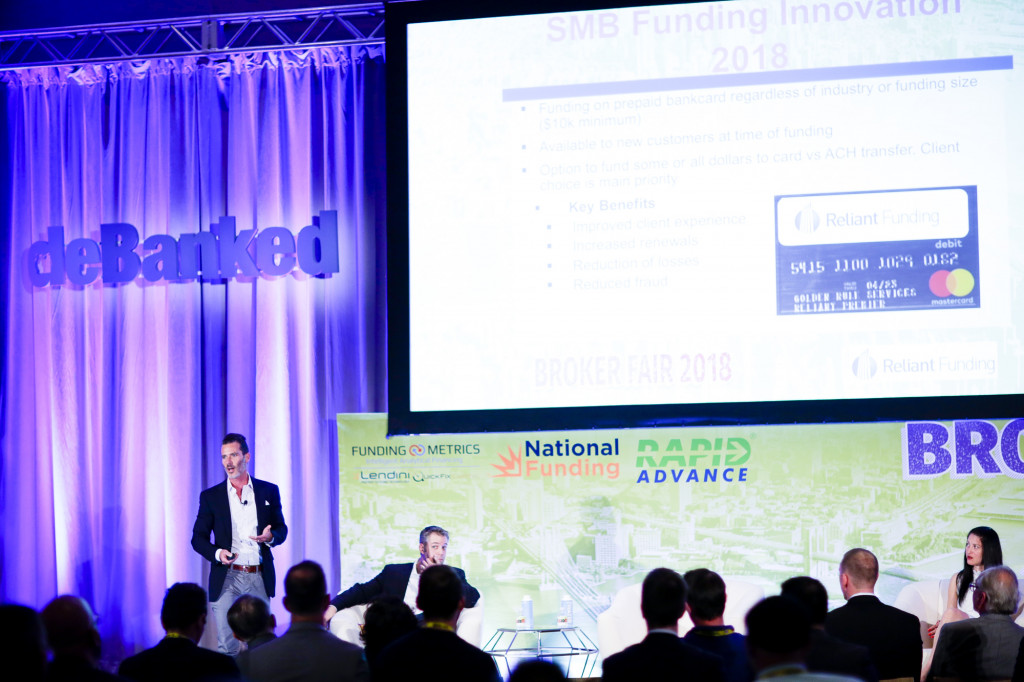
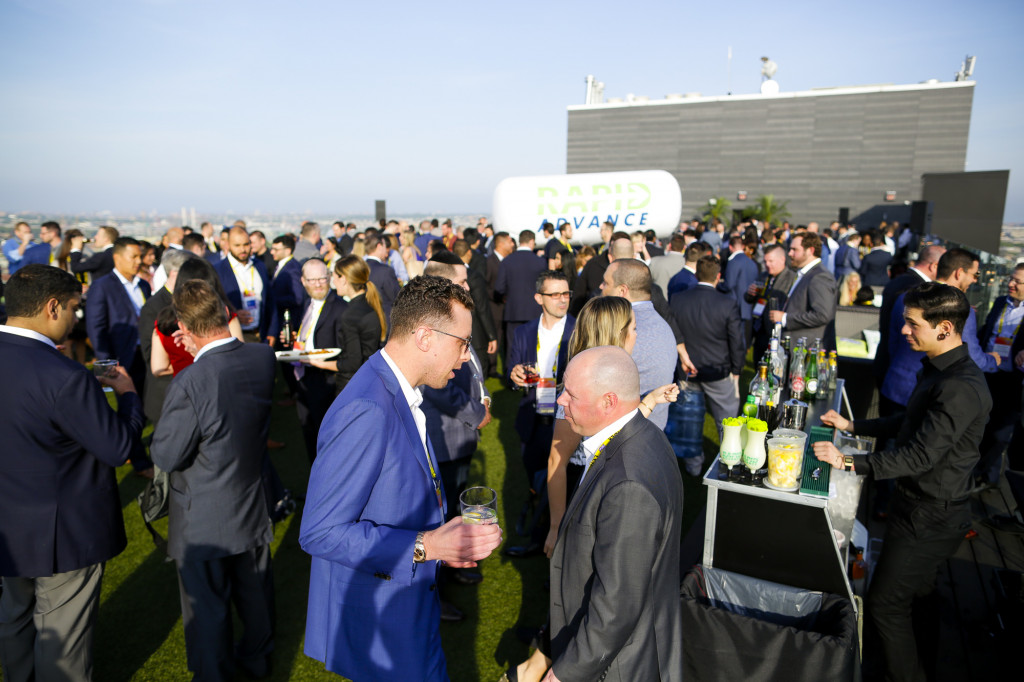
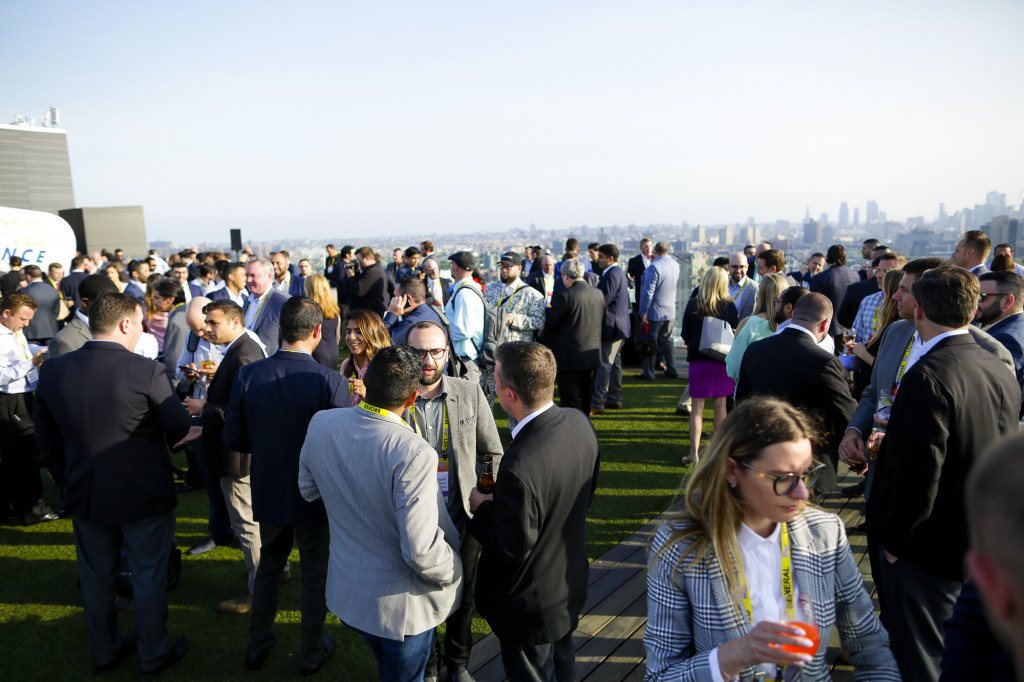
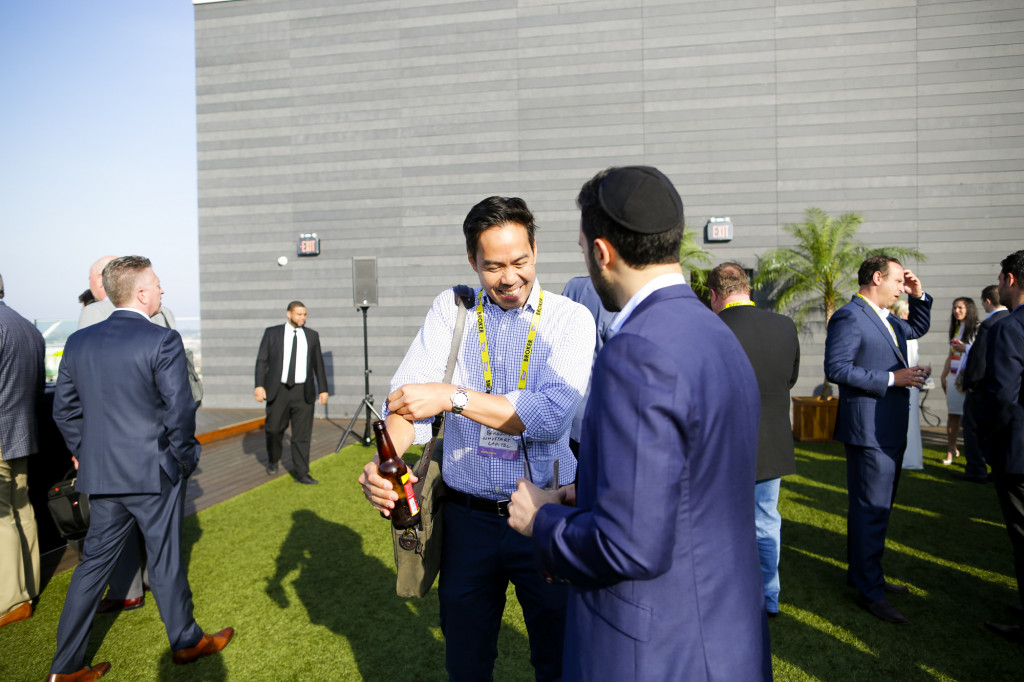
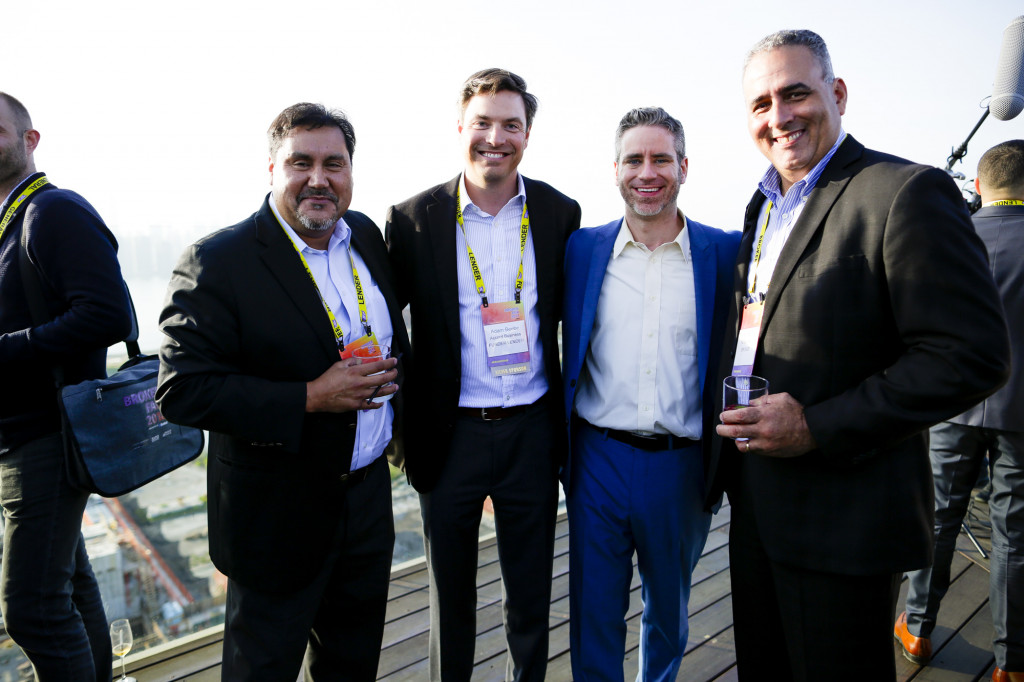
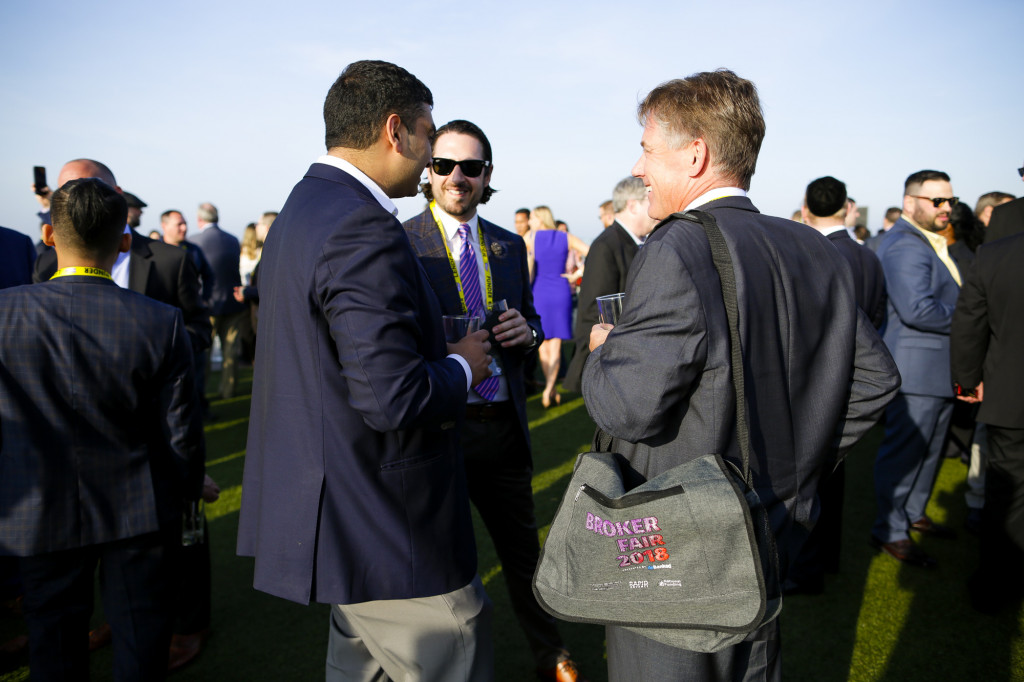
JOIN US OCTOBER 4TH IN SAN DIEGO AT THE ANDAZ FOR A SPECIAL HALF-DAY INDUSTRY NETWORKING EVENT
Couldn’t find yourself in any of our photos? We’ll publish the full album in the following weeks.
Broker Fair 2018 Pre-Show Photos
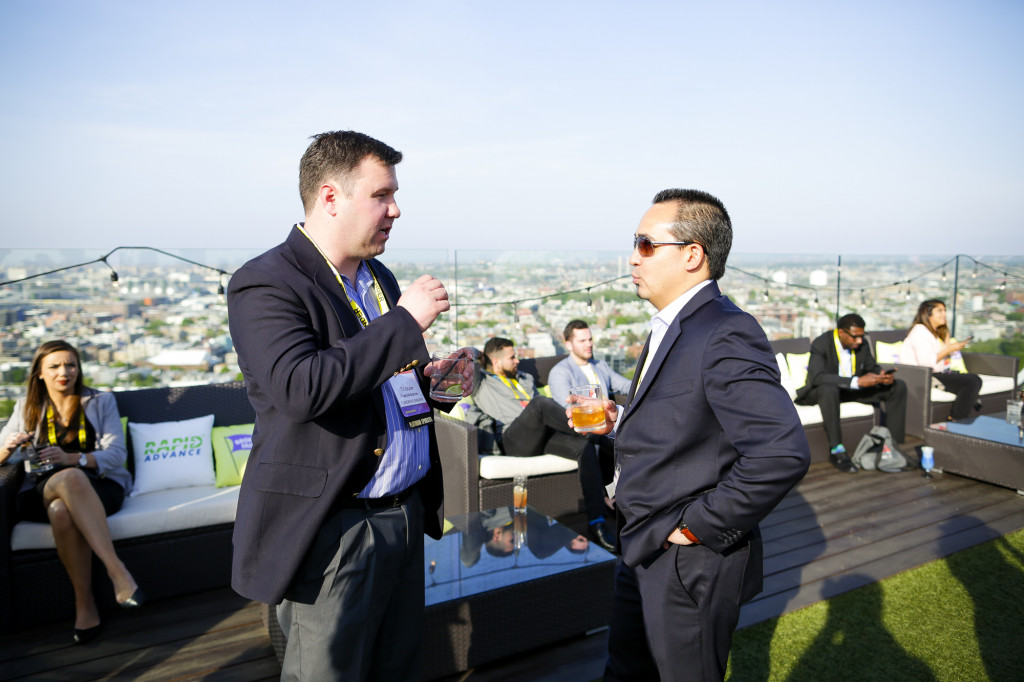
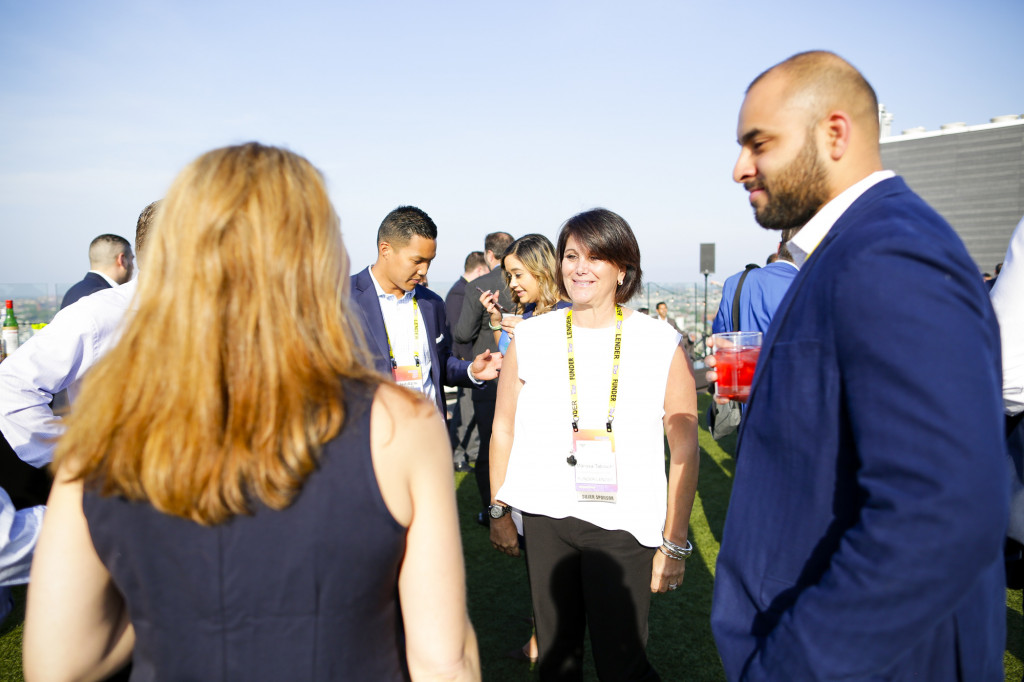
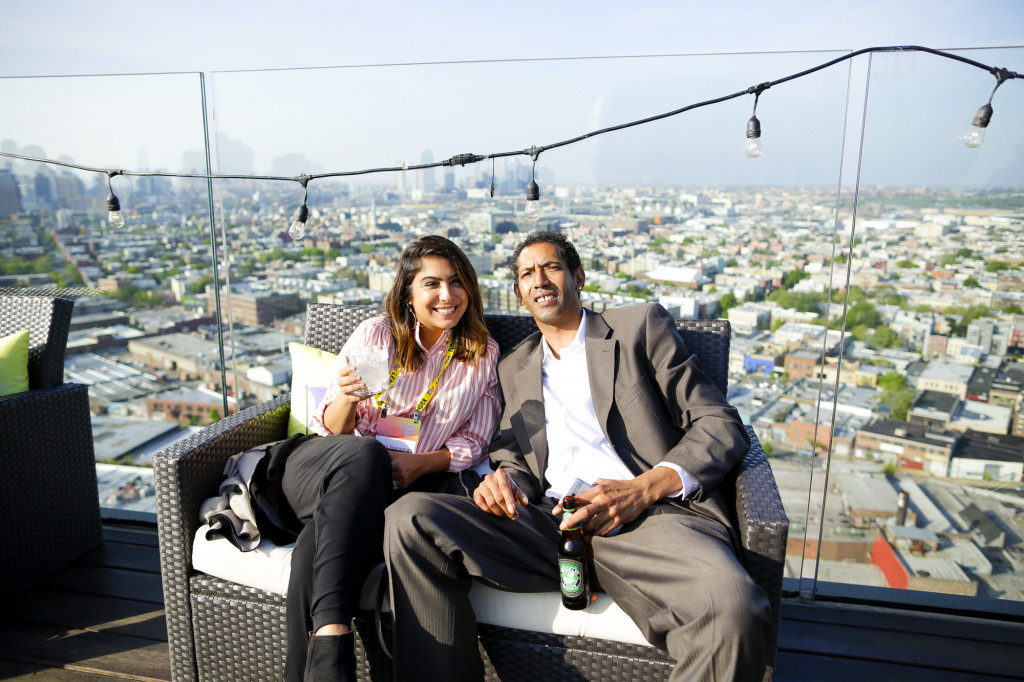
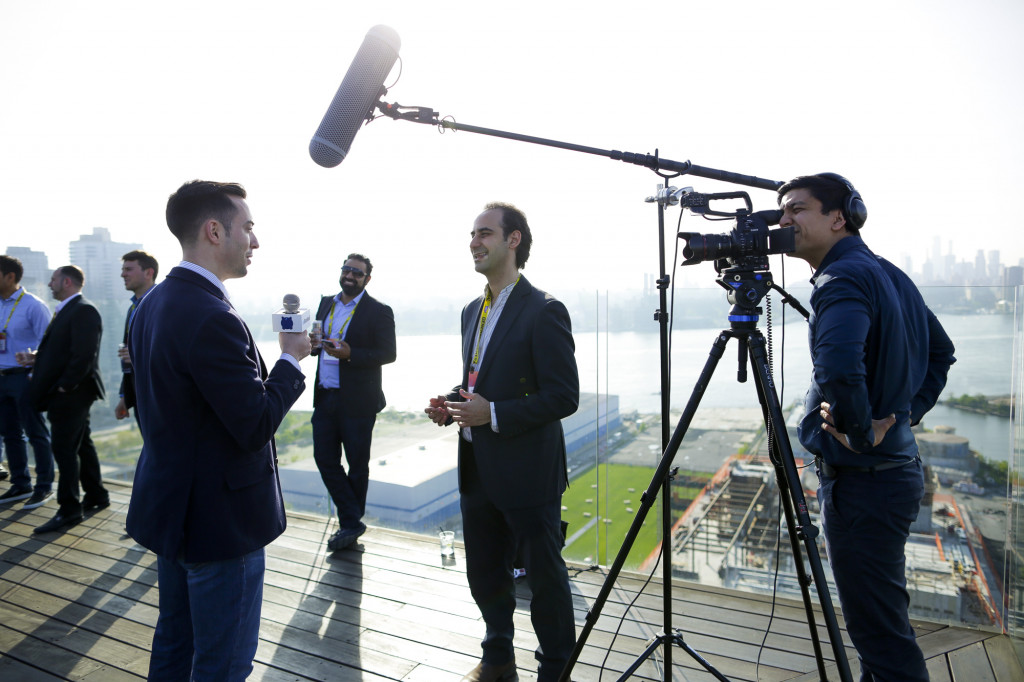
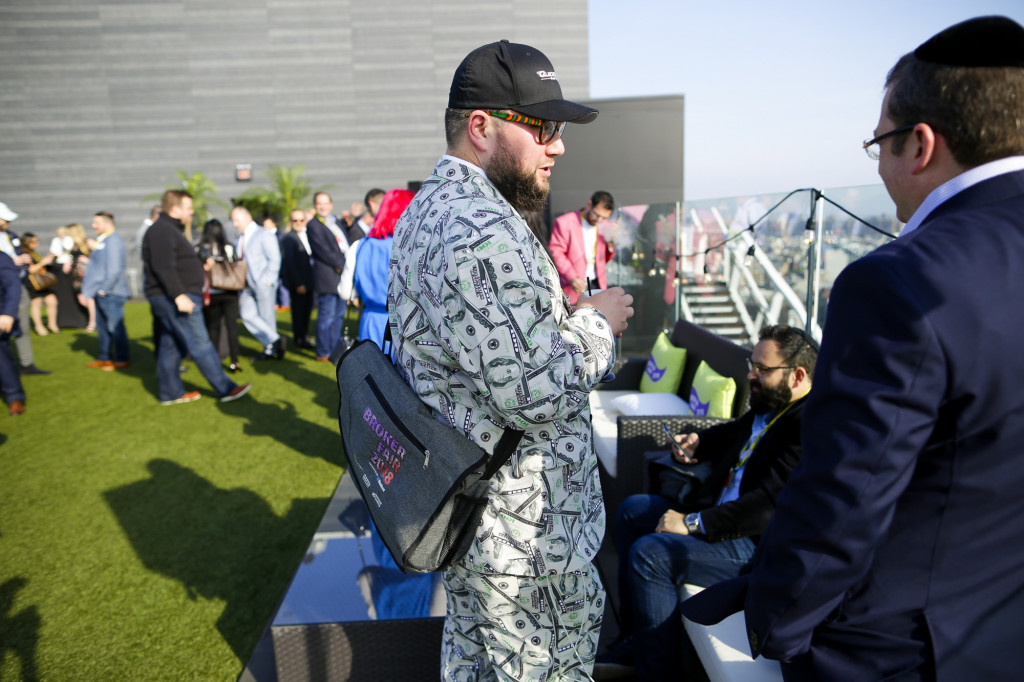
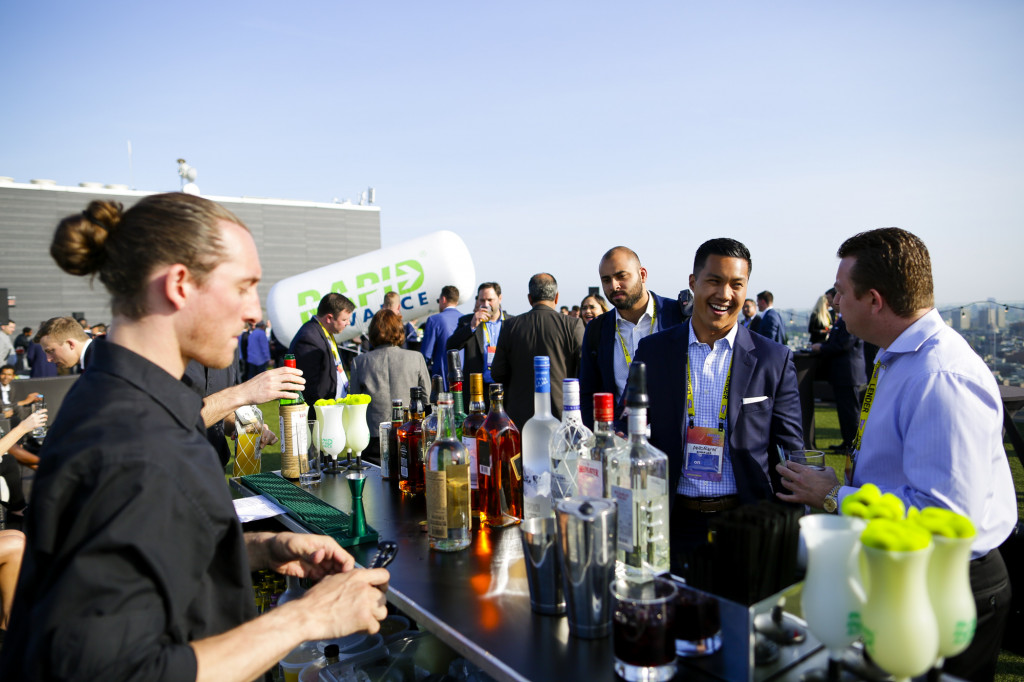
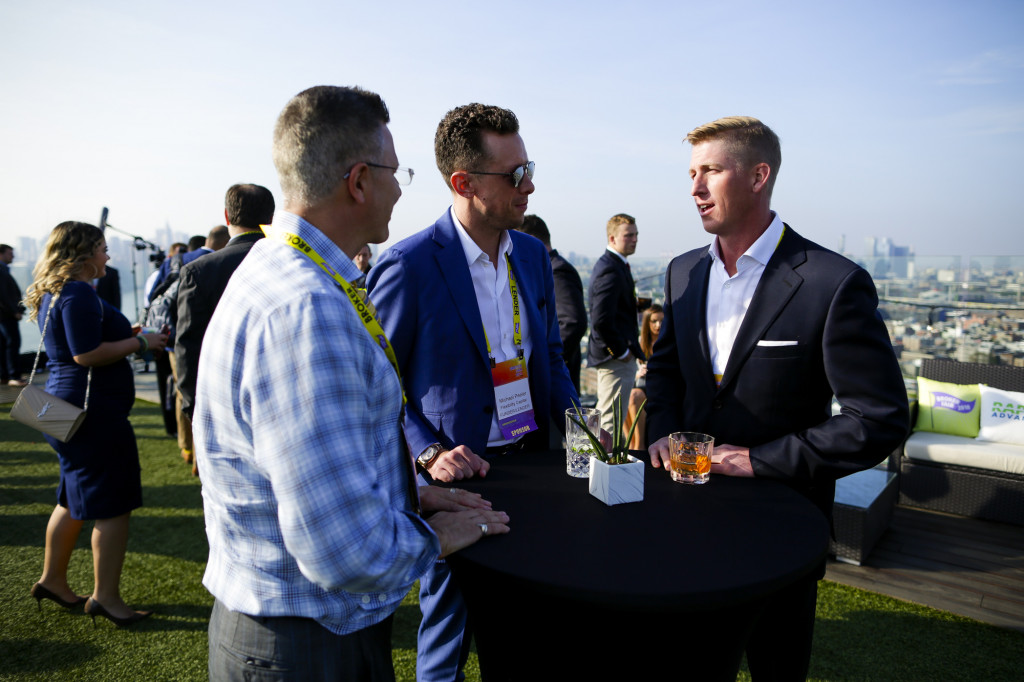
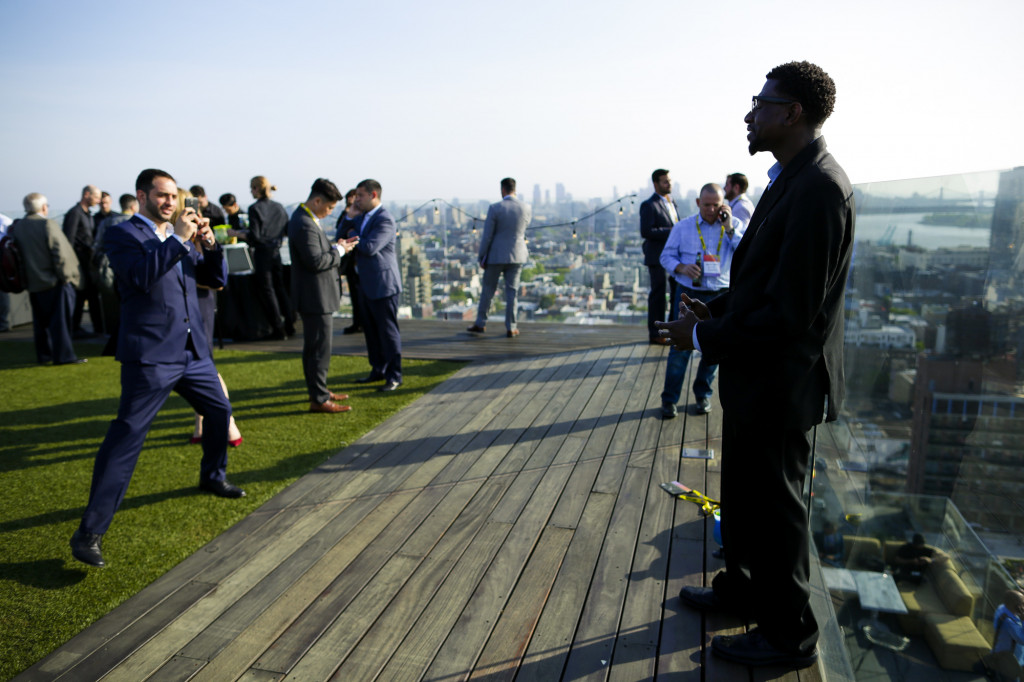
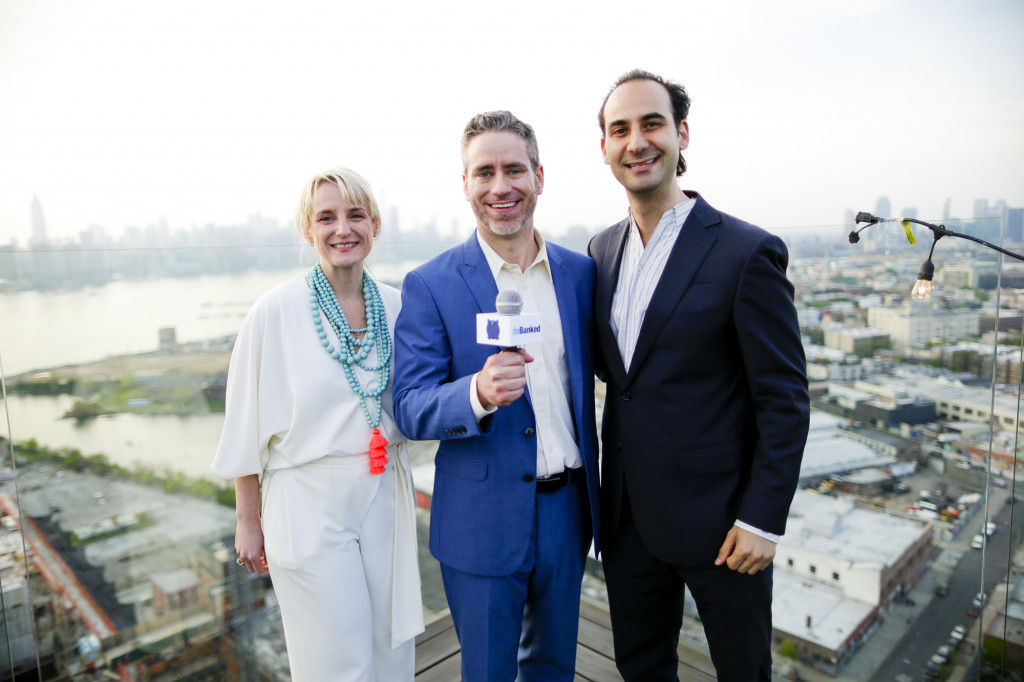
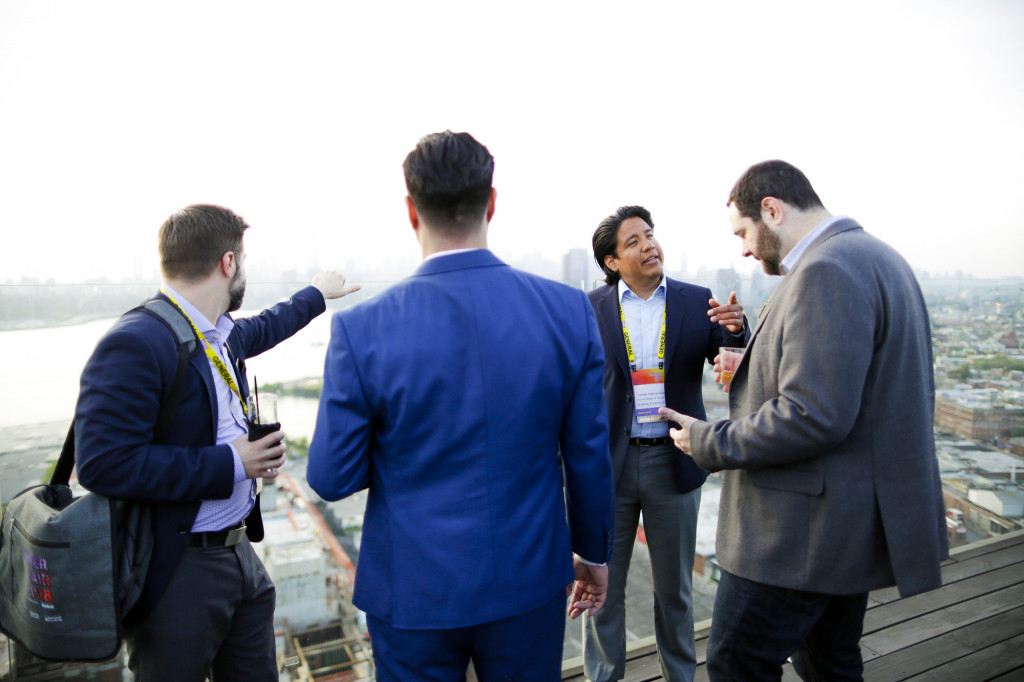
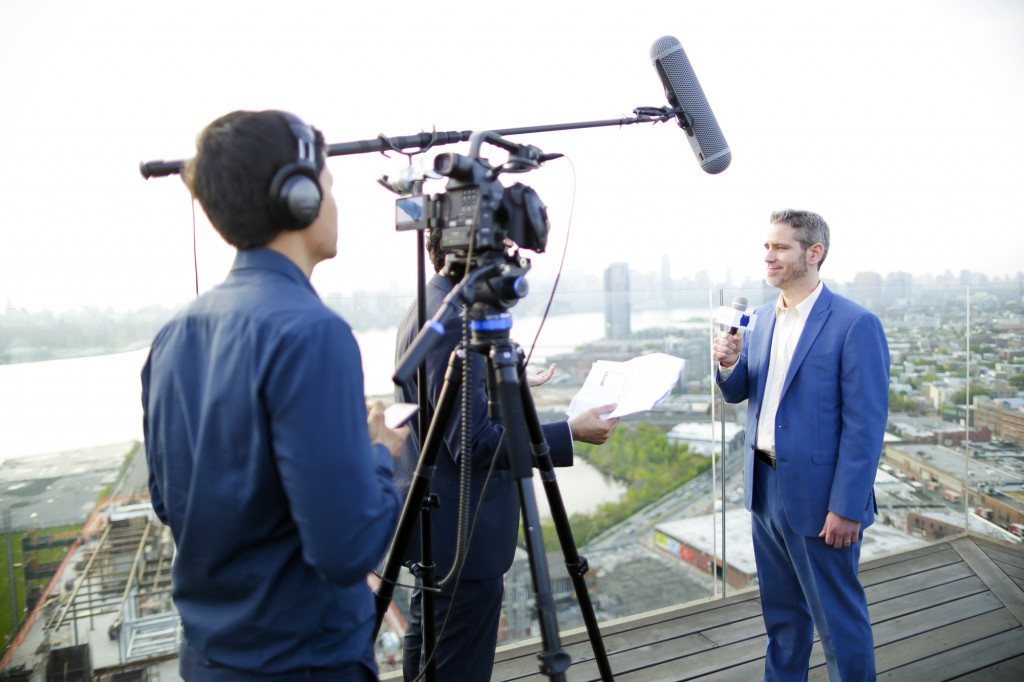
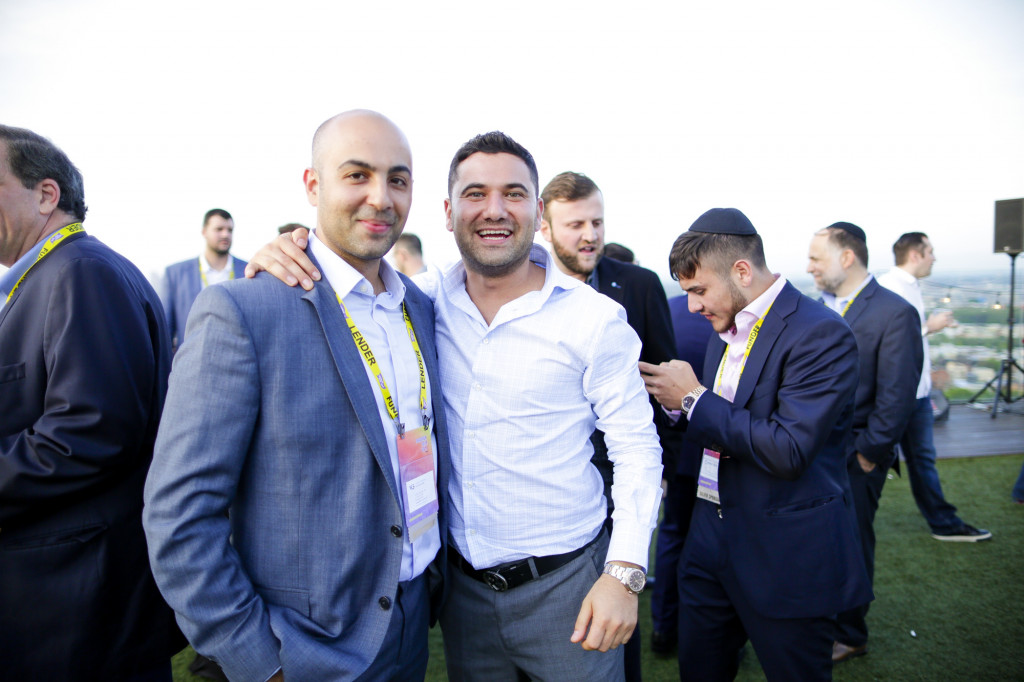
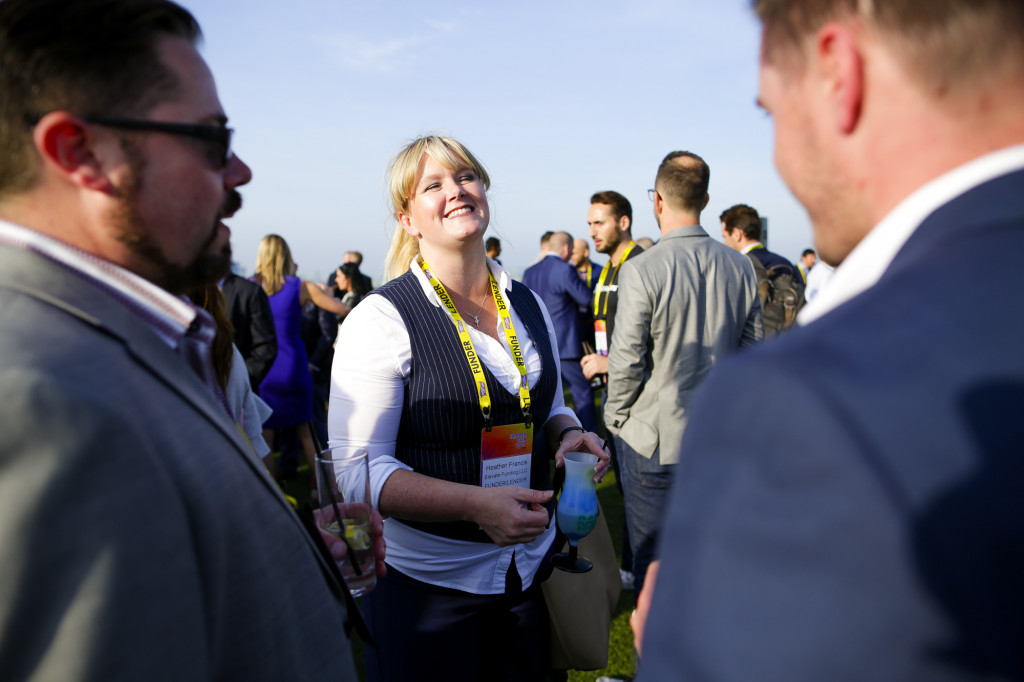
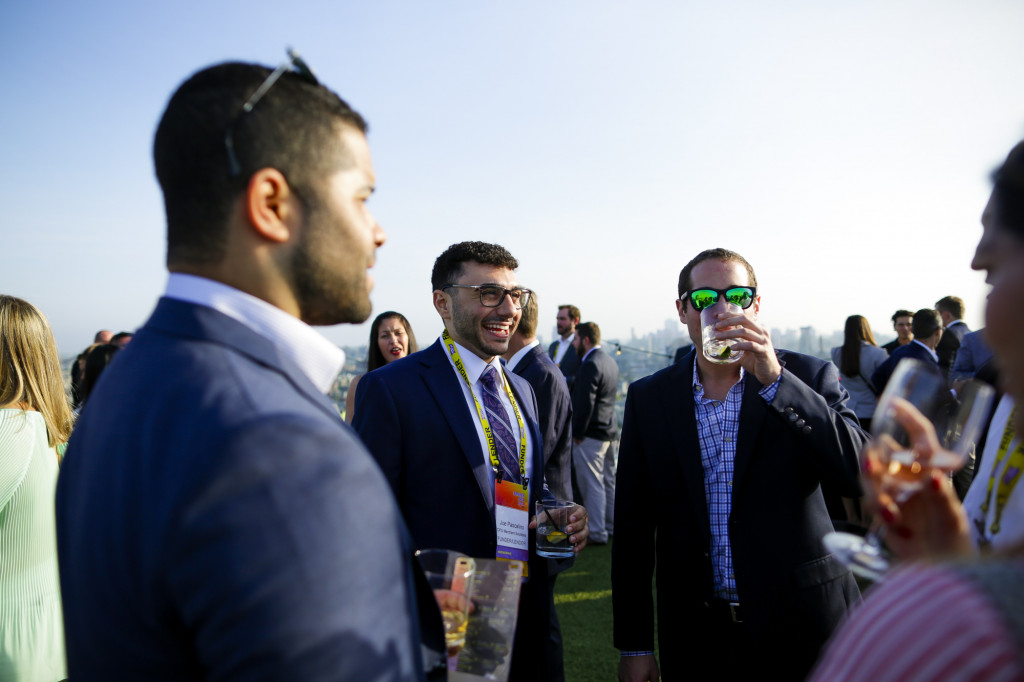
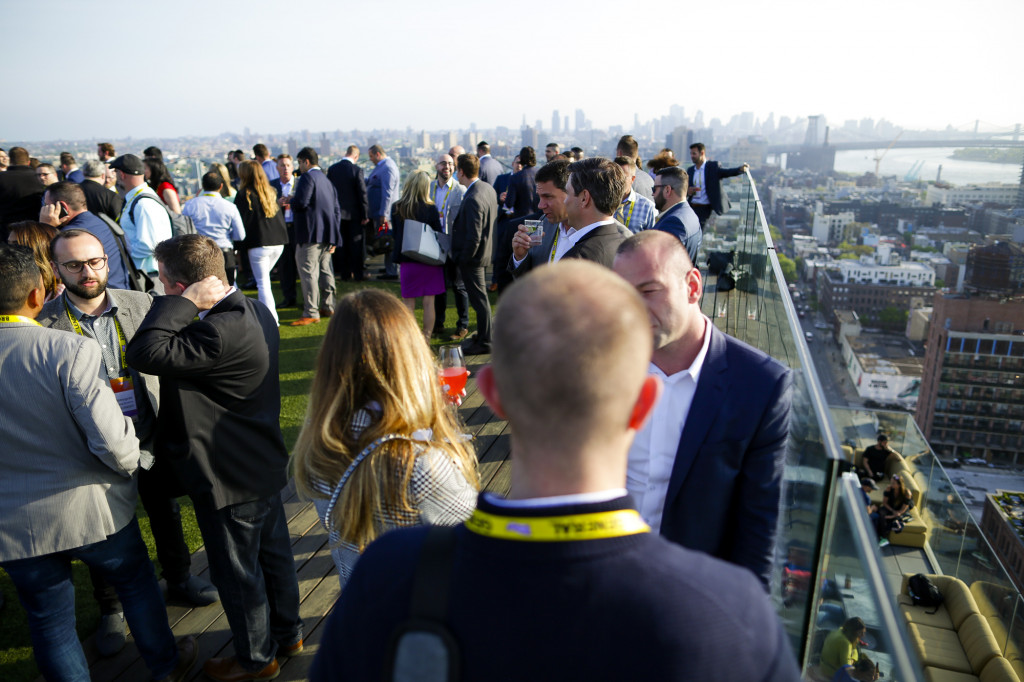
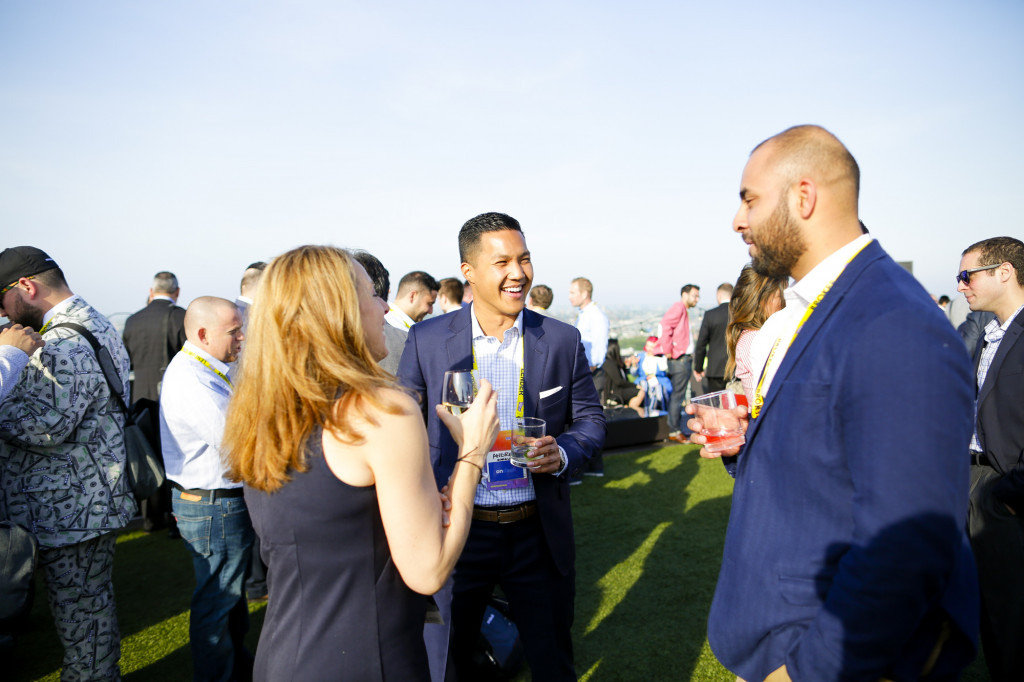
May 17, 2018Photos from the Broker Fair 2018 May 13th Pre-show party at The William Vale in the Vale Garden Residence. Photos from the conference will be published separately. We hope you had fun.