Business Lending
Chase Ends Partnership With OnDeck, OnDeck Stock Tanks On Bucket of Mixed News
July 29, 2019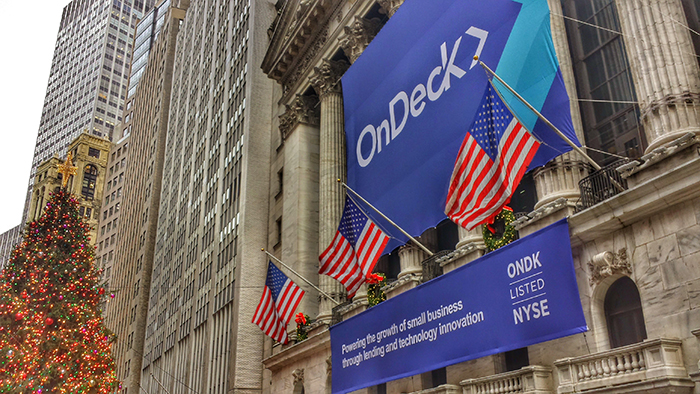 The market didn’t take too kindly to OnDeck’s Q2 earnings announcement on Monday. The stock price set a new all time intraday low of $3.01, down 24% from Friday’s close.
First, JPM Chase ended their partnership with OnDeck, the company said, bringing a 3-year relationship to a close. “We can’t speak for Chase and their change in priorities,” OnDeck CEO Noah Breslow said during the Q&A with analysts. “I don’t think it was specific to us.”
It was subsequently revealed that the relationship was never a significant moneymaker for their business to begin with. “On a standalone basis, it was a positive contributor,” the company said, but that it was “not a contributor to the bottom line profit.”
Breslow called the Chase deal a one-off that had some costs involved with it, but that they were optimistic about other deals with banks through their subsidiary ODX. “We do believe the drivers of this are not some fundamental readout on the ODX model,” he explained. “Again, we had a product that performs very well from an underwriting perspective. Customers loved it. We can’t speculate on why Chase made this particular decision. We just know it was specific to them.”
OnDeck also announced plans to pursue a bank charter and believed that the timing was right. Although they were “far along in [their] thinking,” they had not actually applied for a charter and they left the door open to possibly acquiring a chartered bank to achieve that goal. “I think the next logical milestone would be to look for some kind of either application for such a charter, but we’re not prepared to talk about a timeframe over which that would occur,” the company said.
Originations shrank to $592M, down from $636M in the previous quarter. “We do expect a return to sequential originations growth in the third quarter,” Breslow said.
The company also plans to buy back up to $50 million worth of stock to boost the share price.
PayPal Begins Offering Business Loans in Canada
July 28, 2019 PayPal has extended its popular working capital business loan program to Canada, according to company CEO Dan Schulman.
“This quarter, we began offering our PayPal business loan product to PayPal merchants in Canada, allowing them to access financing to build and sustain their businesses,” he said during the Q2 conference call. “This follows the expansion of our business financing solutions to Germany in Q4 2018 and in Mexico earlier this year in partnership with Mexican lending platform Konfio.”
deBanked ranked PayPal as the leading alternative small business finance company by originations in 2018. They are followed by OnDeck, Kabbage, Square, and Amazon.


Become: The Who, What, and Why of a Rebrand
July 23, 2019Last week Lending Express rebranded to Become. Founded in 2016, the company, which educates businesses looking for loans on how to appear more attractive to funders, was spearheaded by CEO Eden Amirav in Australia originally, with an eventual expansion to the US. Three years in, the company has over 50 lending partners across its two markets, a record of having facilitated over $150 million in funding, and more than 150,000 members on their platforms. As indicators of progress go, these are far from undesirable. So, when things were going so well, what led Amirav to decide to rebrand?
In short, the company had evolved into something different from what it was in 2016, and its name, logo, and stylized website fonts had to reflect that. Thus, Lending Express became Become.
 Gone are many of the aesthetic features of Lending Express, replaced with fresher counterparts, but beyond the brand, much of the company has remained. Amirav, the ex-pro gamer who was national champion of Israel in Warcraft 3 when he was a teenager, is still around; their AI-powered funding odds calculator, LendingScore, continues to be used; and their offices in both the US and Israel remain open.
Rather than being hoarded remnants of times past, what Become has brought with it from Lending Express were deemed necessary by Amirav when discussing what was required to execute the rebrand. Explaining that before planning for the future of the rebrand even begun, Lending Express worked for months to comprehensively take stock of itself, and Amirav noted that all hands were needed and the entire company pitched in. Whether it was ensuring that URL links which once directed people to Lending Express now went to Become, or the drafting up of the new name, much of the work that went into the business’s metamorphosis came from within the company. Of course, Become specializes is helping small businesses get approved for loans, so not everything could be done by themselves, which is where a marketing firm came in to aid them with the crafting of the company’s new image.
As to the motives of the rebrand, the brief explanation given above doesn’t cut it. A blog post on Become’s website explains the origins of both names. With Lending Express having a ‘do-what-it-say-on-the-tin’ aspect to it, Become is much more abstract in how it reflects the company. Noting that Become originates from both within the company and without, Amirav explains the name owes itself to Lending Express’s development into a “no human-touch, all-tech based” company, following LendingScore’s creation; as well as the business’s ability to help its customers achieve their goals, enabling them to become what they wish.
Rebranding comes at a massive financial cost, with no guarantee of an immediate large payout upon launch, but as Amirav asserted, the switch to Become was necessary in his long-term plan for the company, as the “stress [of the rebrand] is offset by the goal of where they want to go.” “We’re well equipped with people, resources, and vision,” Amirav went on to say, and as well as this, he believes in the importance of a strong brand, regardless of industry, claiming that it “becomes a power to work with.”
And with their new logo and four-tone color palette sure to catch eyes, perhaps Amirav’s gamble will pay off. For now, he’s content with his rebrand going public, the continued business of Become, and the “shareholders [being] happy.”
Breakout Capital is BACK
July 17, 2019
SecurCapital Corp has acquired the lending business of Breakout Capital Finance.
Breakout was founded in 2015 by Carl Fairbank, a former investment banker, and quickly made a splash in the burgeoning small business lending industry. The company has raised significant capital and is a principal member of Innovative Lending Platform Association (ILPA), a trade group that among other things, created SMART Box, a uniform loan disclosure meant to enhance transparency across the industry.
Earlier this year, however, the company suspended originations.
But that’s poised to change. The deal with SecurCapital, a supply chain and financial service provider headquartered in California, means that Breakout is on track to resume originations as early as next week, according to the company. And there’s other changes afoot.
Tim Buzby, who previously served as the company’s CFO is now the President & CEO. Buzby is well primed for the job. He’s a former CEO of Farmer Mac, a company he spent 17 years with.
Carl Fairbank, who previously served as CEO of the lending business, will provide strategic guidance during the transition, the company reports. He will no longer have a day-to-day role.
“After four years as Founder and CEO of Breakout Capital Finance, this transaction begins the next chapter of Breakout Capital’s lending business,” Fairbank is quoted as saying in a company announcement. “SecurCapital is also committed to the proliferation of best practices to drive change in the broader market. I believe Breakout Capital, in partnership with SecurCapital, is now well positioned for substantial growth, especially with its commitment to FactorAdvantage.”
Fairbank is reportedly shifting his focus toward driving innovation in artificial intelligence, machine learning, and blockchain.
Breakout Capital has also hired McLean Wilson, former CEO of Charleston Capital (fka Drift Capital Partners), an asset manager in the SME space, and former CEO of inFactor, a factoring company, as Chief Credit Officer.
In an interview with Breakout’s new CEO Tim Buzby and VP Jay Bhatt (who has been with the company since the very beginning), they said that the company’s risk criteria and credit box will remain the same as it was previously, with potential to even expand it down the road. The company pressing the originations pause button from approximately February to July, therefore, shouldn’t be interpreted as a weakness of the company’s business model. Rather the acquisition and changes should suggest the opposite.
Steve Russell, CEO of SecurCapital, commented, “We’re delighted to have found a highly respected team and innovative business model in the small business finance space. I share the founder’s vision of the massive potential of the FactorAdvantage lending solution and believe we now have the platform and capital to rapidly grow this industry-changing product. We couldn’t have found a better business to complement SecurCapital’s strategic vision for empowering small businesses.”
Two SecurCapital executives have also been placed on Breakout’s board of directors.
Buzby confirmed that operations will resume as normal. The business address and business name will remain the same with one notable difference; That being that the name has been shortened from Breakout Capital Finance to Breakout Capital. It’s also now being operated by a subsidiary of SecurCapital.
Key Takeaways from the Q2 2019 Private Capital Access Index
July 17, 2019The latest Private Capital Access Index, published quarterly by Pepperdine Graziado Business School, was released recently, and with it came fresh insights into the minds of business owners. Covering companies that earn under $5 million in revenue annually, as well as those that raise between $5-100 million, the Index provides information on a wide range of business. Below are snapshots of some of the main points found within the report:
More Large Businesses Appear to be Looking for More Money
Businesses that earn between $5-100 million a year are seeking to raise more financing in 2019. Compared to 2018, many loan ranges have seen jumps: the amount of larger businesses seeking between $500,000-999,999 has over doubled in size to 39% and $1-1.999 million has more than tripled to 28%. However, outside of this range, desire has fallen for financing among larger firms.
Slight Fluctuations in How Quickly Customers Are Paying
The past year has witnessed some small changes in the speed at which businesses receive payments from their customers. With 15% of smaller businesses reporting accelerated reception of payments in the previous three months, an increase from the 11% that was stated this time last year, and an increase of 1% of larger businesses claiming a speed up, it seems at least that a small sector of fortunate vendors are benefitting from increasingly prompt customers.
Accompanying these figures are the reports of payments slowing down, that show a 2% increase amongst smaller companies and a drop to 10% from 23% for their larger counterparts. This jump is accounted for by the 81% of larger businesses which reported that the speed of payments remained the same, which is up from 70%; while the smaller firms reported 63%, down from 68% in 2018.
More Businesses Are Planning to Raise Finance
More businesses of all sizes are looking to raise capital in the coming six months compared to 2018, with 35% of small businesses and 28% of larger businesses claiming that they will be seeking financing, an increase of 5% for both. This news, coupled with the knowledge that the total number of businesses which said they will not be seeking finance dropped, may come as a gift to lenders and brokers, but it should be taken with a pinch of salt, as those who said they were unsure also rose by 4% to 35%.
Purposes for Raising Finance Remain Mostly Unchanged
Growth and expansion continue to be the primary reason for seeking finance, with an increase on last year from 58% for both the smaller and larger companies to 62% and 77%, respectively. As well as this, working capital fluctuations and refinancing existing loans/equity remain as the second and third highest reasons to raise funds, with the total of the former dropping 3% to 17% and the latter falling to 7% from 10%. Besides these motives, capital required to replace equipment or facilities unrelated to expansion saw a dip of 4% in larger businesses.
Businesses Are Optimistic
Despite over 50% of businesses saying that it is difficult to acquire both equity and debt finance, as well as 49% claiming that the current business financing environment restricts growth opportunities, businesses appear to be confident about the future, with 68% of them expecting increases in revenue over the next year. Also, respondents appear to be unconcerned by external forces, as 57% of businesses don’t believe the federal tax hike will impact them and 74% don’t expect to be hampered by severe weather from climate change. These may or may not prove to be naïve as time goes on, especially the latter, as 56% of the respondents do not have emergency funds in place should severe weather disrupt their business, but for now companies seem to be looking forward to the coming year.
The full report is available here.
Online Lenders Beat Credit Unions, Friends, and Family as Primary Source of Credit
July 14, 20197% of small businesses generating less than $5 million/year in revenue relied on online lenders as their primary source of credit in the last quarter, according to the latest Private Capital Access Index published by Pepperdine Graziado Business School. 3% relied on credit unions as their primary source and 6% relied on friends and family.
Banks were the most popular. 19% relied on large banks as their primary source of credit and 12% relied on community banks.
38% said they didn’t have any source of credit at all.
Sticking with the under $5 million/year segment, 45% of respondents explained that their primary source of credit had become so simply because they were able to qualify for it. 21% said their primary source became so because they couldn’t qualify for any other source.
Meanwhile, merchant cash advances, online business loans, and factors experienced among the lowest reported approval rates for businesses of all sizes. Of those businesses that applied for financing, the success rate in obtaining funds are as follows:
| Financing Type | Success Rate |
| Business credit card | 65% |
| Trade credit | 57% |
| Personal loan | 51% |
| Lease | 48% |
| Bank loan | 41% |
| Online lender | 38% |
| Merchant cash advance | 31% |
| Asset Based Lender | 28% |
| Factor | 23% |
| CDFI/Credit Union | 18% |
While bank loans came in at 41%, revenue was a major determining factor. 88.9% of businesses doing $5 million to $100 million/year in revenue successfully obtained a bank loan while only 31.6% of businesses doing less than $5 million/year in revenue successfully obtained a bank loan.
OnDeck Canada, Credit Union Announce Partnership
July 11, 2019 Today sees the partnership of OnDeck Canada and Coast Capital Savings, the first collaboration of its kind in Canada, being between an online lending company and a federal credit union.
Beginning this month, small business members of Coast Capital will be able to apply for term loan financing from OnDeck Canada of up to CAD$250,000 online, in branch, and via the Coast Capital Contact Centre. And as a perk of partnering with an alternative financing company, Coast Capital members will benefit from the fast turnaround times for approvals and funds being made available that are typical of the industry, with waits being as short as one day.
The move comes as OnDeck Canada is expanding to Quebec, paralleling Coast Capital’s efforts to spread across the nation, beyond its home of British Colombia. Both parties appear to be approaching the partnership with similar visions of where it will take them, with Tiffany Kayar, the OnDeck Canada Communications Manager, explaining that OnDeck is able to further help fund those small businesses who have been historically underserved by alternative financing, and Coast Capital will benefit from a greater national presence.
It is one more notch on OnDeck’s belt of partnerships, coming after the online lender linked with JPMorgan Chase in 2017 and PNC Financial Services Group last year to extend loans to businesses.
And for Coast Capital, which has the largest membership base of any credit union in Canada, it is a development that is consistent with their history of innovation. Having offered Canada’s first free checking account from a full-service financial institution and Help Extras®, which further assist members with investing, this opening up of funding channels to small business owners further cements Coast Capital’s position as a unique non-bank choice for finance management.
With small businesses comprising 98% of Canadian businesses, this partnership is hoping to provide support for such a large sector of the country’s economy. Saying in a press release that “As the proven leader in online small business lending, OnDeck Canada is delighted to partner with Coast Capital to offer online financing to its small business customers, ensuring that their unique and ever-evolving needs are met faster than ever with the power of automation and a world class digitized customer experience,” Neil Wechsler, CEO of OnDeck Canada, is confident that the synergy between OnDeck’s tech and Coast Capital’s membership will benefit the Canadian business community. Just as Derek Turner, Head of Small Business at Coast Capital, is sure that the partnership will “deliver the Coast Capital experience that so many members already enjoy, to even more people across Canada.”