Business Lending
BlueVine is Back and Now With Business Checking Accounts
August 28, 2020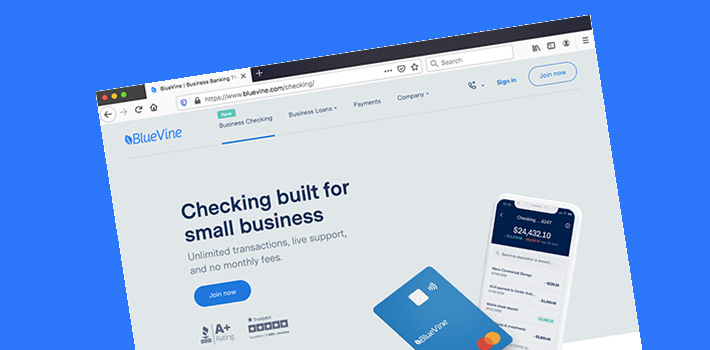 BlueVine, a leading small business lender, has resumed its normal services after generating $4.5 billion in PPP loans to more than 155,000 businesses. The company had continued to offer its normal lending products even while others in the industry paused completely, the company says. Herman Man, the chief product officer, said that BlueVine has also fully launched a small business checking account platform.
“Our goal always was to be that small business banking platform,” Man said. “Last year at Money 20/20 we announced we were going to build a small business checking account. Recently, we launched it post-COVID, derailing our plans. We have a breadth of offerings now, and we are that small business platform.”
BlueVine also released a survey this week of more than 800 small business owners to learn what they need most in an ever-changing market. Their findings supported their online product offering. Distressed by COVID-19, the respondents reported an overwhelming interest in reliable customer service, day to day support, and fee-less transactions.
77% of small business owners surveyed reported demand for direct guidance in day-to-day accounting. In the face of an emergency, many respondents noted that banks were more interested in new customers than servicing current customers.
Following this emergency support trend, nearly nine out of ten or 87% of small business owners said access to emergency credit was necessary from the same bank providing them regular service. Accessing credit from the same provider was not just important, but over half or 64% reported it was exceptionally so.
Finally, 58% of business owners reported that a lack of overdraft, monthly, or maintenance fees were the essential features a business checking accounts could offer.
With the launch of a checking account platform, BlueVine can service the needs of these businesses, offering one common platform that connects factoring services, payments services, and now credit and banking services.
“If a small business wanted to take a line of credit and do it on a Friday night, using our algorithm and things that are automated, it could run through our system; if they get approved, money would be transferred into their checking account instantaneously,” Man said. “This isn’t something they have to wait until Monday morning. It will land immediately, so that’s a huge game-changer.”
Banks, Non-Banks, Fintech and More Came Through for Lendio on PPP, But it Wasn’t Easy
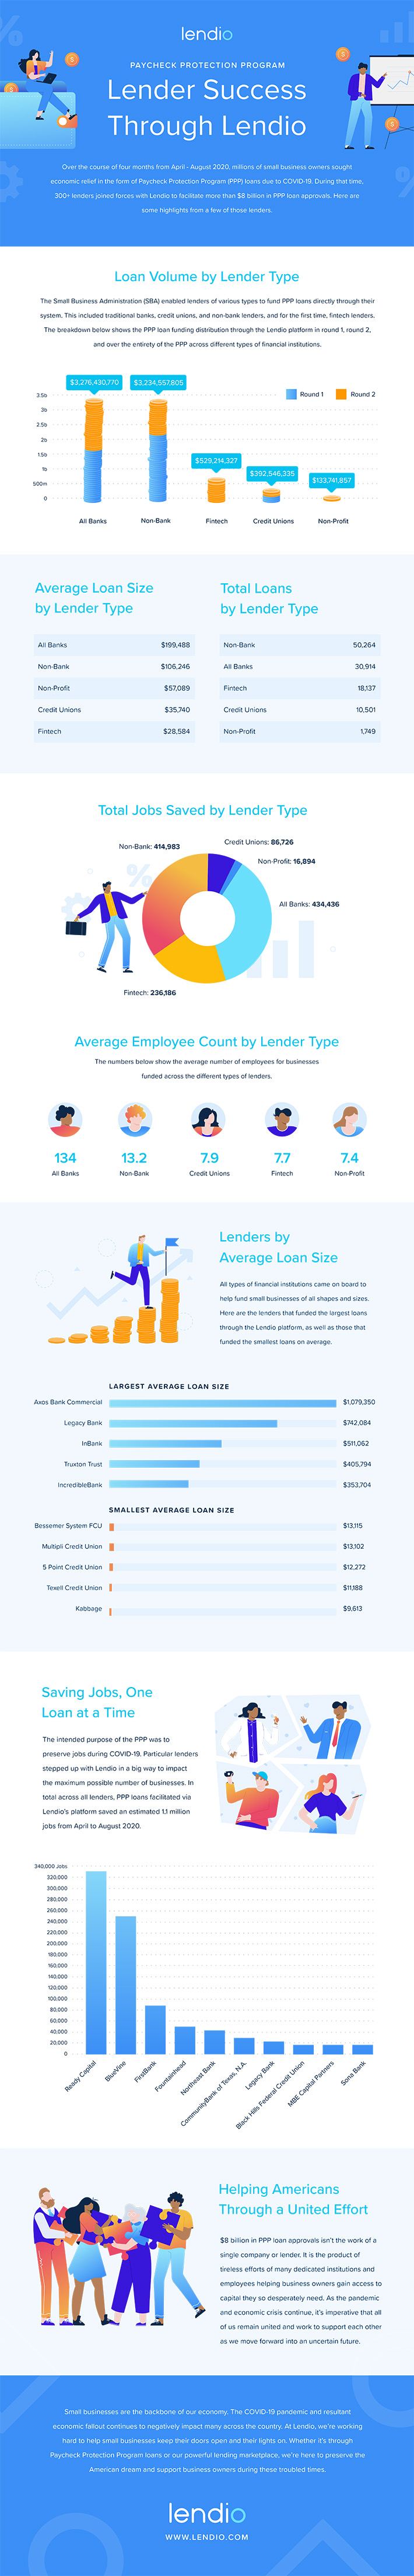
August 27, 2020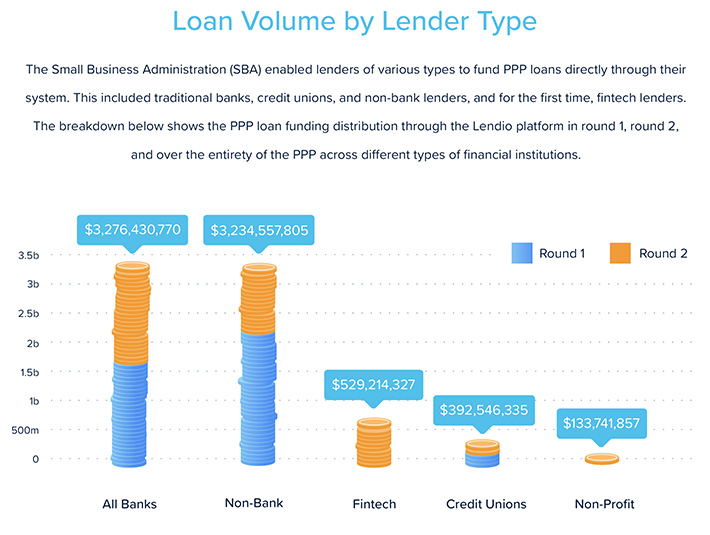 Last week, Lendio, a facilitator of small business loans, released a report analyzing the $8 billion of PPP loans that were approved through its lending platform. A coalition of more than 300 lenders was able to give aid, saving an estimated 1.1 million jobs, Lendio indicates.
Through Lendio’s service, traditional banks approved the most funding at $3.3 billion- or about 44% of the PPP dollars on the platform. Though non-bank lenders secured the highest number of approvals at 50,264 transactions in lesser dollar amounts.
Fintech lenders funded 6% of the total loan volume through the platform.
Lendio was well situated to facilitate lending from institutions to those that needed help through funds provided by the SBA. Brock Blake, CEO, and co-founder of Lendio, said the company’s success in delivering on PPP was no accident— they had to remove all stops and almost bet on the success of the PPP program.
“Our mission at Lendio is normally ‘Fueling the American Dream’: helping the American business owner accomplish their dream,” Blake said. “We tweaked our mission during this timeframe to ‘Saving the American Dream.'”
Blake said while other companies were closing their doors and sending off employees on furlough, Lendio took on 250 new hires- and buckled down for thousands of hours of engineering work to overhaul their system. Not just loan sales, but legal processes, onboarding, training, and backend tech work had to be updated in just days.
This all came on fast, but so did the quarantine. Beginning in April, more than 100,000 business owners applied for economic relief under the PPP using Lendio’s online marketplace.
The demand for capital was outrageous.
“It was more demand in one weekend than the SBA had seen in the last 14 years combined,” Blake said. “We were helping these business owners that were watching their entire lifes’ work flushed down the drain in a matter of weeks, and they were desperate for capital.”
Lendio was finding that many institutions could simply not handle the volume, Blake said, and he knew if banks were only able to process loan requests for their current customers, there would be an exploding demand for loan processing. The company took on 100 new partners who needed help during this time.
“Our systems were tested to their limits, like 1000 times more pressure than we ever saw before,” Blake said. “Some partners of ours got so much demand they couldn’t handle it and turned off their spigot. So we scrambled to find lenders that would take on new customers.”
Though it was ten times more challenging than anything Blake has done in his career, it was ten times more satisfying. Lendio doubled the number of loans it has issued since 2011, and quintupled the dollar amount the platform facilitated in just four short months. Where are they going to go from here?
For one, Lendio is one company out of many that are hoping for another round of PPP funding. Blake said he is getting customer feedback all the time asking for help, dealing with quarantine regulation that is harming business, like restaurants that have nowhere to seat patrons.
Outside of PPP, Blake said that many of the 110,000 businesses they served are now applying for other loans, or using Lendio’s bookkeeping and loan forgiveness applications. Lendio is happy to help business owners and banks through this tough time by launching digital applications.
“Before, lenders across the country were requiring business owners to come into branches [with] paper applications,” Blake said. “Now, there’s not one business owner in America that wants to walk into a bank branch. The demand for lenders to go digital is as high as it’s ever been.”
QuickBooks Capital Has Already Funded $683M in Cumulative Business Loans
August 26, 2020 QuickBooks Capital has funded $683 million in cumulative small business loans since Intuit launched the program in late 2017. This excludes the $1.2 billion in PPP loans the company facilitated, according to the latest quarterly earnings report.
Showing optimism, Intuit recorded revenue of $1.8B in Q4 and $7.7B for the fiscal year, up 13 percent.
Among Intuit’s leading products is TurboTax, which experienced its strongest customer growth in four years. Growth was also strong with QuickBooks online payments, QuickBooks Online payroll and TSheets.
Intuit announced that it was acquiring Credit Karma for $7.1B in cash back in February.
Sketchy Virginia SBA Loan Brokers Indicted
August 26, 2020Ronald A. Smith and Terri Beth Miller, owners of Virginia-based Business Development Group (BDG), an SBA loan brokerage, were indicted this month over an advance-fee scheme in which many customers are alleged to have paid money to obtain SBA loans but did not in fact get them.
As part of the scheme, defendants are alleged to have made many false and misleading representations to prospective borrowers including that:
- BDG was a large, multi-state company
- BDG was headquartered at the Trump Building in New York City and had an additional business in Las Vegas
- BDG has assisted certain named companies in obtaining SBA loans
- BDG was a business established in 2005 or earlier
- BDG was affiliated with the SBA
- BDG had relationships with banks across the nation that allowed it to facilitate the loan approval process with SBA lenders in a customer’s area by utilizing a “Lender Linker” made up of the most preferred SBA lenders in the country
- BDG had a program that included a “Powerful Online Grant Writer Interface Service” that was directly connected to the federal government and “handled everything from A to Z in Finding, Writing, Submitting and Securing Grants”
- BDG offered a money back guarantee
- BDG won the 2016 Best of Manhattan Business Award for Business Development Software and Services
BDG was really just an internet-based business whose goal was to obtain money through fraudulent pretenses and promises, prosecutors contend.
A copy of the grand jury indictment can be obtained here.
Section 1071 is Back and The CFPB Wants to Know How Much It Will Cost You to Comply
August 25, 2020 At some point in this century, small business finance companies will be expected to comply with Section 1071 of the Wall Street Reform and Consumer Protection Act that was passed in 2010.
In the wake of the ’08-’09 financial crisis (remember that?!), lawmakers passed the above act that has become colloquially known as Dodd-Frank. Section 1071 gave the Consumer Financial Protection Bureau the authority and the mandate to collect data from small business lenders (and similar companies).
The costs, risks, and challenges with rolling out this law have been discussed on deBanked for 5 years, yet little progress has been made to finally implement it. But it’s starting to move along and the CFPB would now like to know how expensive it will be for businesses to comply.
If you are engaged in small business finance, you should seriously consider submitting a response to their survey. The CFPB is specifically cataloging responses from merchant cash advance companies, fintech lenders, and equipment financiers.
Lendified Is Still Trying To Pull Through
August 18, 2020 On June 29th, deBanked ran a story titled Canadian Small Business Lender Looks Doomed In Wake of COVID-19. It was about Lendified. Several of the company’s top executives had recently resigned and its financial situation was dismal.
“Lendified is in default in respect of credit facilities with its secured lenders,” the company disclosed at the time. “Forbearance and standstill agreements are being discussed with these senior lenders, with none indicating to date that any enforcement action is expected although each is in a position to do so, however, no formal agreements in this regard have been concluded as of the date hereof.”
Among the company’s last ditch plans to recapitalize was the raising of equity through a private placement. But that was made impossible by the Ontario Securities Commission who entered an order prohibiting any such transaction for “failing to file certain outstanding continuous disclosure documents in a timely manner.” The filing failures, of course, were due to the issues they were facing. This order just compounded them.
The Commission partially revoked the order on August 14th, paving the way for the private placement to continue. Lendified is only seeking up to $1.4M, the proceeds of which would be used to “pay, among other things, outstanding fees owed to the Company’s auditors and other service providers, public and filing fees, legacy accounts payable as well as for general working capital purposes.” The company further said that “Completion of the Private Placement will help the Company in its efforts to prepare and file the outstanding continuous disclosure documents with the applicable regulatory authorities.”
Lendified offers no guarantees that the private placement will be successful. The company sold off a subsidiary, JUDI.AI, in July.
How An Online Lending Hedge Fund Manager Became “Unwound”
August 12, 2020 In 2017, Ethan Senturia, the founder of a defunct online lending company, published a tell-all book about his startup’s rise and fall. He called it Unwound. It’s the fall that stood out. Senturia’s poorly modeled business had been heavily financed by an up-and-coming online lending hedge fund manager named Brendan Ross.
I first encountered Ross in 2014 on the alternative finance conference circuit. Ross’s major theory was that small businesses overpay for credit and that the padded cost served as a hedge against defaults and economic downturns.
“The asset class works even when the collection process doesn’t,” Ross said during a Short Term Business Lending panel at a conference in May 2014. “The model works with no legal recovery.”
 As an editor, I helped secure a lengthy interview with Ross that Fall. In it, he placed a special emphasis on building “trust.” It’s a word he used seventeen times over the course of the recorded conversation. “Everything is about trust and eliminating the need for it whenever possible,” he proclaimed.
Ross stressed that his fund invested in the underlying loans of online lenders, not in the online lenders themselves. “I need to be the owner of the loan. I need it sold to me in a way that is completely clean.”
Ross would eventually connect with Senturia at Dealstruck, an online small business lender whose philosophy seemed to contradict Ross’s mantra of small businesses overpaying for credit. Dealstruck, it would turn out, had a tendency to have them underpay…
Senturia told the New York Times that year that Dealstruck’s mission was “not about disintermediating the banks but the very high-yield lenders.”
It’s a concept that failed pretty miserably. Senturia recalled in his book that “We had taken to the time-honored Silicon Valley tradition of not making money. Fintech lenders had made a bad habit of covering out-of-pocket costs, waiving fees, and reducing prices to uphold the perception that borrowers loved owing money to us, but hated owing money to our predecessors.”
As the loans underperformed, Senturia became aware that the hedge fund backing them, Ross’s Direct Lending Investments, might also be doomed. Senturia recalled an exchange with Ross in 2016 in which Ross allegedly said of their mutually assured destruction, “I am like, literally staring over the edge. My life is over.”
One would expect that in light of that conversation being made public through a book, that investors would question Ross’s report that his fund delivered a double digit annual return (10.61%) the same year his life was over.
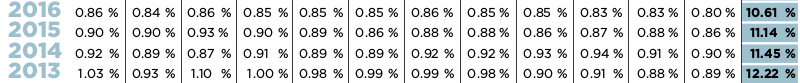
Some actually did question it. deBanked received tidbits of information in the ensuing years, always seemingly off the record, that something was not right at Ross’s fund. There was little to go off other than the unlikelihood of his consistently stable stellar returns. Ross had been an especially popular investment manager with the peer-to-peer lending crowd and a regular face and speaker at fintech events. CNBC also had him on their network several times as a featured expert.
All told, Ross managed to amass nearly $1 billion worth of capital under management before his demise.
In 2019, Ross suddenly resigned. His fund, Direct Lending Investments, LLC, was then charged by the SEC with running a “multi-year fraud that resulted in approximately $11 million in over-charges of management and performance fees to its private funds, as well as the inflation of the private funds’ returns.”
 Yesterday, the FBI arrested Ross at his residence outside Los Angeles. A grand jury indicted him “with 10 counts of wire fraud based on a scheme he executed between late 2013 and early 2019 to defraud investors…” An announcement made by the US Attorney’s Office in Central California revealed that the charges had been under seal for approximately two weeks prior.
The SEC simultaneously filed civil charges against him.
No reference is made to Dealstruck in any of it. The Dealstruck brand was later sold to another company that has no connection to Ross or Senturia where it is still in use to this day. Instead, the SEC and US Attorney focus on Ross’s actions allegedly undertaken with another online lender named Quarterspot. Quartersport stopped originating loans in January of this year.
Ross allegedly directed the online lender to make “rebate” payments on more than 1,000 delinquent loans to create the impression that they were current. Quarterspot has not been accused of any civil or criminal wrongdoing.
The SEC included in its complaint that Ross expressed concern about the scale of loan delinquencies.
“…more loans are going late each month than I can afford and still have normal returns, so that the can we are kicking down the road is growing in size,” he wrote in an email. It was dated February 8, 2015.
It’s a sentiment that seems to disprove his early premise that “the asset class works even when the collection process doesn’t.”
Ross is innocent until proven guilty, but an excerpt of an interview with him in 2014 is now somewhat ironic.
“I [understand] that people end up sometimes in the [industry] who have had colorful careers in the securities space. It doesn’t make it impossible for me to work with them,” he said. “But if they had been in the big house for white collar crime, then that is probably a non-starter.”
Real Estate and Funding Deals With Chris Pepe
August 10, 2020I recently spoke with Christopher Pepe, Head of ISO Relations at World Business Lenders. Pepe explained why WBL’s practice of securing loans against real estate has enabled their business to keep lending and to do deals unsecured lenders and MCA providers are not equipped to handle.
You can watch the full interview here: