
The Road To Training The Best Sales Reps
February 26, 2017
Alternative-finance industry executives tend to agree on at least two basic rules for building a successful sales team: Hire people who know how to sell and never stop training them. Following the second rule requires knowledge and perseverance. The first one takes a leap of faith.
To obey Rule No. 1, companies have to find ways of determining who possesses that elusive quality known as salesmanship, even among inexperienced job candidates. To that end, most firms make an educated guess based on experience, intuition, common sense, high hopes and the good graces of Lady Luck.
“We look at personality traits,” says Zach Ramirez, a World Business Lenders vice president and manager of the company’s Costa Mesa, Calif., branch. “We’re looking for an outstanding person – the highest-caliber person we can find. They should be hard-working and competitive. You can underline ‘competitive.’ They should have a fire inside them.”
“We want someone who’s hungry for money and is going to be a go-getter, says Chad Otar, CEO and executive funding manager at Excel Capital Management Inc. “It’s a feeling that you get when you talk to them. You can tell when a person is going to sit back and not do anything.” In addition, good candidates aren’t intimidated by the challenge of learning how the industry works, he notes.
 “It’s really about how you connect with someone,” according to Amanda Kingsley, who owns Options Capital and also works as a sales training consultant. “Even over the phone, you need to treat people with understanding. You need to inspire the trust that you could provide the advisory help they need.” Small details, like remembering a potential client’s daughter just got married, mean a lot, she says.
“It comes down to drive and personality,” says John Celifarco, sales manager at Sure Funding Solutions. He finds there’s not much room for the thin-skinned and it takes a certain kind of person to succeed. “When you find the right people, it usually clicks pretty quick,” he says. “For the people who don’t work out, it usually falls apart pretty quick.”
“I look for strong personalities,” says Isaac Stern, CEO of Yellowstone Capital. “I don’t believe you can necessarily teach someone to sell,” he asserts. “This isn’t an easy sell, so you have to have a Type A personality. They’re on the phone and they’re confident whether they know the product or not in the beginning.” The interview process can “weed out” candidates who aren’t going to find success, he says.
Don’t expect someone with a background in outside sales to find happiness spending eight hours a day on the phone as an inside salesperson, warns Stephen Halasnik, managing partner at Financing Solutions. As a direct financing company, his firm hires salespeople different from those an ISO or broker employs, he says. His company expects salespeople to act as consultants who are knowledgeable about finance and empathetic to small-business owners.
Nearly every company prefers candidates with selling experience, possibly in telemarketing. Some seek reps with a background in selling financial services, but others prefer prospective employees who are new to the industry. “I don’t want to hire someone else’s problem child,” Stern asserts. “I’d like them to learn the way we do things from start
to finish.”
 “Different offices have different cultures, so someone who has worked well in one office might not work well in another,” Celifarco says. People hired from other companies may bring bad habits, he says. They may approach the job in a variety of ways they’ve learned elsewhere and thus prevent the company from presenting a consistent face to the public, he says. “Every company has an identity,” he contends.
Applicants without a sales background sometimes rise to the occasion and succeed, says Ramirez. In fact, one of his top sales managers joined the company with no sales experience. Former entrepreneurs, even those without a sales background, often have a lot in common with other small-business owners and that helps them do well, he notes.
Excel Capital Management seeks salespeople with differing backgrounds for two different types of roles in its sales force, says Otar. Openers work on salary and should have phone sales experience so they’re comfortable on the telephone. Closers, who work for commissions, should have experience at selling financial services products or something closely
related, such as stocks or mortgages, he says.
While good hiring practices bring good employees into the company, they also guard against inviting bad ones into the fold. World Business Lenders uses several third-party companies to perform background checks and pre-employment screening, but most often calls upon ADP, says Alex Gemici, the company’s chief revenue officer. ADP performs evaluations that comply with the laws of the states where the employees are located, he says.
Eliminating unsavory candidates carries special significance in the alternative-finance business, notes Ramirez. “It’s critically important that they have no background issues,” he says. “In this industry there a lot of bad apples out there. It’s important that they don’t infiltrate our organization.”
“It’s very difficult to find loyal guys,” Otar laments. “They come in and utilize all your systems and then you catch them stealing.” In other words, they pass deals along to other companies. Otar has caught three of his closers doing exactly that. “You’ve got to be very careful,” he warns, adding that it’s difficult to spot bad actors because they’re skilled at selling themselves.
Once a company chooses the best candidates, the training can begin. New salespeople always start on Mondays at World Business Lenders, and the company’s corporate headquarters conducts sales training nationwide that day, says Gemici. The full day of instruction originates at headquarters, and new hires at branch locations participate on Skype. Subjects include the industry in general, specific company products and sales tips.
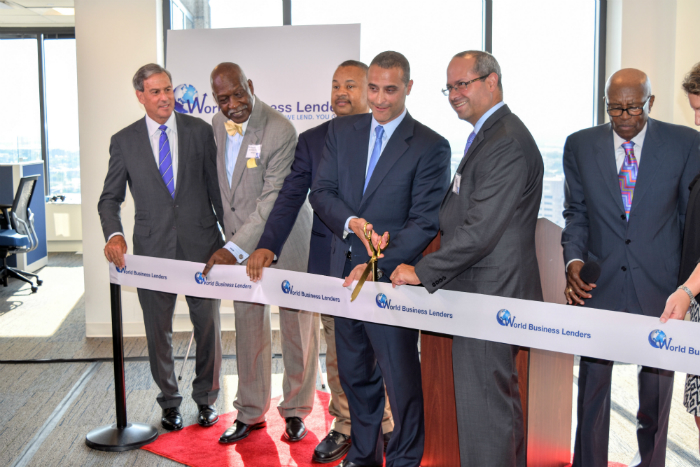
On Tuesdays, the World Business Lenders branches take over the training for a day or more, Gemici notes. That instruction, which lasts as long as the branches decide, can include having the new employees “shadow” more-experienced workers and having crack salespeople listen in on the phone calls of the new staffers as they make their pitches.
In the World Business Lenders office in California, Ramirez continues the training every day of a new employee’s first two weeks on the job. Tuesday and Wednesday of the first week, he spends the full eight-hour day with them. After that, he sets aside at least two or three hours of instruction each day. “I want to err on the side of over-training,” he explains.
From there, education continues as long as employees work for the company, Ramirez says. That can include spot training that he institutes anytime he sees a problem or an opportunity for improvement. Ongoing training also helps salespeople keep up with changes that occur in the industry, he notes.
The sales staff in the California office of World Business Lenders also assembles in a conference room for regular sales meetings. Ramirez picks a rep who’s outstanding at some aspect of the job to deliver a short lecture on the subject at those meetings. A star at prospecting, for example, could explain tricks of that part of the trade and then field questions on the subject. “That way, everybody can learn what everybody else knows,” he says.
For ongoing training at Financing Solutions, Halasnik calls his staff into a “huddle” for 10 minutes every day. They review what deals are pending so that salespeople know what management is seeking and can use that knowledge when they’re gathering data from customers. “We’re looking for reasons to give someone financing that doesn’t fit the cookie cutter approach a bank would use,” he notes. The team also use the huddle to share information about the industry.
At Sure Funding Solutions the sales staff meets every couple of weeks for ongoing training. They talk about some aspect of the sales process, such as opening, closing, dealing with banks, what’s working and what’s not working, says Celifarco. “I’ve been in this business since ’08, and I’m still learning new things,” he notes, adding that changing one phrase in a pitch could get better results.
Ongoing training at Excel hinges on monitoring phone calls to ensure openers are asking the appropriate questions to qualify leads and that closers are working effectively, Otar emphasizes. “It’s a never-ending process to learn what to say at the right time,” he says of his company’s training policies. Salespeople who have mastered the basics can bring their own personalities into their presentations to avoid sounding as though they’re reading from a script and thus foster an organic conversation, he notes. “That’s perfect – it’s golden,” he exclaims.
Kingsley agrees. “Don’t be too ‘salesy,’” she counsels. “That’s the best sales advice I can give.” Nobody enjoys receiving a telemarketing call, she reminds her trainees. Larger companies probably won’t heed that tip because they’re focused on volume, but smaller companies can avoid the “salesy” trap, she says.
Training should also teach originators to avoid industry jargon on their calls because prospects simply may not know the lingo, Kingsley cautions. Closers should learn from their training that knowledge of the customer’s industry can help build a relationship, she says. And knowing the customer’s industry also helps salespeople convey a deeper understanding of creditworthiness to underwriters, she maintains.
Financing Solutions trains salespeople to reveal information to clients through a string of questions instead of merely throwing out statements about the company’s products, Halasnik says. The questions can include how the customer’s business works and how he’ll use the money. That can allow the client to sell himself, and it can help the salesperson explain the client’s situation to the underwriters, he says.
Salespeople should learn to present themselves as professionals and avoid sounding like used car dealers, Halasnik maintains. “They have to understand business,” he notes, adding that training must convey that sensibility because “they don’t really come in that way.” In fact, he maintains that financing Solutions has to persevere in continuing to help the sales staff understand how small-business owners think.
Even though training never ends, it eventually pays off, Halasnik contends. He looks forward to the time – possibly in six months or so – when the roles reverse because his salespeople are picking up so much information that they’re training him. The fact that sales reps are making contact with customers keeps them in touch with the pulse of the industry, he notes.
But problems can arise even with the most persistent training efforts, so it’s also vital to begin the process with employees who are trainable, Kingsley suggests. “Some people listen to you, but then they don’t act on the advice,” she maintains. Others don’t want to expend the effort necessary to research their customers’ industries. “If you’re going to make $10,000 off of a sale, put in the work for it,” she admonishes.
Some companies are hiring lots of salespeople and putting them to work quickly as part an effort to achieve sheer volume, Kingsley says. Instead, she recommends training a smaller number of reps to conduct themselves in a transparent manner that promotes repeat business.
 World Business Lenders allows for a 90-day period to determine whether a new salesperson and the company are a good fit, says Gemici. Turnover occurs during that period, often because the company is growing so quickly that it’s necessary to take on a few inexperienced employees, he says. For salespeople who complete the 90 days, the success rate is high, he notes.
“We like to say six weeks,” Otar says of his company’s probationary period. By then, a closer should be making four to seven deals a week, he suggests, noting that openers should generate 15 to 25 leads weekly and five to seven should be getting funded.
Salespeople can require four months to really catch onto their jobs, according to Halasnik. He finds that he can gauge their progress by the quality of the questions they ask, not by what they say. As they learn the business, their questions improve, he notes.
The effort required to find and train salespeople can tempt some companies to steal good employees from their competitors, but the problem’s no more severe in the alternative-finance industry than in other businesses, according to Ramirez. “I never intentionally poach someone else’s employees, although people have tried to recruit mine,” he says. “Most of these people are clients. These competitors of ours send deals to us so I don’t want to do anything to jeopardize that relationship nor do I think that’s a good business tactic.”
So where are those prospective employees hiding? World Business Lenders employs a full-time in-house recruiter to ferret them out. Excel finds candidates on industry blogs or through general employment websites. Kingsley urges companies to contact colleges to seek out finance majors. Stern says he puts up a post and receives “tons of resumes.”
Wherever the employees come from, one of the keys to their success lies in understanding the customer’s business, Halasnik maintains. “If you only think of your business as money, it could be a little bit boring,” he says. “If you think about who the clients are and how they got there and who their customers are, that’s the fun part of the job.”
The New Normal
January 24, 2017 In March 2014, I wrote the following for DailyFunder.com: I think we are either currently in, or are fast approaching a “market bubble” in MCA. Bubbles never end well…When I see some of the business practices, offers, terms and other aspects of our business today, I am worried…assets are being overpaid for through higher than economically justified commissions …and [funders are] stretch[ing] the repayment term of the MCA or loan even further. I went on to say that this felt to me an awful lot like the subprime mortgage meltdown of 2008.
Like all good bear market prognosticators, I was a touch early in my forecast. 2014 and 2015 were continued boom years for small business alternative lenders (or “small business Alt Lender.” I don’t agree with applying the moniker “online lender” for our industry. It might be sexy, but it’s not accurate.) Loan and MCA terms got longer, loan pricing to the client dropped further, companies grew 100% year over year. And then 2016 happened.
The most shocking event for me in 2016 was the disruption at CAN Capital. They had the most data, the most experience, market dominance, and the most in-depth institutional knowledge. The granddaddy of all of us. Not far behind is the fiasco that is On Deck, the only publicly traded small business Alt Lender. In the past 12 months alone, the stock price has declined by over 40%. And that is after a roughly 50% drop in stock price in 2015. The first 9 months of 2016, driven in part because of market required changes to their business model when they could no longer profitably sell a sufficient volume of loan originations, they have a GAAP net loss of almost $50 million. There have also been a number of other lesser but still high profile failures, shutdowns, and exits from the industry in the past several months alone.
So what is driving this abnormally high rate of failure in the Alt Lending industry? Is it the “New Normal?” And what do I think lies ahead in 2017 and beyond? Before revealing my personal crystal ball again, I will share an anecdote from earlier in my business career.
I was the CFO (and eventually CEO) of a profitable, long-tenured family owned construction company. We had a working capital credit line from a major bank secured by a first position lien on our accounts receivable. The credit line was also personally guaranteed. We borrowed from the credit line for three reasons. For cash flow, when our receivables paid more slowly than expected; we had tax payments due; or we purchased a large piece of equipment. We always paid back the draw on the credit line as quickly as we could, to keep interests costs low, to impose cash management discipline, and to create future availability on the line once repaid.
 The credit line was for one year. It was always renewed. But I was frustrated to have to go through an annual underwrite process with our bank, despite the personal guarantee, consistent profitability, and that we always paid back our draw on the credit line. Our banker (patiently) explained to me that economic cycles changed, and medium sized businesses – we had about 200 employees – suffered ups and downs and sometimes became financially distressed and even went out of business. The bank wanted to protect their position and not overextend the term of the credit line.
When I started RapidAdvance in 2005, I drew on my personal knowledge and previous experience as a borrower. The products we offered made sense based on our customer profile which was main street small business. We needed to protect against economic cycles and the high rate of small business failure. The maximum term offered by any company in 2005 was 8 months, at that time only for an advance product (future purchase and sale of credit card receivables), not a loan. Payment was received daily through a credit card split, thus allowing for a future capital advance (renewal) within about five or six months as the open advance was paid down. Cash advances could be used for taxes, equipment purchases, or business expansion. The price of the product reflected the risk of the credit offered.
What many in the small business Alt Lending industry seem to have forgotten, or never learned, is that our business is fundamentally a subprime credit industry. We are either lending to subprime borrowers, because of either the personal credit of the owner or the balance sheet of the borrower, or if the credit is strong and the business is more substantial, the loan itself is a subprime risk because we are at the bottom of the capital stack – behind the bank loan, the business property mortgage loan, the other personal guarantees of the owner, the factoring company, etc. We are taking the most risk. To offer two and three year terms and to try to pretend to get to “bank like” rates is, in my opinion, committing lending suicide.
At Rapid, we were dragged kicking and screaming into slightly longer term and lower cost products in order to stay competitive with certain customers. But we have kept that pool of customers as a very small percentage of our overall receivables.
Going into 2017 and beyond, I see five major trends. First, terms will get shorter, prices will increase, and offers will become more rational. That is already happening. Second, capital to this industry will become less available. The best companies with proven data driven models, consistent underwriting, a strong balance sheet and predictable loss rates will get financed. The days of easy money chasing this space are over. Equity will be particularly hard to come by.
Third, there will be continued disruption of funding companies. Companies will consolidate and some will disappear. On Deck may be in for a big challenge. They had a tremendous cash burn converting their business model to more balance sheet financed instead of originating and selling loans. Their market cap today is approximately book value, i.e. if you could buy up all the shares of the company at today’s trading price that would be roughly equal to their cash on the balance sheet and the value of their net receivables. The next two quarters are crucial for them to show the market they have turned the corner to become a self-sustaining lender. I am not optimistic, but I am rooting for them to succeed as it is in the best interests of the industry.
 Fourth, stacking will continue to be an issue. I believe that the legal system over the next few years will bring some semblance of order to this industry scourge. At Rapid we have taken an aggressive legal stance against stacking, with some success in the courts. The challenge is that each situation is fact specific, and to prevail in a claim of tortious interference, the first position lender has to prove damages. I think that an unrelated decision at the end of 2016, Merchant Funding Services, LLC vs. Volunteer Pharmacy in New York State, could be a game changer. Because of the form of contract and the business practices in Volunteer, the judge ruled that the transaction constituted criminal usury. Knowing the business practices of the stackers, specifically the practice of writing an agreement that pretends to be a sale and purchase of future receivables but is in fact a loan, which is the basis for the judge’s ruling in Volunteer, I can see lawyers seizing on this precedent to help overstressed small business owners attempt to void their stacked loan agreements. The small business would first block the stacker’s ACH, claim the contract is void because of criminal usury, and then sue the stacking company. There could also be class action lawsuits like we saw a few years ago in California – bundle together a number of these claimants and go after the deep pocketed investors and banks that finance the stacking companies. The State’s Attorney General in New York may take a public policy interest in these types of loans. Once the dominoes start to fall, the costs of stacking – litigation and unpaid loans, in addition to proactive claims for damages – could be enormous for both the stacking companies and their owners and investors.
 Lastly, and to my great pleasure, I think we will stop hearing small business Alt Lenders calling themselves “Fintech.” I think we will see the beginning of the demise of fully automated, no manual touch funding. At Rapid we have data and risk and pricing algorithms but we have always had an underwriter at a minimum review every file. At conferences when I have presented or participated in Fintech panels I always referred to Rapid as a technology enabled, non-bank small business lender. Now even On Deck describes themselves in similar terms.
I titled this post “The New Normal.” In the classic Mel Brooks movie Young Frankenstein, Dr. Frankenstein sends his assistant Igor to steal a brain from a cadaver to implant into his monster. But Igor accidentally drops the genius brain he was supposed to steal, and brings the doctor a different brain without telling him. When the monster awakes and has the personality of a psychotic five year old, Igor tells him he brought him a brain that was labeled “normal” instead of the one he was supposed to steal. It was, as Igor read it, “Abby Normal.” Abnormal, I believe, is the “New Normal” we will be dealing with in 2017.
New Regulations, Section 1071 of Dodd-Frank Among Them, Temporarily Frozen By Executive Order
January 23, 2017
Update 2/1/17: Disagreements abound over whether or not Trump’s recent regulatory freeze can affect the CFPB. According to the WSJ, part of this stems from the CFPB’s uncertain status as an independent agency after the the recent court decision in PHH Corp v. CFPB. “The CFPB is following a hiring freeze ordered separately by the Trump administration,” the WSJ states. This may be a signal that they do not feel totally insulated.
Section 1071 of Dodd-Frank had expanded Reg B of The Equal Credit Opportunity Act and granted the CFPB the authority to collect data from small business lenders. It’s all-encompassing considering that it oddly defined a small business lender as “any entity that engages in any financial activity.”
Although Dodd-Frank was passed in 2010 and the CFPB created in 2011, Section 1071 has been lying in wait. But just a month ago, the Federal Register said that its implementation was under way, with a pre-rule timetable of March 2017. “The Bureau is starting its work to implement section 1071 of the Dodd-Frank Act, which amends the Equal Credit Opportunity Act to require financial institutions to report information concerning credit applications made by women-owned, minority-owned, and small businesses,” it says.
And that work is no doubt a big undertaking, especially if it is really supposed to cover any entity that engages in any financial activity.
“The amendments to ECOA made by the Dodd-Frank Act require that certain data be collected and maintained, including the number of the application and date the application was received; the type and purpose of loan or credit applied for; the amount of credit applied for and approved; the type of action taken with regard to each application and the date of such action; the census tract of the principal place of business; the gross annual revenue of the business; and the race, sex, and ethnicity of the principal owners of the business. The Dodd-Frank Act also provides authority for the CFPB to require any additional data that the CFPB determines would aid in fulfilling the purposes of this section.”
Fear exists in the commercial finance community that the CFPB will use such data in a misinformed way to levy penalties and exert control over business-to-business transactions even though its statutory power is limited to just the collection of information.
Although the CFPB is still in the information gathering stage on Section 1071, the President’s regulatory freeze is likely only the first step of many to delay or dismantle their rules. And that’s at a minimum. Presently, the CFPB is faced with the threat that Trump will fire its director or abolish the agency altogether. There is strong support for this among Republicans, especially given that a federal court recently held that the CFPB’s structure is unconstitutional. In PHH Corp v. CFPB, the court offered two ways for the agency to come into compliance with its order, either reconfigure into a multi-member directorship or yield the director’s power to the President of the United States. Sitting CFPB Director Richard Cordray rebuffed the order as “wrongly decided” and declined both. His term ends in 2018.
The CFPB’s brash refusal to make concessions or accept court orders has made it a prime target of Trump’s administration. Because of the battles with the agency still to come, it is possible that Section 1071 may not begin to see the light of day for at least another four years.
If You Don’t Make Loans, You’re Not a Lender (And definitely not a ‘direct lender’)
January 19, 2017 Small business owners in multiple states are arguing that the contracts they engaged in were loans despite the agreements specifying otherwise. In one case with multiple defendants that was filed two weeks ago in federal court, the plaintiff attached emails from the ISOs and funders they allegedly communicated with as evidence, several of which purportedly used the words “loans” or “lender.” That on its own might not be so bad except that the plaintiff entered into contracts for the purchase of future sales, in which case the words would not make sense.
While that matter and others will be litigated and decided on the merits, this should be a wake-up call for any ISO or funder that thinks the use of proper terminology is best left for lawyers and fine print in contracts. A court ordered recharacterization of a contract could have very negative consequences (if you want to know what kind, speak with an industry attorney).
Imagine working for a small ISO and one day being subpoenaed to do a deposition and potentially facing liability because of something you said on the phone or in an email. The easiest way to avoid this is to use the proper terminology at all times. If the product you sell or underwrite is a standard merchant cash advance (purchase of future sales), then it will never make sense to say loan, lender or any words related such as repay in any communication regardless of whether or not it’s with a customer or internally. Calling yourself a “direct lender” for example, is especially illogical.
If you’re at all confused, seek out your company’s manager or compliance officer for additional training. Another helpful resource is Merchant Cash Advance Basics, A certification course offered by CounselorLibrary and deBanked to help explain the differences between loans and MCAs. Given the challenges taking place in courts around the country, it’s never been more important to be knowledgeable on the products you offer.
CAN Capital is Changing the World’s Most Expensive Tire
January 16, 2017
Acting CEO Parris Sanz told the WSJ that what’s happening at CAN Capital right now is akin to changing a flat tire. “We hit a bump in the road and blew out a tire,” Sanz said. “We just need to change out the tire, and we’ll be back on the road.”
But sources say that the company is in the midst of trying to sell off assets including its loan portfolios to raise cash in a hurry. In the span of a few weeks the company has let go of more than half of its employees, has suspended funding new deals, put its top executives on leave, been sued by a shareholder, and suffered a rapid amortization event with its $200 million bond deal. That’s on top of a breach that the WSJ reported with CAN’s $650 million credit facility led by Wells Fargo. A spokesperson for Wells told me they could not provide any comment or information on the matter.
And CAN’s issues aren’t the result of a changing economy, but rather internal systems that couldn’t keep up with their innovations. They’ve even hired a restructuring company to assist them through this crisis. It now being more than a month and a half since the story first broke, the WSJ puts the amount CAN is trying to raise “to strengthen its financial position” at $100 million.
If this is how they go about changing a tire, it may be time they sign up for AAA Roadside Assistance. For the merchant cash advance industry, their predicament is one of the biggest events of the decade by virtue of their history, size and renown. The company has funded more than $6 billion to small businesses since they launched in 1998.
Consider that just a few months ago, CAN was seemingly riding high as it promoted its new lending transparency initiative as part of the Innovative Lending Platform Association. And in July, Sanz represented the MCA & small business lending industry in a congressional hearing dedicated to financial institutions and consumer credit.
CAN’s top competitor is OnDeck whose stock has only inched up 8% since November 29th.
A spokesperson for CAN reiterated that this was an issue that they self-discovered and self-reported. “In the absence of information, people are making incorrect assumptions,” she said. “It affected about 3% of total assets in the portfolio under our senior line. It’s a manageable situation and one we are working through as we position ourselves for success in 2017.”
MCA Company Files Suit Against Debt Settlement Company
January 16, 2017Plaintiffs Pearl Gamma Funding, LLC and Pearl Beta Funding, LLC (Pearl) aren’t happy with what a debt settlement firm is allegedly telling their customers, according to a complaint filed in the New York County Supreme Court in November.
“Creditors Relief LLC researches customers who have entered into Merchant Agreements with Pearl, solicits them throughout the country, and advises them to breach their contracts with Pearl,” plaintiffs allege. They also cite an example in which an employee of defendant allegedly told a customer “that Pearl was engaging in illegal activity and its Merchant Agreements were unenforceable.”
Pearl’s causes of action against the defendant include tortious interference with contract, defamation and permanent injunction.
Creditors Relief, based in Englewood Cliffs, NJ, denied the allegations in their response but has asked the court to declare Pearl’s contracts with its customers unenforceable nonetheless.
Due to the nature of pending litigation, neither party was asked to comment.
Confessions of a Fintech Chief Data Scientist
January 8, 2017 My name is Justin Dickerson. For most of 2016, I was the Chief Data Scientist at Snap Advances (Snap), a funding company of merchant cash advances based in Salt Lake City, Utah. I can’t discuss my awesome work at Snap for obvious reasons. And fortunately, I don’t need to in order to make the key points I want to convey through this article. That’s because I’ve also been a senior level data scientist at two other companies, and I’m also a well-regarded statistician who holds one of the most prestigious credentials offered by the American Statistical Association.
One discovery over the past year prompted me to start collecting my thoughts for this article. I was looking at the financial performance of On Deck Capital (the largest company in the alternative fintech industry which is also publicly traded) through the first nine months of 2016 relative to the same period in 2015. Gross revenue increased more than $22 million while net income for the same period fell nearly $50 million. I’m not an accountant, but that doesn’t sound good to me. And let’s face it, this fact doesn’t surprise anyone in our industry, especially given what’s happening at CAN Capital. But one interesting and overlooked fact is worth considering. According to my Linkedin search, there were between 30 and 40 data scientists (all levels) working for On Deck Capital during the same time period in which they lost $50 million. So, not only does On Deck Capital lose a lot of money, it appears they need a lot of intellectual horsepower to figure out how to do so.
And here we are today. We’re looking at an industry full of companies trying to navigate the abyss of hyper-aggressive originators and spiraling default rates. If you’re a Chief Data Scientist for one of these companies, you’re undoubtedly feeling the heat from your management team. The problem is simple. How do you grow your business (or even stabilize it) in an environment where you have to take too many uncomfortable risks? We’ll ignore the fact this question has plagued much larger industries for many years (e.g., trying to compete against Wal Mart in the retail space). Boards of Directors in alternative fintech have short memories and believe this is a unique problem to their industry and era. As a result, data scientists are at a premium as they’re seen as key players in how to resolve this crisis and steer their companies to safe harbors. Well, here is my opinion. They’re dead wrong, and here is why.
Data Scientists Are Tactical, not Strategic
This statement may end up being the most controversial thing said in the data science industry this year. But let me make my case. Of those 30-40 data scientists working for On Deck Capital, more than 80% of them have a Master’s degree in a field of study synonymous with data science. Specifically, many of them attended Columbia University’s Master’s degree program in Operations Research. The four required courses for that degree are: Optimization Models and Methods, Introduction to Probability and Statistics, Stochastic Models, and Simulation. From there, students can choose from one of six concentrations (all but one of which are targeted toward quantitative methods). Further, students selected for this program already have highly refined quantitative skills as demonstrated by the pre-requisite courses for admission (e.g., multivariate calculus, linear algebra, etc.). So, in essence, the program takes really smart quantitative people (quants) and makes them even smarter quants, while sprinkling in 6 elective courses which may or may not provide an opportunity to learn something about the “real” world of business.
Make no mistake, the students attracted to programs such as these generally aren’t the professionals you send to meet with investors and pitch them on new strategic directions for a company. They are the professionals who sit in cubicles and spend their days writing code. They are experts in programming languages such as R, Python, Java, Scala, and many others. Ironically, they are enslaved to similar rules which govern the same supervised machine learning algorithms they create each day. They aren’t allowed to “get out of the box” and see the “forest through the trees.” If I’m portraying them as a bit robotic, that’s intentional on my part.
I don’t want to leave the impression data scientists can’t think for themselves. Specifically, those who earn a PhD are known to have such skills and are often praised for their abilities to rise above the technical chains of their existence and offer strategic direction to an organization. But they are few and far between in the data science factory found deep in the bowels of companies like On Deck Capital. Instead, more and more alternative fintech companies seek out the same “cookie-cutter” data scientist who can check off the same boxes on the hiring list. This means the data scientist role is relegated to a part of the company lacking diversity of thought, creativity, and the organizational respect needed to save a company from itself.
The Law of Diminishing Returns
One of the most intelligent questions asked of me within the alternative fintech industry was, “do we really have enough data to justify so many data scientists?” As a Chief Data Scientist, you always want to answer that question with an emphatic, “YES!” Even better, you may tell your management team you need even more data scientists to make a “real and lasting contribution to the company.” After all, the existence of your team depends on it. But when you’re away from the management team and thinking about the structure of your department, the honest Chief Data Scientist knows the company is at risk of experiencing the law of diminishing returns.
All of us can recognize the law of diminishing returns from our freshman year Economics course. In short, it’s the concept of achieving less than a one to one relationship between an additional unit of input relative to the resulting measured output. For example, the reduction in default rate for a financial product is hardly ever proportional to the number of data scientists employed by the company to predict default rates. In fact, I would argue once you have more than two or three data scientists, even the largest organizations would have a difficult time justifying the payroll investment based on proportional gains in default rate management.
So, why do companies like On Deck Capital have so many data scientists? I believe it’s more akin to the comfort food we all like to eat in the winter. There is hardly anything as satisfying as my grandmother’s homemade chili during a cold Utah night. And the more of it I get, the warmer I feel! The problem is the chill of winter eventually fades and the light of day shone on financial statements eventually begs the question of whether we’ve simply eaten too much.
Make no mistake, NO organization needs endless amounts of data scientists to be successful. In fact, I would argue two or three excellent data scientists armed with superior data science/machine learning platform technology such as those offered by IBM, Microsoft, or DataRobot is more than enough to guide an organization to success. The key when thinking about staffing a data science department is to think in terms of credibility. If I have three data scientists each armed with PhD training, 15 years of industry experience, and the tools (such as a great machine learning platform) to do the mundane parts of data science usually done by legions of Master’s degree data scientists, am I more credible in the organization than I am with 30 quants who all grew up in an economy where nothing bad ever happened to financial institutions? If you want your data scientists to help your organization, you’ve got to be willing to let them into the board room and present digestible recommendations for action. So the question becomes, do I have a team that is credible enough to meet such a standard?
The Supremacy of Domain Expertise
I learned a lot during my time as a Chief Data Scientist. Since leaving Snap, I’ve established two companies. The first is Crossfold Analytics. This is my data science consulting company. We only serve the fintech industry and we spend most of our time building real-time machine learning prediction services for small to mid-sized fintech companies. And I think we’re darn good at it! The second company is Crossfold Capital. This is my independent sales organization (ISO) focusing on merchant cash advance, business loan, and factoring products. It was when I established Crossfold Capital that I learned the most valuable lesson of all about data science in alternative fintech. Nothing will ever replace the experience of working in the trenches of the business (what I call “domain” expertise). In alternative fintech, this is generally working within the trenches of a sales organization. If I could go back in time and start over as Chief Data Scientist at Snap, I would start my job by underwriting files and selling merchant cash advances for a month. Absolutely nothing I learned in math, statistics, or any quantitative subject can replace what I’ve learned running my own ISO in just the past two months. I wish every alternative fintech company would adopt a training program for data scientists that allowed them to spend their first month in the field calling on clients and working with potential customers. If you understand the business, you can bring immeasurable value to your company by blending that understanding with your technical skills as a data scientist. I truly believe such an approach could take the power of a data scientist and magnify it three-fold. Otherwise, you end up having a rogue department of quants that people in the trenches of the business either don’t understand or don’t trust.
My Recommendation to Alternative Fintech Companies
Based on what I’ve learned as an alternative fintech data science professional, I would make three recommendations to all companies in our industry. First, hire diverse talent. It’s imperative a data scientist knows enough about coding to be effective at building predictive models. But I would trade extensive coding expertise for a data scientist who also had a Bachelor’s or Master’s degree in business administration. We don’t need an army of robots in data science. We need gifted thinkers who also happen to have advanced technical skills. Second, don’t “over-eat” even though it can be cold outside. More data scientists aren’t going to solve your problems. In fact, hiring the same type of data scientist only encourages “group-think” which can actually be very detrimental to your organization. Focus on building a credible data science department, not a massive data science department. Finally, put your smartest people in the dirt of the business. Have them spend a week underwriting files. Then send them to sell your products with one of your ISO managers. Don’t treat your data scientists as fragile figurines. As a good friend of mine from Texas says about his gun collection, “they may be worth a lot, but they’re so dirty from hunting you wouldn’t know it!”
I hope my confessions help your organization navigate both fair seas and choppy water.
My Marketplace Lending 2017 Projections
January 8, 2017 LendIt co-founder Peter Renton has projected that there won’t be any new industry IPOs this year. While I don’t know if I’d say he’s wrong (a year is a long time), one thing that has changed since 2014 is a shift away from the “tech” label. When OnDeck went public, they positioned themselves as a technology company. Today, they more closely identify themselves as a non-bank commercial lender. Lending Club too was a “tech company.” Now they might be more appropriately characterized as an online consumer lender, especially since their competitors are traditional financial institutions like Discover Bank and Goldman Sachs. So the public markets in 2017 may not be ready for a tech company that can lend but they may be ready for a lending company that has tech. The difference is real.
On regulation, while a Trump presidency may mean that federal regulatory threats will subside, my projection is that the judiciary system will instead play a prominent role in 2017. Whether it’s state courts or federal courts, expect the rules of engagement in marketplace lending or merchant cash advance to become more clear than ever before.
I think it would be easy to predict consolidation in 2017, so more than that, I believe some companies will just wind down and others who arrived too late to the game will just move on to something else. That’s not necessarily a pessimistic outlook since this will give the more serious players a chance to flex their muscles and continue strong growth. This is a natural cycle in any industry that experiences a rapid growth phase.
There will be at least one black swan event. We don’t know what we don’t know.
Lastly, if you want to come up with your own predictions you should attend the 2017 LendIt Conference this March in NYC as it’s the best opportunity to take the temperature and size up the future. I have been to the last three annual LendIt USA conferences and in my opinion each has set the tone for the rest of the year.
You can get 15% off the registration price with Promo Code: Debanked17USA.