Business Lending
A Journey Through Collections With Erica Gilerman
September 8, 2026“Within two weeks, I closed my first deal. I just clicked in the industry,” said Erica Gilerman.
Gilerman wasn’t talking about funding a deal. She was talking about collecting on one.
“Closing the deal on our end means that we have a signed, sealed, and delivered stipulation, one that our client is happy with, and one that truly makes sense financially for the merchant as well,” she said.
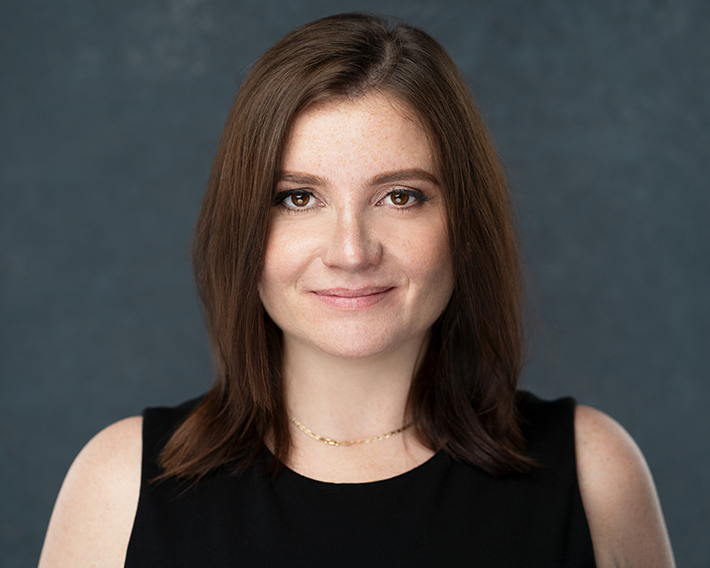
Conventional wisdom in the small business finance industry has long held that anyone can put money out the door; getting it back is the hard part. Gilerman currently serves as Chief Legal Officer of that hard part, working for Triton Recovery Group in South Florida.
Talk to anyone at Triton and they’ll probably tell you that successful collection begins during the underwriting process, before a deal is ever funded in the first place. In a taped interview deBanked conducted with Triton CEO Leo Vargas in 2024, he said, “The underwriting process to me is the most important piece of getting a deal done in the industry.” Vargas offered examples, saying that it’s critical to know from the outset what merchants plan to use the funds for and that the terms of any deal should be set in accordance with a merchant’s anticipated receivables, not deposits.
Today, Triton has 75 employees. But when Gilerman was being recruited to work there in 2021, the company had only six. Vargas was looking to add an attorney to his then-fledgling traditional commercial collections firm, which was focused entirely on the merchant cash advance industry, and he posted an ad in the New York City market.
“I will never forget… it was very interesting to me because it was in all caps and it said ‘COLLECTIONS ATTORNEY, NEW YORK,'” said Gilerman.
She answered the ad, met Vargas in New York, and received an offer. There was just one catch: She had to spend a month training at Triton’s Miami office to learn its particular niche of collections. That required a significant sacrifice, time away from her family, but she decided to take a chance and then determine whether the job was right for her. She started in July 2021 as the firm’s General Counsel.
“Within two weeks, I closed my first deal. I just clicked in the industry,” she said. “Between my accounting background—I understand how the factor rates work, I understand how businesses operate, I take a very unique approach to everything in the sense that I will collect in a way where I put myself in the debtor’s shoes.”
Gilerman, the daughter of immigrants, was born in Brooklyn, New York, and she attended Madison High School in Brooklyn. She was accepted into the school’s law program, which had been created by former Supreme Court Justice Ruth Bader Ginsburg. Ginsburg, herself a Madison graduate, had created the curriculum.
“My love for law really kind of came to play there, and I learned a lot from that program,” Gilerman said, “and that’s why I’m very proud to say I’m a New York City public school graduate, and that’s how I fell into law.”
Gilerman faced a personal family tragedy as she began college at Pace University, around the same time Lehman Brothers collapsed. Pace’s campus in Downtown Manhattan had a front-row seat to the turmoil unfolding across the financial system.
“I will never forget that in that moment I realized I need to find a career that will not keep me into some sort of niche, because 25 years from now I could be one of those people that was carrying boxes,” Gilerman said, “and they had nowhere to go and nothing to do, and it was a very eerie dynamic being on Wall Street at the time.”
Gilerman initially intended to pursue a career in public accounting as a result but ultimately swerved back toward law. After becoming an attorney, she worked in employment litigation before moving on to collecting medical debt for hospitals in New Jersey.
“You have to have a specific type of personality to be in collections, especially as a woman,” she said. “I would candidly say I would never expect myself to be in collections. That was not my goal in law school, but I would not change it for the world now. This is exactly the niche industry I need to be in.”
Part of that certainty came from finding the right person to work with.
“I will say that I learned most of the MCA space, especially on the front end side, from Leo. He taught me the collections mindset for commercial collections, and we just clicked in a way that it was just a great synergy from the beginning.”
Triton was still quite small at the time. When Gilerman visited the company’s original Miami office, they had to set her up in the break room. By the end of 2021, however, the COVID lockdowns were finally beginning to dissipate nationwide, and the company hit the gas pedal by sponsoring a conference that December in New York: Broker Fair.
“We were able to expand and start hiring more after the very first deBanked [conference] that I attended, which was December of 2021,” Gilerman said.
By then, her mind was fully made up. She and her family moved to Miami two weeks after the conference. Five years and nearly 70 additional employees later, spread across two states (Florida and Texas), she has since become the company’s Chief Legal Officer.
In those early days, Gilerman was still trying to wrap her mind around the financial product Triton’s clients worked with. She said she came to really understand “that without the MCA industry, there is no such thing as a mom and pop shop anywhere in this country and it really changed my perspective of what alternative finance as a whole is.”
Triton’s collection practice handles MCA, commercial loans, and equipment financing on a contingency basis. Ask the team a question about underwriting and they’ll readily offer an opinion. They’re only interested in legally enforceable paper.
The latest frontier in collections includes dealing with merchants who have turned to LLMs to fire off letters, emails, and demands, often containing incorrect information or citations to the wrong statutes. It has become commonplace to see merchants effectively act as their own attorneys with the help of AI, or even claim that AI is representing them.
“I see a lot from ChatGPT and Claude there, and the problem is that they continue to just say the same thing over and over,” she said. “You could tell by the tone because no one’s actually telling them to make it sound like themselves.”
Even on phone calls, merchants may attempt to bring AI agents onto the line with them.
On the flip side, collectors can use AI too. In a recent social media post, Triton CEO Leo Vargas said, “The best agencies will use AI to eliminate repetitive tasks, improve compliance, analyze consumer behavior, optimize account placement and provide collectors with better insights before they ever pick up the phone. Collections has always been about people. AI simply gives those people better tools to succeed.”
Vargas also referenced Gilerman in an email to deBanked. “Five years ago, [Gilerman] took a chance on Triton and joined us during an important stage of our growth,” he said. “Since then, she has grown alongside the company and worked her way to becoming our Chief Legal Officer and a key member of our executive leadership team.”
“Collections, especially the MCA space, this is us playing chess,” Gilerman asserted. “And for us, a checkmate is getting that payment through the door, making our client happy, allowing our client to then redeploy those funds.”
Quickbooks Capital Originated $1.9B in Business Loans Last Quarter
September 2, 2026Intuit’s Quickbooks Capital originated $1.9 billion in business loans for its 4th quarter in FY 2026, which ended July 31.
“In capital, revenue growth continues to be driven by working capital loans to small businesses,” said Sandeep Aujla, Intuit’s CFO during the quarterly earnings call. “Loan volume through QuickBooks Capital increased 54% to $1.9 billion this quarter. The Q4 deceleration in capital revenue growth is due to a deliberate increase in the mix of loans we sell through our forward flow partners, which have a lower revenue yield.”
Intuit is among the largest online small business lenders in the country.
An SMB Financing Brokerage Experiences Strong Growth in a Changing Digital Marketing Era
August 25, 2026 “You will really have trouble in the long term growing out an SMB financing brokerage if you don’t have a robust digital marketing strategy in place.” That’s what Zack Fiddle, co-founder and CEO of CapFront, told deBanked in early 2023, before the AI revolution swept across the internet. The company has kept up so well, in fact, that it recorded a three-year growth rate of 124%, landing it at No. 2,607 on the Inc. 5000 list in 2026.
“This year we’ve made a big push on strategic partnerships and affiliates for lead acquisition,” Fiddle told deBanked just this month. “If you do some quick Google searches or LLM searches for top business loans and top financing providers, you’ll find us on a lot of those rate comparison chart lists.”
Fiddle said that in previous years, CapFront hadn’t really delved into that style of marketing. More recently, however, the company has gotten into a rhythm of leaning on key relationships with a broader reach than CapFront has on its own—and has been leveraging them with considerable success.
“Obviously AI has come in, it’s really changed the landscape for digital marketing, especially in the SEO space,” he said.
Fiddle is not alone in that observation. Some of the larger online customer aggregators in finance, including publicly traded companies, have reported similar trends over the last 18 months, that traditional online search engines are not as dependable as they used to be.
“Diversification is always really important,” Fiddle said. “We have a number of different strategies beyond affiliate and partnership lead acquisition to try to find the most high quality and diverse leads, and that’s been a main focus for us this year.”
Along the way, they’re using every new technology available.
“Our Claude Cowork bill has definitely increased exponentially over the past few months, but I’ll just say this, I think that it’s allowed us to move significantly faster than we had in prior years,” he said.
For example, a major project initially expected to be completed by the end of the year accelerated to the point that it is now nearly finished.
“Things, are just moving a lot faster and if you have the right people and allocation of resources at your disposal, you can make things happen pretty quickly,” he said.
While there are numerous ways that “AI” is doing “cool and interesting” things at the company, Fiddle volunteered one of the more exotic use cases CapFront has begun rolling out.
“For the sales enablement’s part of it, we’re utilizing our VP of Sales Training’s mind as [a] sales coach.”
It is what it sounds like. They’ve essentially encapsulated a working replica of an employee’s mind into an AI chatbot that anyone at the company can interact with.
“I ran all sorts of tests on this myself and it’s just really cool to see, like I feel like I’m talking to this guy,” Fiddle asserted, as if such capabilities are simply to be expected these days.
The AI VP bot was given access to hundreds of thousands of the company’s sales call transcripts, with the real VP’s feedback and advice on those calls modeled into it. That’s the most basic way to describe it but it’s actually considerably more built out and complex.
“I’m able to do some mental exercises now and spit out some ideas that maybe a couple years ago I had in the back of my mind but I just knew they weren’t really in reach with what we had at our disposal,” Fiddle said. “But now it’s starting to get to the point where I feel like if I can imagine it, I could build it.”
For all the fanfare around technology, Fiddle acknowledges that one thing hasn’t changed: a business owner’s dependence on human interaction to help navigate financing options. CapFront can do everything in its power to make the process as efficient and user-friendly as possible, but there is still a personal side to it.
“You still want to be able to give them access to a human at the end of the day, because human relationships are what drive customer relationships, not self-servicing. I guess for some borrowers, maybe they like that, but I think in my experience, even this year in 2026, the majority of borrowers want to speak to a human.”
From the New Kids on the Block to #668 in the Country
August 21, 2026 “I work 100 hours a week. I’ve been doing that for four years and eight months, and my top sales guys work anywhere from 60 to 80 hours a week,” said Frankie DiAntonio, CEO of Lexington Capital Holdings, a small business finance brokerage headquarterd in Port Jefferson Station, Long Island.
It’s a grind that he literally dedicates seven days a week to.
“Every day. I do not miss a day. Even holidays, Christmas. I’m still here. I go see my family, but I make sure that I wake up earlier those days. I’ll be here from like five, six a.m. to like whenever…” he added.
DiAntonio recently turned 27 years old, and he calls the sacrifice—one of total dedication to success—an investment. To his credit, he already has something to show for the effort. His company just placed No. 668 on the 2026 Inc. 5000 list after recording a whopping three-year growth rate of 514%. He says he ended up being the second-youngest CEO to make the list.
The earliest mention of DiAntonio on deBanked was recorded in April of 2022, when his company had only been in business for three months and he was still almost completely new to the industry. In a quote he supplied at the time, he called Lexington Capital “the new kids on the block.” Now, with close to a hundred employees and a reputation for being one of the most in-demand brokerage partners in the business, the company can point to its system as a model that yields results.
“There’s like a Lexington way around here, and if you don’t kind of buy into what we’re doing around here, it’s kind of hard for you to succeed,” said DiAntonio. Most of the Lexonites who work there and have bought into the system are 20-somethings like DiAntonio. Part of that means they need to put in the effort to become great at a rapid pace, especially when much of their competition may have more than a decade’s head start in experience.
“The only way to shorten the gap of getting really good at sales very quickly is to work as many hours as humanly possible on your craft,” said DiAntonio. And so those around him go all-in and embrace a lifestyle that’s not always understood by their peers. Outsiders may see sales, long hours, and an industry that moves at lightning speed and subtly preach that they should prepare a backup plan if it doesn’t work out. DiAntonio says there is no backup plan. The plan is Lexington.
“As an entrepreneur, I don’t think that you can have a backup plan because I’ve noticed in life, and not even just my life, but others, that if you don’t have two feet in to do something, you won’t be successful,” said DiAntonio on this subject. “If you always have in the back of your mind that this might not work out, and have an exit plan, an exit strategy, I’ve seen that those people never really seem to work out.”
Less than a year ago, deBanked was invited to cover the ribbon-cutting ceremony for the company’s new 16,000-square-foot office, where some of the old hands who had been with DiAntonio from the beginning, along with new recruits, expressed an unbridled optimism about the work culture there. DiAntonio credited a number of his very first hires as integral to everything that has happened since inception.
“Those first few hires that you have are so key for the future trajectory of your company because they’re going to set the tone and the foundation and the culture for the rest of the company, like Corey [Digi], Ryan [Showe], and my sister [Nicollete DiAntonio] care so much that it makes everyone else care,” he said.
It’s worth mentioning that Corey was one of six finalists in deBanked’s Broker Battle in 2024, and Ryan won the entire competition in 2025.
But what’s the secret sauce to funding deals beyond long hours and company culture? When it comes to customer acquisition, they have “a good crossbreed of everything.”
“…cold outreach still works, paid ads still work, cold emailing still works,” he says, while adding that they spend about 20% of their profits trying out different things, including technological enhancements. Some of those efforts involve AI and are designed to move deals from their intake systems to funding with the appropriate partner in the shortest amount of time possible. When merchants find them through social media specifically, they tend to find them on Facebook, LinkedIn, and YouTube, in that order. But DiAntonio said Google still dominates the online channel for business owners seeking capital. It helps that when prospective customers find Lexington there, they also see a perfect 5-star rating aggregated from more than 1,100 reviews.
As for the plan from here, DiAntonio said the next milestone they hope to break is $100 million in annual revenue, and to eventually conduct an IPO within five years.
“We got a lot of eyes on us,” DiAntonio said. “There’s a lot of people who want to invest in Lexington at this moment in time.”
Customer Experience, Personalized Service Makes Small Business Finance Brokerage One of the Fastest Growing in the Nation
August 17, 2026 “I would say 90% of all of our interactions we send out a Zoom link, and we do a video call,” said Edward DeAngelis, CEO of QualiFi, “We call it our discovery call. It’s typically a 30 minute, very in depth discovery call with every one of our clients.”
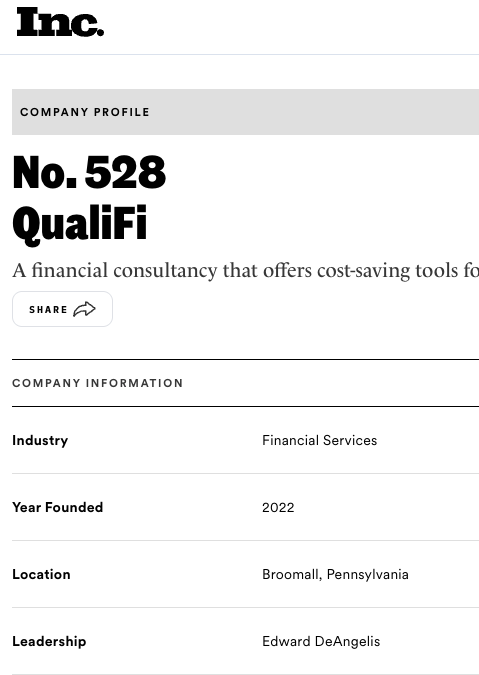
In an era when hyper-growth has become increasingly dependent on automation and AI, QualiFi is finding opportunity by honing in on the human experience. That approach has helped the company generate 658% growth over the past three years and become the ninth-fastest-growing company in Pennsylvania. The Inc. 5000 also ranked QualiFi as the 528th fastest-growing company nationally and second overall among companies that would describe themselves as small business finance brokerages.
QualiFi invests heavily in technology as well, but uses it to make its processes better and more efficient rather than replace crucial elements such as customer service.
“Sometimes if you’re just on a phone call and the business owner’s busy, they got you in one ear and three employees in the other ear, and they might not be paying attention on some of our discovery calls,” DeAngelis said. “We have the CEO on the [Zoom] call. We have their CFO. They might have one of their operations managers. Sometimes we have Zoom calls with three or four members from the business owner’s company. So we feel like it’s much more personable.”
DeAngelis said the objective of the call is to understand clients’ needs and then set a path to meet them, whether immediately or further down the line. From there, the company uses whatever method of communication gets the job done.
 “We use all forms of communication after we have a relationship built, it could be a quick text if we just need something, an email, a phone call, there’s definitely several phone calls that happen throughout,” DeAngelis said.
Suffice it to say, Zoom alone has not led to QualiFi’s success. This past June, DeAngelis was on the big stage at Broker Fair, where he presented to hundreds of brokers in New York City about his company’s history and its journey toward 10xing a broker shop. There, he attributed the company’s success to ingredients including company culture, the client experience, proper hiring, onboarding, and training, among other things.
In a clip that circulated across social media from his presentation, DeAngelis said of culture, “It’s not about posters and ping pong tables.”
“Your team’s on the front lines. And if you really take care of your team, your team’s taking care of your clients, and it kind of snowballs if they feel good about their company, they feel good about their leaders, they’re going to feel good about their products and their services that they’re offering,” he told deBanked. “It just trickles down.”
DeAngelis largely credited his team for QualiFi’s Inc. 5000 placement as well. “I have to pass all the credit back to our team that’s in the trenches every day, our management team, our sales reps, our processing team,” he said.
About 60-65% of QualiFi clients’ first transactions are lines of credit. The company offers unsecured and secured financing, term loans, SBA loans, MCAs, and more.
DeAngelis and his business partner, Jason Maury, set out from the beginning to build a $100 million company. While they have not reached that milestone yet, QualiFi has already experienced tremendous growth.
“We’re going to continue every day, ‘1% better every day,’ that’s our motto,” DeAngelis said, “and we’re just going to try to do good in the world and continue to make everything a better place at QualiFi.”
Figure: Business Loan Brokers Increasingly Arranging Deals Using Home Equity
August 14, 2026“What’s happening is people who have that home equity are using that to fund small business financing,” said Figure CEO Michael Tannenbaum on the company’s Q2 earnings call. “That’s a new avenue for us. We’re lapping about a year of us launching that, and it’s already grown to a meaningfully significant portion of our volume…we’re now signing up people that would historically not have been in the mortgage business whatsoever. They’re business loan originators, brokers, Fintech SMBs, but they’re able to use Figure because we make it so simple and easy and inexpensive.”
Figure has also made waves in the SMB market recently with the addition of an SMB loan pool to its Democratized Prime platform. The pool initially consisted primarily of loans originated by Credibly.
“The partners originating home equity loans for business purpose are also generating opportunities for Democratized Prime, as the SMB market has very little capital market standardization, and we therefore launched our SMB pool officially in July,” Tannenbaum said during the Q2 call.
Figure ultimately wants lenders to be able to access warehouse financing through Democratized Prime and then sell the loans they originate to investors through Figure Connect.
Small Business Funders That Made the 2026 Inc 5000 List
August 11, 2026The 2026 Inc 5000 list is out. Below are some of the familiar names that appeared from the financial services category:
(did we miss you? email us at info@debanked.com to be added!)
Shopify: “Capital was a larger driver this quarter”
August 6, 2026Shopify Capital originated $1.4B in small business loans and merchant cash advances in Q2.
“Capital was a larger driver this quarter, while loss rates in payments and credit are both at normalized levels,” said Shopify CFO Jeff Hoffmeister during the Q2 earnings call.
Beginning in April of this year, Shopify replaced its MCA product in Canada with a loan product in response to new regulations from 2025. It did not elaborate in the Q2 earnings on what specific regulations those were but it is possible they are referring to the amended national interest rate caps that went into effect on January 1, 2025. In a loan, an annualized percentage cost is determinable and controllable from the time the contract is made, whereas there is no predetermined controllable annualized rate on an MCA. Shopify disclosed that the main impact from switching from MCAs to loans in Canada was how it booked them in their financial statements.