Merchant Cash Advance Accounting Pitfalls
January 13, 2015This is question #5 in an interview between deBanked’s Sean Murray and accountants Yoel Wagschal, CPA and Christina Joy Tharp.
- 1. Merchant Cash Advance How to Guide Intro
- 2. Do I Need a Special MCA Accountant?
- 3. and 4. Recording Merchant Cash Advance Transactions on the Books
- 6. Revenue recognition for Merchant Cash Advance
- 7. Q&A – Real questions that MCA companies or syndicators have
Q: Are there any pitfalls for ISOs or funders in the industry with how they run their books? Big no-nos, etc?
A: Here are some of the most common pitfalls we have seen:
- Don’t think of this as a loan – that’s a huge pitfall that we have experienced firsthand (get rid of that word!)
- Don’t have your CFO be one of your syndicators. This inevitably creates multiple conflict of interest issues.
- The biggest no-no – don’t rely solely on spreadsheets! You need a good accounting system that will cross reference and reconcile your accounts. It needs to track and present your cash activity and it should ultimately provide you with your crucial reports. Basically, it needs to accomplish all of the trifecta in question #1.
Phone (845) 875-6030
Fax (845) 678-3574
Email: cjt@ywcpa.com
http://ywcpa.com
Please consult with an accountant to assess your particular situation and needs.
Recording Merchant Cash Advance Transactions
January 13, 2015This is question #3 and #4 in an interview between deBanked’s Sean Murray and accountants Yoel Wagschal, CPA and Christina Joy Tharp.
- 1. Merchant Cash Advance How to Guide Intro
- 2. Do I Need a Special MCA Accountant?
- 5. Merchant Cash Advance Accounting Pitfalls
- 6. Revenue recognition for Merchant Cash Advance
- 7. Q&A – Real questions that MCA companies or syndicators have
Q: ISOs and funders are often asked by their clients or their accountants how to record selling their future sales on their taxes. Should merchants just record it as a loan?
A: No, No, No, and absolutely NO. “Loan” is a dangerous word. MCA’s do not handle loans because if these cash advances were loans then you could not charge such a high percentages. These percentages on “loans” would be against usury laws. Never, ever, use the word “loan”. Take it off of your websites. Take it off your business letters. Remove “loan” from your vocabulary entirely. The funder is buying and the merchant is selling “future sales”.
Q: How should a funder record buying future sales from a GAAP perspective? From an IRS tax perspective?
A:The IRS does not have any special provisions for the MCA industry so follow GAAP. If you have a departure from GAAP for tax purposes, it is the same as in any other industry.
Here is the typical debit and credit entry for most every normal sale:
The company pays for product XYZ with 1,000 USD:
| Account | Debit | Credit |
| Inventory/Purchases | 1,000 | |
| Cash | 1,000 |
The company sells product XYZ and collects 1,500 USD:
| Account | Debit | Credit |
| Cash | 1,500 | |
| Sales | 1,500 |
Very simple. Here you have a profit of 500 USD and this is what you see in your bank account. If the 500 USD is not in the bank it could be for various reasons which is why you need to reconcile.
Of course, there is much more to the merchant cash advance business than these simple transactions but we want to stay focused on this for a little while.
Now remember the business model of the supermarket? Every day the supermarket does thousands of orders and each order has dozens of items. We have to do the accounting for all of those transactions in order to reconcile the proper balances with the inventory. If done manually, we would need an entire staff of accounting clerks just to do those transaction entries.
That’s why everyone in the retail industry understands that they need a good point of sale (POS) system in order to record the information. What do you think the accountant does? The accountant prints out a report at the end of the day/week/month and from that report the accountant creates one entry in the general ledger showing the summary of the day.
I.E.: The summary tells the accountant that registers have rung up the total of 300,000 USD in sales of which 280,000 USD was paid in cash and 20,000 USD was paid on credit.
| Account | Debit | Credit |
| Cash | 280,000 | |
| A/R | 20,000 | |
| Sales | 300,000 |
The idea is that you can sell as many items as you want in a single period but that your accountant should not have more than one transaction to post to the general ledger.
When you want to micro manage you look at the point of sale system. How do you know that the POS system is correct? What is the end goal? Where does the buck stop? Yes, the buck stops in your bank!
If the POS summary is being put in the general ledger, and the general ledger is matching up with the money in your bank – BINGO! If it doesn’t match – TROUBLE!
With this simple transaction in mind we see that the MCA industry has two big challenges:
1) Finding the right management software
2) Finding an accountant who really understands how to reflect these numbers in the general ledger
Unlike in a regular retail business (where you sell a product for money) the product that you are selling here actually is underlying money. It is not a loan, but a purchase of future sales. As this is the case, your bank account becomes the point of sale system. However, a bank typically doesn’t have point of sale capabilities when it comes to reporting and accounting.
To successfully track every cent of your transactions a good cash advance company must have excellent management software. The software must provide a mirror image of the transactions in your bank accounts.
The only way you can do that is if you have one bank account designated to handle only transactions that are reflected in the management software. If you decide to pay a phone bill from this “software transaction only” account, it will be just like a supermarket owner that takes a 100 bill from a cash register in order to pay the store’s phone bill.
Once you establish the “software transactions only” account, (and you have an accountant who can record the summaries into the general ledger while understanding how the general ledger ties into the bank account) then and only then will you be in good shape.
The understanding of the cash advance accounting journal entries can be very confusing if you don’t understand the small steps that make up the big picture. Research reveals sparse results. As that is the case, I will only illustrate a basic example (with no fees).
Please keep in mind that each MCA has different ways of doing some things. This example will cover the basic standards but for modifications and special needs, you will need to find an accountant that understands the eccentricities of your own company’s business model.
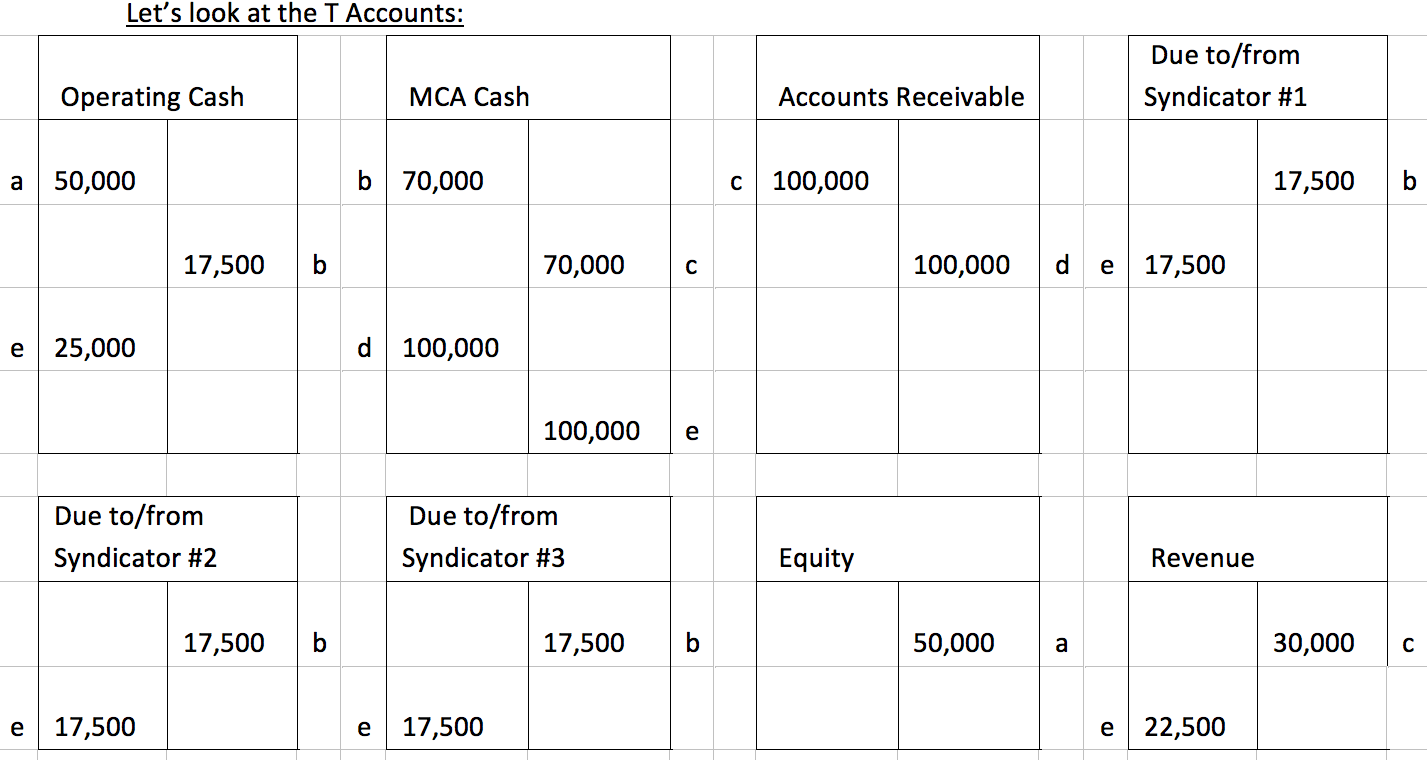
Our MCA model starts with the formation of a small fictional cash advance business. We will start this MCA business with 50,000 USD seed money and we make contact with three investors who we will refer to as syndicators. Yes, I know that some of you reading this call these investors or syndicators by different names, which is part of the confusion out there. To avoid further expatiation, we will use only the term “syndicator” in this article.
On day one “ABC merchant” wants to sell 100,000 USD of their future sales to our MCA business for the discounted rate of 70,000 USD. We reach out to the aforementioned syndicators. They agree to contribute 25% each.
Future sales will be scheduled in terms of 1,000 USD per day for the next 100 days
We are going to have 30,000 USD in profit and it is going to be split among 4 people, each receiving 7,500 USD.
Now we will give it some familiar terms:
Funding amount = 70,000
Payback amount = 100,000
Daily ACH = 1,000
| Account | Debit | Credit |
| Operating Cash | 50,000 | |
| Equity | 50,000 |
| Account | Debit | Credit |
| MCA Cash | 70,000 | |
| Due to/from Syndicator #1 | 17,500 | |
| Due to/from Syndicator #2 | 17,500 | |
| Due to/from Syndicator #3 | 17,500 | |
| Operating Cash | 17,500 |
| Account | Debit | Credit |
| Accounts receivable | 100,000 | |
| MCA Cash | 70,000 | |
| Revenue | 30,000 |
| Account | Debit | Credit |
| MCA Cash | 1,000 | |
| Accounts Receivable | 1,000 |
Although the next step depends on when a MCA company repays its syndicator investments, we will assume the syndicators are all paid at once to allow for a simple transaction example. There is a credit to cash and debits to the syndicator accounts for the principal and the revenue account or an offset account for their share of the profit. The share that I have to split with syndicators wasn’t really my own revenue in the first place.
Multiply this transaction for the number of days (in our example, 100 days). The net effect on this particular transaction will look similar to this:
| Account | Debit | Credit |
| Due to/from Syndicator 1 | 17,500 | |
| Due to/from Syndicator 2 | 17,500 | |
| Due to/from Syndicator 3 | 17,500 | |
| Revenue | 22,500 | |
| Operating Cash | 25,000 | |
| MCA Cash | 100,000 |
| Cash | 57,500 |
| Total Assets | 57,500 |
| Equity | 57,500 |
| Revenue | 7,500 |
After you examine all of the transactions, you’ll see that the chips fall in the right places. We started out with 50,000 USD and received profit from our 25% participated in a merchant funding deal. That deal ended with total revenue of 7,500 USD. It’s all there!
If you truly understand these transactions and you have the proper system in place, then this process should be very easy to follow (even if each of these transactions happens a million times a day).
However, if you don’t understand then you should be very careful because only proper accounting measures can save you from losing tens of thousands or even hundreds of thousands of dollars without ever knowing it. Unfortunately, I have seen it happen with my own eyes. Just like the grocery store example above, the sale of money to MCAs is just like the sale of tomatoes is to grocery stores. If left unaccounted for, those tomatoes could go missing without the store owner even noticing. Don’t let that be you with your money!
Phone (845) 875-6030
Fax (845) 678-3574
Email: cjt@ywcpa.com
http://ywcpa.com
Please consult with an accountant to assess your particular situation and needs.
Merchant Cash Advance Accounting – A How To Guide
January 13, 2015This is the introduction and first question in an interview between deBanked’s Sean Murray and accountants Yoel Wagschal, CPA and Christina Joy Tharp.
- 2. Do I Need a Special MCA Accountant?
- 3. and 4. Recording Merchant Cash Advance Transactions on the Books
- 5. Merchant Cash Advance Accounting Pitfalls
- 6. Revenue recognition for Merchant Cash Advance
- 7. Q&A – Real questions that MCA companies or syndicators have
Funding small businesses is the easy part of merchant cash advance. Anyone can fund. It’s what comes after that’s tricky and I don’t just mean capturing those receivables you’ve purchased, but also recording everything in such a way that you’re not scrambling around tax time.
I have a B.S. in Accounting but I asked the experts Yoel Wagschal, CPA and Christina Tharp his staff accountant for their insight on managing the books for a merchant cash advance company. We’re still a ways off from April 15th so now is your opportunity to fix whatever you might not have done in 2014 and start off on the right foot for this year. Thanks again to Yoel and Christina for answering these questions.
Q: As a funder, what systems should I have in place to make sure I can:
a. Prepare business tax filing
b. Be ready for an audit to raise capital
c. Know whether or not I am making money
A: First of all you have to understand that every type of business has this exact same question. The answer is that you need to have proper accounting entries and records which will then aid you in creating the financial statements (ie: balance sheet, income statement, statement of retained earnings, and statement of cash flows).
Whether it is a tax filing, a bank audit, or an internal inquiry, the solution is identical because all of those situations require the same financial material in order to answer them. In order to prepare a business tax filing a company must provide its profits and losses. That is the same information provided in an audit to raise capital and it is the same information a business owner needs to see how much money they are making (or losing!).
The exact system is obviously custom fit to your individual business model but it should follow these very basic steps:
i) Think the entire process through from cradle to grave
ii) Be sure to codify where funds are coming in from:
a. Investments from syndicators
b. Payments from merchants
c. Commissions
iii) Be sure to codify where funds are being sent to:
a. Funds to merchants
b. Funds to syndicators
c. Commissions
iv) Be sure there is a system of checks and balances which will alert you to the following common errors:
a. Funds not received from/sent to syndicator
b. Funds not received from/sent to merchant
c. Commissions not received
v) The bank account is the authority while the system is only a representation:
a. Your system balance should reconcile with your bank account
b. It is advisable to have a separate bank account for funding transactions
You will also want to pull up trial balances and earnings reports, which must be input correctly from the very beginning in order for these reports to be accurate and effectual.
What makes this industry different is that an accounting system can make or break an MCA company. For example, a supermarket usually has good POS software for inventory control. If an employee drops a “box of tomatoes” it’s not the end of the world. The loss is either immaterial or if it is material the accounting system will pick up the big monetary discrepancy.
In the MCA industry a “box of tomatoes” could be anything from a $0.05 loss to a $500,000 loss. Because the MCA industry deals with money as its product and is often processing transactions at breakneck speed, there needs to be safeguards in the system to catch any and all mistakes in real time.
Our accounting firm has seen where people built attractive systems which seemed good to the funder. However, if the funder lacks accounting knowledge when this “box of tomatoes” falls out they may not be able to place exactly where the loss occurred. Or even worse, they may not realize a loss has taken place until it is too late. For example, if you wait until the end of the tax year and then discover that merchant payments have been missed how do you recoup those funds? It’s the same situation if incorrect amounts are funded to merchants, if incorrect commissions are paid out, or if syndicators have not invested the funds they were expected to.
Phone (845) 875-6030
Fax (845) 678-3574
Email: cjt@ywcpa.com
http://ywcpa.com
Please consult with an accountant to assess your particular situation and needs.
Should I Start an ISO With Only $2,000?
January 12, 2015A long time ago in a galaxy far, far away…
It is a period of civil war. Rebel sales reps, striking from a hidden ISO, have won their first victory against the evil Galactic Funder.
During the battle, Rebel spies managed to steal secret formulas to the Funder’s ultimate weapon, the UNDERWRITING ALGORITHM, an advanced code with enough power to destroy an entire industry.
Pursued by the Funder’s sinister sales agents, our hero races home with her flash drive, custodian of the stolen formulas that can save her merchants and restore freedom to the industry…
Breaking away to start your own ISO or brokerage in this industry used to be a rite of passage. You started somewhere, learned the ropes, then went off on your own like a Jedi Master.
The stories of reps and underwriters of years past who left their jobs to start their own ISOs are a bit nostalgic. Young twenty-somethings defying authority to plant their own flags in an industry they felt offered unlimited potential. For some, going solo was a rude awakening, a healthy taste of the real world, where you needed to be able to do more than just close the leads you’re given. But for others? Well, today they are the owners or managers of companies worth millions, tens of millions, or hundreds of millions of dollars.
Empires were built not that long ago and they certainly were not in a galaxy far, far away. But today the prospects are much bleaker. The industry has matured and certain channels are saturated. Merchant cash advance and non-bank business lending are no longer part of a young unexplored universe.
So to those that have asked me whether or not it makes sense to start an ISO in 2015, I’d have to say in many cases it does not. It’s a little late in the game. Below is one of the most popular questions posed to me over the last six months:
 Q: I’m thinking about starting my own ISO. I have about $2,000 to $5,000 to spend on leads. Do you think I can do it and where should I buy the best leads from?
A: There’s a few things to address here. If you are working out of your house and your rent/mortgage is already taken care of without you having to pay yourself from your new ISO, you may be able to turn a profit starting with something this small. The first problem though is that if you’re not absolutely positive where to get excellent leads, you’re going to spend a lot of money on experimenting with multiple sources. $2,000 might be the cost of an experiment with one lead provider. In other cases, it might be $5,000. Your entire budget could get wiped out in an experiment with just one source.
There may be no barriers to entry in this business, but $2,000 to $5,000 is entirely too little to give yourself a real chance to get off the ground. Direct mail takes a lot of trial and error and thousands of dollars. Google/Bing advertising takes even more trial and error and tens of thousands of dollars before you can get really meaningful results.
And if you’re going to put all your eggs in the UCC marketing basket because of budget, it’s going to be a tough climb uphill.
The companies that do actually have the best leads don’t need a $2,000 startup ISO to sell them to. A big ISO or funder is probably already paying double the price they’re worth.
So how do you stand a chance? You should realize that the odds are you won’t.
And if you need to allocate part of that 2-5k to pay for an office and get set up like a business, you might not have anything left for marketing at all. That’s a horrible place to be!
Lastly, I have seen many ISOs try to become a broker’s broker in order to acquire deals. That means trying to close ISOs to send you deals for you to forward on to a funder as a middleman where you will get a cut if the deal closes. It’s a hustle, and if you can swing this, great, but it’s not exactly a sustainable model especially if the ISO realizes they can go direct to the funder themselves. If you can’t acquire merchants on your own (and deals you stole from the last place you worked at don’t count as acquiring on your own), then you probably shouldn’t be in the ISO business at all.
If you’re going to start an ISO in 2015, I suggest having a minimum $25,000 (50k to be safe) in marketing to start off. And if you don’t know what you’re doing, well then may the force be with you.
Heather Francis Launching New Funding Company
January 5, 2015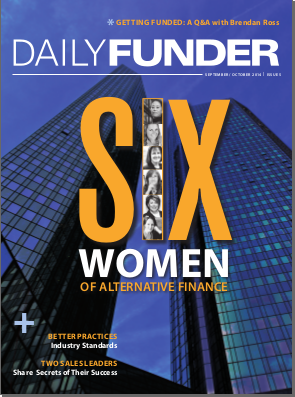 One of the Six Women of Alternative Finance is leaving their current position to launch their own funding company. Heather Francis, EVP of Merchant Cash Group appeared in the September/October issue of DailyFunder. A regular at the industry’s conferences and who was in many ways the face of Merchant Cash Group, Francis is moving on to start Elevate Funding.
When the news broke, deBanked asked Francis about the change. This was her response:
“So the start of the new year begins with something exciting for me as I will be leaving Merchant Cash Group to pursue heading up my own funding company. Elevate funding is still in the set up stages and will not be operational and funding until Mid February but I can assure you that with each unveiling of what we will be funding and what we will offer to the Alternative Industry as well as the business owners will help shape a new future. I enjoyed my time at Merchant Cash Group and I wish them all the best but I am excited for this new adventure and to take a lot of the ideas that have been kicking in my head for a while and see them come to fruition. I know it will be difficult and I am greatly looking forward to the challenge. In the words of a Fort Minor song : This is 10% luck, 20% skill, 15% concentrated power of will, 5% pleasure , 50% pain, and a 100% reason to remember the name… Best of luck to all in 2015!”
Elevate will be based in Gainesville, FL.
Despite FinTech Disruptions, Many Thing Stay The Same
January 5, 2015 2014 was an unbelievable year!
I kicked off last year by opening an account with Lending Club so that I could understand their product. Today I have tens of thousands of dollars invested on their platform and picking up new loans has become part of my daily routine. You could say I’m not surprised they went public a few weeks ago.
I also launched the industry’s first trade publication and ran it as both publisher and chief editor. We produced 6 issues and distributed more than 20,000 print copies combined. Unfortunately the publication will not be continuing further. It is wild to think that it both started and concluded in 2014 as the magazine had a cult-like following.
7 conferences in 4 cities. Las Vegas (twice), San Francisco, New Orleans, and here in New York. I spoke at two of them. Hoping for at least 1 Miami conference this year. Please??? It’s so cold here right now.
OnDeck Capital took a lot of flak in 2014 from both industry insiders and the media. They shrugged it all off and went public on December 17th. Considering they’ve operated on the fringe of the merchant cash advance industry for so long, it was one of those things you had to see to believe. I didn’t get inside the building but I saw the IPO was real from the outside.
I started off 2014 not knowing what a Bitcoin was. Now I have a copy of the entire blockchain, operate a full node (don’t worry I have port 8333 open), have 10 dedicated mining devices running 24/7, have made purchases with bitcoin, conducted countless transfers, and just finished coding a working prototype application using Coinbase’s API. And when I realized that bitcointalk.org and my cryptography books weren’t enough to satisfy my appetite, I found myself talking about bitcoin on IRC; #bitcoin and #bitcoin-pricetalk on irc.freenode.net. I also know who Satoshi Nakamoto really is now too but he made me promise not to tell anyone.
I rebranded Merchant Processing Resource to deBanked, retiring a name I’ve used for 4 years.
I interviewed former Congressman Barney Frank, one of the two architects of the Dodd-Frank Wall Street Reform and Consumer Protection Act (it was only a few questions).
I got asked by a credible movie producer if I would help him on a storyline for a script about Wall Street and the alternative business lending industry. Don’t worry I turned it down!
I jumped on the payment disruption bandwagon and used Square to process credit card transactions all year. You should know that I previously did merchant account sales. I could’ve boarded my own account and set my own fees but I went with Square anyway.
I finally got set up to syndicate on merchant cash advances.
I ran my first 5k in Central Park.
I moved to a different part of Manhattan.
Of course a whole lot more happened. It was a roller coaster year which leads me to believe that 2015 will be impossible to predict. There’s a lot more room to grow in FinTech but it might be time for fresh ideas. Everyone and their mom built an online lending marketplace platform in 2014.
Similarly, it’s also a tough time to become a loan broker or MCA ISO especially if you’re undercapitalized. The easy profit ship has sailed. Press 1s and UCCs aren’t winning business models, at least not ones that will invite outside capital or ensure survival long term.
2014 changed finance but in many ways it stayed the same.
It still takes 2-4 days to confirm an ACH didn’t reject! This is annoying all around. If I add funds to Lending Club on a Monday, it’s not accessible until Friday evening. If you debit a merchant on Monday, you won’t really know if you have it until a few days later. Believe it or not I actually mailed out more checks in 2014 than in any other year of my life. The ACH system appears to be fine until you use something that is far more advanced, something I will probably write about over the next month. Instantaneous payments, low transaction fees, no bank involvement. Yeah, it’s time for ACH to go away…
And with banks, well… I have opened business bank accounts over the last few years with 3 different banks. The one I opened in 2014 required a two hour in-person interview, a process that involved filling out forms by hand and being threatened that the government would shut everything down in a heartbeat if they found out that I so much as breathed wrong on an ATM. It was a repeat of prior account opening experiences. Although I’ve never had an account closed for doing anything wrong (because I’m not actually doing anything wrong), it is easy to see how much regulatory pressure banks are under. Swiping your debit card upside down could cause the entire bank to get an Operation Choke Point subpoena. They want your business but they’re scared to death of anything you might do with a bank account.
All the major peer-to-peer platforms of 2014 became centralized. Lending Club and Prosper don’t even fall in the p2p category anymore. The market trend has been to create a platform designed for the little guys and then hand it over to a bank or institutional money to do all the funding. In some ways it’s easier to deal with a handful of big players instead of thousands or millions of retail investors. But with the regulatory environment uncertain on so many new investment products, it’s probably also safer to deal with institutional investors, lest the regulators claim they violated a consumer protection law they thought up this morning.
Banks continue to be the biggest obstacle to innovation because at the end of the day, all payments flow through them. How can one deBank and truly disrupt?
Hopefully we’ll find out in 2015. Happy belated New Year.
Through OnDeck Capital, An Industry Wins
December 16, 2014 Call it merchant cash advance, non-bank business lending, or financial disintermediation. Whatever floats your boat. On December 17th an entire financial methodology will be validated, the daily repayment method. Daily payments don’t exist anywhere else in lending but ’round these parts it’s the standard. It’s what makes unbankable businesses bankable.
OnDeck is a lender. They target small businesses. The costs are high. Anyone could feasibly do those things and plenty are doing them, but only a certain segment of fintech companies utilize daily payments and most of those are merchant cash advance companies. OnDeck is a lender but like it or not their core repayment mechanism overlaps with an industry well known for being even more expensive.
Daily payments are so unique and so revolutionary that it hasn’t sunk in to the masses yet. Even the press glosses over this fine detail to instead dwell on things like APRs and social media’s role in approvals. Daily payment and daily repayment look like tech jargon, some kind of code for a backend computer process to hotwire an anomalous rate algorithm.
Daily payments mean borrowers have to make payments every single business day. It’s daily, get it? If the sun rises and it’s not Saturday or Sunday, it’s time to make a payment. I’m not saying there’s something wrong with this. I’m a proponent of this mechanism. It works for business owners that struggle to make a single lump sum payment each month and it works for lenders who need to mitigate and monitor their risk as much as possible.
 I feel it’s better to know there was a problem that started yesterday than to learn there was a problem that started 29 days ago. That’s how OnDeck thinks too. And business owners can incorporate the daily deduction into their normal business operations instead of fretting to cover the balance for a big debit the day before a monthly payment is due.
This isn’t just a theoretical design that can’t function in practice. It’s been working for lenders and factors since AdvanceMe (Now CAN Capital) started doing it in 1998. The daily payment methodology has survived the Dot Com Bust and the Great Recession. It’s grown to a $3 – $5 billion a year industry. By some measures, it’s taken a hell of a long time to go this mainstream.
But it’s here. The press will call OnDeck a lender, a tech company, or a combination of both. They’re a sign of the times but they are unique in that they will show the world that daily payments have a place in the modern economy. With OnDeck leading the way, traditional lenders may consider leveraging their methodology to serve categories of risk they usually shy away from.
I’ve never heard of a business credit card that required payments to be made every day. Some might think that defeats the purpose of credit. OnDeck proves it doesn’t. And 100+ merchant cash advance companies serve as a secondary validation. Perhaps there are lenders that have considered a daily payment system previously and feared the political or legal environment was too risky. But OnDeck is making no apology about what they’re doing or how they’re doing it. They’re putting themselves on the open market, surrendering themselves to total scrutiny.
 CAN Capital is gearing up to follow them, the pioneers who first experimented with daily payments 16 years ago. And while OnDeck bemoans their loan program being compared to merchant cash advance, CAN is made up of two departments, one of which is undoubtedly a merchant cash advance service provider.
And there you have it. It’s not all about algorithms or tech or using facebook activity to judge a borrower. Those are old ideas now. OnDeck smashes down the door with something completely different, something that nobody is even talking about, daily payments.
December 17th is Wednesday and just about all of OnDeck’s borrowers will be making a payment. A good many of them won’t even notice. That’s the great part about layering it in as a daily cash flow expense. There’s no worrying about it at the end of the month. If they underwrite the borrower financials well enough, it should be completely painless. That’s not always the case, but it’s the goal.
You can’t possibly understand OnDeck until you understand daily payments. With this IPO, an entire industry wins.