
CFPB Reaffirms Excluding Merchant Cash Advances From Section 1071
October 13, 2026The CFPB recently published its annual Fair Lending Report. Under the section about small businesses, it reaffirmed its decision to exclude MCAs from the Section 1071 rule.
On May 1, 2026, the CFPB issued the final rule. The rule reduces the scope of “covered credit transactions” by limiting the types of transactions subject to reporting in order to focus data collection efforts on core lending products—loans, lines of credit, and credit cards—that are most utilized by small businesses. Accordingly, the rule sets forth certain exclusions: merchant cash advances, agricultural lending, and small-dollar business credit.
It further reiterated its decision to make other modifications to Section 1071.
In addition, the rule revises the definition of “small business” by reducing the gross annual revenue threshold from $5 million to $1 million. This will allow the CFPB to focus on collecting data related to micro and small enterprises, which are most relevant to section 1071’s goals. The rule also reduces the number of collected data points, extends and adopts a uniform compliance date of January 1, 2028, and simplifies the time and manner of data collection in order to allowinstitutions flexibility in how they comply with statutory requirements.
The rule updates are necessary to ensure reasonable implementation that does not restrict credit availability for America’s small businesses. The 2023 rule imposed a significant number of requirements that were not needed to advance the purposes of section 1071 of the Dodd-FrankAct. This rule recognizes those concerns and takes a more reflective approach, including just what the statute requires. The updates will result in cost savings for institutions and reduce the burden of data collection without sacrificing data availability.
Wells Fargo-supported Fund Aims to Refinance MCAs
October 8, 2026Sixty-one percent of all deals funded by Founders First Capital Partners went toward refinancing merchant cash advances. That’s intentional, according to the company, which just announced a capital raise of $19 million for one of its small business financing funds. Investors in the fund include Wells Fargo Foundation, Deutsche Bank Americas Foundation, Sunrise Banks, Community Reinvestment Fund USA, and others.
Founders First offers revenue-based financing, term loans, and hybrid loans that combine both. The company says borrowers that refinance their MCAs with Founders First experience an average effective APR decrease of 15 percentage points.
“To help meet that demand [of refinancing MCAs], Wells Fargo contributed $500,000 to Founders First, fiscally sponsored by Realize Impact,” a press release said.
Founders First does not advertise its own APRs, but according to a hybrid loan contract it originated in 2023 that deBanked obtained, it said that amounts collected from the revenue-based financing component of the loan should be excluded from interest and interest rate calculations and should not be considered when determining whether the loan exceeds a state’s maximum allowable interest rate.
Many of the company’s case studies tout the benefits of revenue-based financing. In one case, a borrower received $500,000 and grew revenue by 90% over 12 months. Founders First said that “revenue-based financing was ideal as the payments were increased during stronger revenue months.”
The company has deployed more than $20 million in capital, and 70% of its customers have increased their revenue. Its financing has also contributed to the hiring of more than 2,700 new full-time employees. Businesses can obtain funding of up to $2 million. In Founders First’s 2025 Impact Report, the company says its financing is better than SBA loans because borrowers do not need strong credit or assets. It also touts how more than half of its portfolio consists of refinanced MCAs.
True Food Kitchen Had $2.2M MCA Balance With Parafin Before Bankruptcy
October 7, 2026FRC Balance, LLC, which owns the True Food Kitchen restaurant chain, filed for bankruptcy this week. According to the company, True Food Kitchen has closed 12 restaurants, whose final day of service was Sunday, October 4. The company’s remaining 34 restaurants across 14 states are open and serving guests as usual.
Among the company’s listed creditors is Parafin, with an outstanding merchant cash advance balance of $2,206,502 reported in one of the bankruptcy filings. There is no indication that the MCA added to the company’s financial pressure (True Food Kitchen owes millions just to its food vendors alone, for example, and they cited organizational issues as the root cause). The balance is notable, however, for its size and for how the arrangement originated: through DoorDash Capital. deBanked was one of the first to discover DoorDash’s entry into MCAs in January 2022.
True Food Kitchen has been a poster child for DoorDash Capital since last year. In July 2025, DoorDash published a feature about the restaurant chain’s use of merchant cash advances. Titled How True Food Kitchen Used DoorDash Capital to Fuel Expansion, it opens by saying: “In September 2024, Peter Koumas, True Food Kitchen’s CFO, found DoorDash Capital while exploring the restaurant’s Merchant Portal, right as True Food Kitchen was in the middle of an exciting expansion phase, opening two new locations in Scottsdale, AZ, and Raleigh, NC.”
At the time, 10% of True Food Kitchen’s overall revenue came through DoorDash. The feature also noted that DoorDash Capital MCAs were provided by Parafin. In its bankruptcy filings, True Food Kitchen also listed a $1.8 million “MCA” balance with Rewards Network and a $7.1 million balance with InKind Credit, alongside debts to more traditional creditors.
Just a week ago, Parafin announced that it had been sold to Stripe for an undisclosed amount. It also revealed that it had originated $3 billion in funding since its inception in 2021. Until then, the scale of Parafin’s funding activity had been largely unknown. The True Food Kitchen bankruptcy now offers a glimpse of how large its exposure to a single client could be.
Counsel for the debtors said during a bankruptcy court hearing that they planned to reject Parafin’s contract and the payments towards it. True Food Kitchen blamed a combination of management turnover, changes in expansion strategy, failed investments, and product/branding issues as the reasons for its predicament.
Parafin Funded Over $3 Billion to Merchants in Five Years
October 1, 2026One of the key details revealed in the Stripe acquisition of Parafin is that Parafin originated $3 billion in funding since the company first started originating in 2021. Parafin supplied the financing infrastructure for platforms such as: DoorDash, Amazon, Gusto, SpotOn, Fullsteam, Jobber, and dozens more. Assuming the company experienced a normal growth curve, the company likely exceeded $1 billion in originations over the last 12 months, putting them roughly on pace with what Stripe’s own funding business was producing. deBanked previously estimated that Stripe Capital originated $1 billion in funding in 2025.
When the deal finally closes and Stripe Capital combines with Parafin, the resulting funding entity will rank among the largest online small business lenders in the country. Only Quickbooks Capital, Shopify Capital, OnDeck, and Square Loans will continue to be significantly larger, at least among the companies tracked by deBanked.
How to Pay Off an MCA With an SBA Under The New Rules Effective Oct 1
September 23, 2026The SBA has provided new guidance on its approach toward refinancing merchant cash advances: if you convert one to a term loan, you’ll have to wait a very long time to refinance it with an SBA.
According to the most recent Standard Operating Procedures that go into effect on October 1, “Sales-Based Repayment Agreements (e.g.; Merchant Cash Advances) are only eligible for refinancing if the original agreement has been converted to a term loan, has amortized for at least 24 months, and no additional Agreements have been implemented since the conversion of the prior agreement(s).” If there’s any uncertainty as to what that means, they go a step further and say “If the Sales-Based Repayment Agreement is still active, it is not eligible for refinancing.”
This is slightly different from last year’s SOP that said “merchant cash advances and factoring agreements are not eligible for refinancing.”
The new language was perhaps put in place to close a potential loophole where an MCA is converted to a term loan and then immediately refinanced by an SBA.
A Journey Through Collections With Erica Gilerman
September 8, 2026“Within two weeks, I closed my first deal. I just clicked in the industry,” said Erica Gilerman.
Gilerman wasn’t talking about funding a deal. She was talking about collecting on one.
“Closing the deal on our end means that we have a signed, sealed, and delivered stipulation, one that our client is happy with, and one that truly makes sense financially for the merchant as well,” she said.
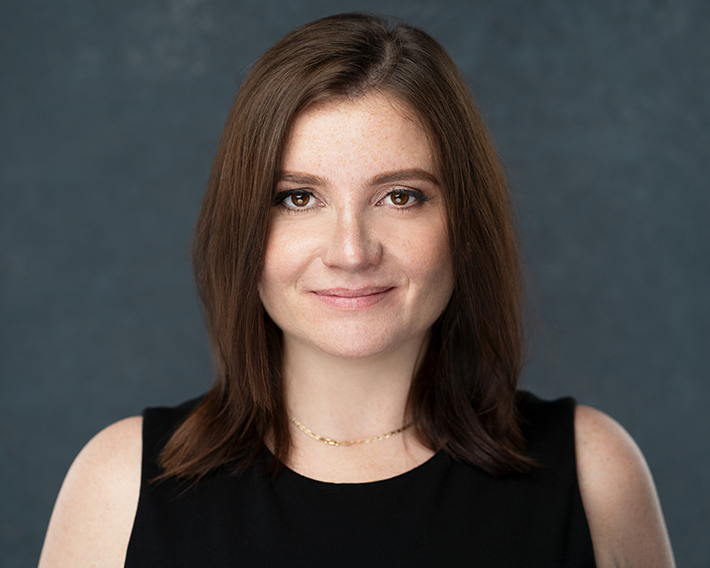
Conventional wisdom in the small business finance industry has long held that anyone can put money out the door; getting it back is the hard part. Gilerman currently serves as Chief Legal Officer of that hard part, working for Triton Recovery Group in South Florida.
Talk to anyone at Triton and they’ll probably tell you that successful collection begins during the underwriting process, before a deal is ever funded in the first place. In a taped interview deBanked conducted with Triton CEO Leo Vargas in 2024, he said, “The underwriting process to me is the most important piece of getting a deal done in the industry.” Vargas offered examples, saying that it’s critical to know from the outset what merchants plan to use the funds for and that the terms of any deal should be set in accordance with a merchant’s anticipated receivables, not deposits.
Today, Triton has 75 employees. But when Gilerman was being recruited to work there in 2021, the company had only six. Vargas was looking to add an attorney to his then-fledgling traditional commercial collections firm, which was focused entirely on the merchant cash advance industry, and he posted an ad in the New York City market.
“I will never forget… it was very interesting to me because it was in all caps and it said ‘COLLECTIONS ATTORNEY, NEW YORK,'” said Gilerman.
She answered the ad, met Vargas in New York, and received an offer. There was just one catch: She had to spend a month training at Triton’s Miami office to learn its particular niche of collections. That required a significant sacrifice, time away from her family, but she decided to take a chance and then determine whether the job was right for her. She started in July 2021 as the firm’s General Counsel.
“Within two weeks, I closed my first deal. I just clicked in the industry,” she said. “Between my accounting background—I understand how the factor rates work, I understand how businesses operate, I take a very unique approach to everything in the sense that I will collect in a way where I put myself in the debtor’s shoes.”
Gilerman, the daughter of immigrants, was born in Brooklyn, New York, and she attended Madison High School in Brooklyn. She was accepted into the school’s law program, which had been created by former Supreme Court Justice Ruth Bader Ginsburg. Ginsburg, herself a Madison graduate, had created the curriculum.
“My love for law really kind of came to play there, and I learned a lot from that program,” Gilerman said, “and that’s why I’m very proud to say I’m a New York City public school graduate, and that’s how I fell into law.”
Gilerman faced a personal family tragedy as she began college at Pace University, around the same time Lehman Brothers collapsed. Pace’s campus in Downtown Manhattan had a front-row seat to the turmoil unfolding across the financial system.
“I will never forget that in that moment I realized I need to find a career that will not keep me into some sort of niche, because 25 years from now I could be one of those people that was carrying boxes,” Gilerman said, “and they had nowhere to go and nothing to do, and it was a very eerie dynamic being on Wall Street at the time.”
Gilerman initially intended to pursue a career in public accounting as a result but ultimately swerved back toward law. After becoming an attorney, she worked in employment litigation before moving on to collecting medical debt for hospitals in New Jersey.
“You have to have a specific type of personality to be in collections, especially as a woman,” she said. “I would candidly say I would never expect myself to be in collections. That was not my goal in law school, but I would not change it for the world now. This is exactly the niche industry I need to be in.”
Part of that certainty came from finding the right person to work with.
“I will say that I learned most of the MCA space, especially on the front end side, from Leo. He taught me the collections mindset for commercial collections, and we just clicked in a way that it was just a great synergy from the beginning.”
Triton was still quite small at the time. When Gilerman visited the company’s original Miami office, they had to set her up in the break room. By the end of 2021, however, the COVID lockdowns were finally beginning to dissipate nationwide, and the company hit the gas pedal by sponsoring a conference that December in New York: Broker Fair.
“We were able to expand and start hiring more after the very first deBanked [conference] that I attended, which was December of 2021,” Gilerman said.
By then, her mind was fully made up. She and her family moved to Miami two weeks after the conference. Five years and nearly 70 additional employees later, spread across two states (Florida and Texas), she has since become the company’s Chief Legal Officer.
In those early days, Gilerman was still trying to wrap her mind around the financial product Triton’s clients worked with. She said she came to really understand “that without the MCA industry, there is no such thing as a mom and pop shop anywhere in this country and it really changed my perspective of what alternative finance as a whole is.”
Triton’s collection practice handles MCA, commercial loans, and equipment financing on a contingency basis. Ask the team a question about underwriting and they’ll readily offer an opinion. They’re only interested in legally enforceable paper.
The latest frontier in collections includes dealing with merchants who have turned to LLMs to fire off letters, emails, and demands, often containing incorrect information or citations to the wrong statutes. It has become commonplace to see merchants effectively act as their own attorneys with the help of AI, or even claim that AI is representing them.
“I see a lot from ChatGPT and Claude there, and the problem is that they continue to just say the same thing over and over,” she said. “You could tell by the tone because no one’s actually telling them to make it sound like themselves.”
Even on phone calls, merchants may attempt to bring AI agents onto the line with them.
On the flip side, collectors can use AI too. In a recent social media post, Triton CEO Leo Vargas said, “The best agencies will use AI to eliminate repetitive tasks, improve compliance, analyze consumer behavior, optimize account placement and provide collectors with better insights before they ever pick up the phone. Collections has always been about people. AI simply gives those people better tools to succeed.”
Vargas also referenced Gilerman in an email to deBanked. “Five years ago, [Gilerman] took a chance on Triton and joined us during an important stage of our growth,” he said. “Since then, she has grown alongside the company and worked her way to becoming our Chief Legal Officer and a key member of our executive leadership team.”
“Collections, especially the MCA space, this is us playing chess,” Gilerman asserted. “And for us, a checkmate is getting that payment through the door, making our client happy, allowing our client to then redeploy those funds.”
Small Business Funders That Made the 2026 Inc 5000 List
August 11, 2026The 2026 Inc 5000 list is out. Below are some of the familiar names that appeared from the financial services category:
(did we miss you? email us at info@debanked.com to be added!)
Shopify: “Capital was a larger driver this quarter”
August 6, 2026Shopify Capital originated $1.4B in small business loans and merchant cash advances in Q2.
“Capital was a larger driver this quarter, while loss rates in payments and credit are both at normalized levels,” said Shopify CFO Jeff Hoffmeister during the Q2 earnings call.
Beginning in April of this year, Shopify replaced its MCA product in Canada with a loan product in response to new regulations from 2025. It did not elaborate in the Q2 earnings on what specific regulations those were but it is possible they are referring to the amended national interest rate caps that went into effect on January 1, 2025. In a loan, an annualized percentage cost is determinable and controllable from the time the contract is made, whereas there is no predetermined controllable annualized rate on an MCA. Shopify disclosed that the main impact from switching from MCAs to loans in Canada was how it booked them in their financial statements.