Need Capital for Your Funding or Lending Company? 3Jane Does it On Blockchain
July 27, 2026“I’m a big believer in agentic capital markets. I think we’re going to see a Cambrian explosion of novel primitives, driven largely by two pieces. Today, it’s just very easy to construct arbitrary financial building blocks using smart contracts,” said Jacob Chudnovsky, Founder of 3Jane, to deBanked.
3Jane provides credit facilities and forward flow arrangements across a range of products, including consumer loans, small business loans, and even merchant cash advances. The company previously provided a $10 million senior warehouse facility to consumer lender LendSwift, for example, and followed that with an inaugural $8.5 million purchase of small business loans from Slope, an embedded credit infrastructure provider that powers business lending programs for major players across the US, including Amazon. According to Chudnovsky, 3Jane would like to do even more deals in the small business lending and MCA space.
But with a twist.
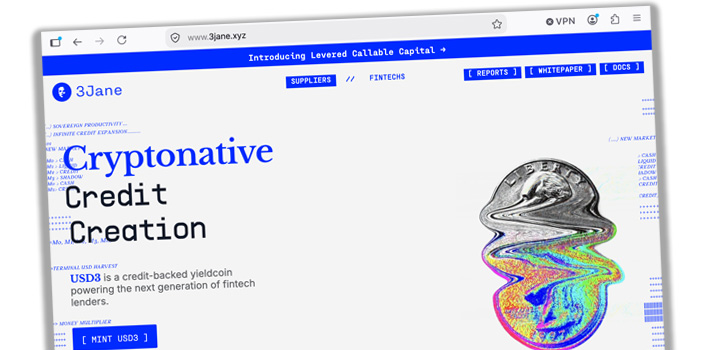 3Jane has built an entire protocol on the blockchain. It offers a credit-backed “yieldcoin” that earns its yield “from warehouse facilities, forward-flow programs, and credit-lines.” Investors can mint the coin on Ethereum, and it earns a yield backed by the performance of 3Jane’s credit assets. Minting is not open to US investors, but the company’s capital markets offerings are focused exclusively on North America. So, if you’re a small business funder seeking a credit facility or forward flow arrangement, 3Jane wants to speak with you.
Chudnovsky is a software engineer by trade and entered the DeFi space in 2020.
“…around 2024, I basically came to the realization that credit is still an extremely underdeveloped vertical in crypto and particularly both the capital aggregation and the capital distribution side of it,” he said. “My initial focus was ‘can we get the best of crypto to distribute capital in a better way?’ and so I founded 3Jane, and we started off by doing unsecured lines of credit for crypto users in the United States who had a bunch of these different assets and could not really borrow against it in a streamlined way.”
 That effort eventually led to 3Jane’s current business model. If the name 3Jane sounds familiar, it’s because Chudnovsky drew it from the 1984 novel Neuromancer, the famous William Gibson book that coined the phrases “cyberspace” and “the matrix.” By pure coincidence, Apple TV is releasing a 10-episode series based on the book in January 2027.
“I just think we’re going to enter this complete renaissance of new different financial primitives and I think it’s going to drive a lot of adoption, new ways of thinking about our financial system and that sort of really resonated with me with the book,” Chudnovsky said.
And that new way of thinking is starting to take root. The capital markets utilizing blockchain to create efficiencies is already cropping up around the industry. Since 3Jane last spoke with deBanked, its purchase of embedded finance products from Slope has increased to a total of $60 million.
3Jane’s customers do not need to be crypto experts. The company handles that side of the transaction while underwriting the risk and executing what is otherwise a conventional capital markets deal, but one in which the infrastructure is robust enough that this can be a lender’s first and last facility. On 3Jane’s part, doing this requires a strong understanding of the various financial products it evaluates, including MCA.
“…there are a number of MCA operators in the United States that are doing things right, they’re growing significantly and they need leverage to scale their business,” Chudnovsky said. “and so warehouse facilities and to a lesser extent forward-flows for MCAs sort of equally make sense for them as long as you are cognizant of the risks.”
Stripe Capital, PayPal Working Capital Could Merge If Acquisition Offer is Accepted
July 19, 2026The old rumor that Stripe was interested in acquiring PayPal was apparently true. Partially anyway. This past April, Stripe, along with Block and Advent (a private equity firm), let PayPal know they were jointly interested in acquiring it. But Block dropped out of the deal and the newest acquisition offer, now public, comes from just Stripe and Advent together. While Stripe and PayPal are obviously known as payment processing companies, the two originate more than $3 billion a year in MCAs and short term business loans a year combined.
PayPal is one of the few online payment platforms to struggle with bad debt in its merchant funding program and the company had never weaponized its lending offerings to grow PayPal’s business. Nevertheless, its origination volume outpaced Stripe’s in 2025. Stripe and Advent offered $53 billion to acquire PayPal. It remains to be seen if a deal will actually happen.
American Brokers Help Fuel Canada’s Small Business Finance Boom
July 10, 2026 Canada’s small business finance industry is growing, and behind the scenes, American brokers are helping fuel that momentum.
“They’re kind of killing it here right now, from what we see from the partners that we work with,” said Vlad Sherbatov, President & Co-founder of Smarter Loans, an online lending marketplace in Canada. “…for the American players that have come in, they’re already really good at the broker channel.”
Some Canadian small business funders, particularly those offering an MCA product, told deBanked that a significant amount of deal volume is coming from south of the border. And with that, the environment and culture of the business itself is beginning to shift. In their view, it is becoming more Americanized.
“…a lot of the Americanization of the industry, if you will, is coming from US brokers and funders,” said Avrohom Bernstein, CEO at 2M7 Financial Solutions.
Part of that shift is a new level of competition among firms as brokers try to maximize the options available to their clients. Bernstein, for example, said it often starts with an American broker inquiring about submitting a few Canadian deals. Lately, however, it’s been escalating into situations where eight different brokers might submit the same clients.
“Every deal now you’ve got to hustle, you’ve got to fight, you have to really work it,” Bernstein said.
That competition once meant fighting to become the one and only exclusive partner for a merchant. Now, it has become more common to find that a submitted applicant already has multiple active advances.
“…that used to be unheard of in Canada, like that used to be excessively unusual to see more than three positions, now ten is not insane anymore,” said Bernstein. “It really escalated in a way that we haven’t seen, and that’s probably over the last 12, maybe 24 months, that it started really picking up,” Bernstein said.
Jodi Levy, Head of Sales and Business Development for BizFund in Canada, said she has made a similar observation. When she first started in the industry there, something like a third position was unheard of. Now, she said, they see it much more often.
“I feel like that’s definitely more an American influence,” Levy said.
BizFund has a large American operation as well, so the company is no stranger to how things work on the other side of the border. But like others, its Canadian funding arm also works with the American broker community.
“…partners are great, American, Canadian, we don’t care where you’re from, as long as you’ve got good business,” Levy said, adding that what matters is whether those partners have a direct relationship with their merchants. She also said that working with the broker community requires operating with a sense of urgency, something she has instilled in her team as a culture of NOW.
The diversity of products brokers can offer may not be as wide as what is available in the US. Sherbatov said that once a business steps outside of traditional banking sources, it is essentially entering MCA territory. As a result, much of the new competition entering the space is focused there.
“Among the new players that have come in, MCA is definitely the product that they’ve been leading with,” Sherbatov said.
“We have like five or six banks, and then like a couple credit unions, and then there’s not really anyone between, and there’s A-paper guys, and then B, C, D type of guys,” said Bernstein of 2M7.
According to Statistics Canada, banks provided 68.5% of all capital to SMEs in 2023, while credit unions and government institutions provided 20.6% and 9.4%, respectively. Only 2.2% was funded by “online alternative lenders.” The total market size at the time was estimated at $94 billion.
“I think the big gap is—there’s tons of businesses that want capital,” said Rafael Rositsan, CEO and co-founder of Smarter Loans. “There are some funders that offer it, but they’re pretty tight, and I feel like if somebody can come in and take on a bit more risk and open up their books a bit, then there’s plenty opportunity to fund a lot of Canadian businesses.”
 As for why there has been such a push from Americans into Canada, no one pointed to a single definitive reason, but the runway for growth in the alternative lending segment, as illustrated by the report, may provide a clue as to the interest. Bernstein of 2M7 said there has long been a pattern of Americans entering and exiting the Canadian market, but he had also long believed that sustained success required boots on the ground. Now, he is reconsidering that view, at least on the broker side, as the current wave of broker entrants appears to be holding more firm. For funders, however, he said it still does not really work as a remote business.
“Every funder that’s actually doing decent volume is here, except for one,” Bernstein said.
In 2019, deBanked held a conference in Toronto for what was then a burgeoning small business finance industry, but held off on further events there after Covid disrupted plans for 2020 and 2021. It did not go unnoticed, however, that deBanked’s more recent American-based events have had more email addresses ending in .ca on the attendee lists. At the most recent Broker Fair conference in New York City, for example, some firms were exclusively advertising Canadian funding products to American brokers.
Canada’s population is relatively small, at roughly 41 million residents. That is about the size of California and only 25% larger than Texas. Homegrown Canadian brokerages do exist, of course, and a lot of business in Canada stays within Canada. Not all of the deals are originating through brokers either. Some merchants prefer to work directly with a funding source, while others prefer the comfort of applying through a Canadian lending marketplace like Smarter Loans, for example. If a merchant is ultimately eligible for some kind of funding, Sherbatov said, they are going to know it through their platform.
“We love the fact that we can help the small business economy thrive in the country, it’s responsible for a lot of positive things,” Sherbatov said. And whether the funding sources originate from Canada or the US, he said those companies ultimately find their way to them.
“We’re just becoming a more critical part of that journey for the merchant, and I think that explains why a lot of the new companies, when they come in, they gravitate toward us,” said Sherbatov. “…because in the business financing space we’ve carved out a nice niche for ourselves after Covid, and usually the new players gravitate to us because they know that merchants come to us as well.”
Levy of BizFund said part of the Canadian business experience is kindness. “That stuff goes far, we love that stuff up here in Canada,” she said. On the company website, photos of the company’s team, including Levy, show them smiling and ready to fund businesses.
For stalwarts like 2M7, which launched in Canada in 2008, the market’s evolution has been dramatic. Bernstein said the industry has gone from being a bit quiet and under the radar to seeing a lot of energy recently, whether from American brokers or from Canadian brokers that have decided this is the niche they are going to focus on entirely.
“In the US, I know a lot of brokers who also do equipment and also term loans and also SBA and also all this other type of stuff, it doesn’t exist so much in Canada,” Bernstein said. “It’s like if you’re selling to small businesses and you’re offering them financing, there’s not that many products you could line up, so it’s like if you’re doing brokerage, you got to be all in, like if you’re doing MCA, you got to do MCA.”
“I think that it was evident to a lot of players outside of the market that there is a big market opportunity that’s untapped,” Sherbatov said, “just because so little financing is being released by alternative lenders, that they started to come into the space, and we’ve seen, I mean, not even for the past two years, but I’d say in the past 18 months, our own roster of business lenders on Smarter Loans has doubled, like we went from 10 to where now we have 20, and the majority of that expansion actually happened from US players coming into the country.”
And the growth is just getting started.
“There’s a lot more room for it,” said Rositsan of Smarter Loans.
Factoring to Take MCA Fight to Federal Level
July 2, 2026In the wake of new merchant cash advance laws passed in Texas and Vermont, American Factoring Association President Cole Harmonson posted the next step is to take the fight against MCAs to the federal level.
Post below:
Oregon Offers Revenue-Based Financing With 2.0 Factor Rates
June 29, 2026 The State of Oregon is in the revenue-based financing business, offering small businesses funding up to $1 million in exchange for a percentage of their future sales and a 2.0 factor rate payback.
It’s called the Oregon Royalty Loan Program and the factor rate cost is branded as a 2X Royalty. Eligibility is based off of historical sales and projected future sales.
“Oregon Royalty Loans are repaid at a predetermined percentage of sales / revenue on a monthly basis until an overall amount, typically 2X, is returned,” the State touts.
An official flyer for the program says that merchants only have to make the required royalty percentage up until they’ve paid 2x the funded amount in full, which could take up to 3-5 years, at which point the royalties stop. The flyer for the program also labels royalty financing as “revenue-financing” in its example at the bottom.
“The percentage of sales varies with each project, but will yield a 2X return from royalty payments over a three– to five–year period,” the State says. “Once the 2X repayment has been achieved, royalty payments stop, and the company has satisfied its repayment obligation.”
Promotional materials say that this may better align with a business’s cash flow.
In Oregon’s official business code, it defines Royalty in the program as “payments calculated as a percentage of the borrower’s sales or revenue as a means of effecting an adequate rate of return typically up to 2X on the monies loaned, as determined at the sole discretion of the Department.”
2X is deemed an “adequate rate of return.” The product is collateralized and personally guaranteed.
The program is similar to New York City’s Revenue-Based Loan Program heralded by Mayor Mamdani and the State of Washington’s Revenue-Based Financing Fund.
Parafin Has Funded 50,000 Businesses, How Does That Compare?
June 25, 2026Parafin’s new credit facility with Goldman Sachs was complemented by the disclosure that the company had funded more than 50,000 businesses since inception. Founded in 2020, Parafin typically markets how much it has extended in “offers” to small businesses rather than how much it has actually funded. This bucks the prevailing industry trend.
To put Parafin’s 50,000 deals funded over the last 5 years into perspective, the industry leading online lender, Square Loans, funded approximately 700,000 loans last year alone.
Parafin disclosed revenue in 2025 as $90M, which is approximately double that of Lightspeed Capital over the same time period. Lightspeed originated $340M in MCAs in 2025.
Parafin says that the majority of its fundings go to repeat borrowers. The company powers platforms such as Amazon, Walmart, DoorDash, Gusto.
Big Deals, Big Consequences: How some deals went very wrong
June 18, 2026In November 2018, a conglomerate of car dealerships went out of business in California. Within three weeks, a merchant cash advance company, 1 Global Capital, was discovered to have filed bankruptcy as a result. They had lost more than $40 million in that dealership deal alone. Over the ensuing weeks, additional funding companies revealed that they had also been in it and gotten burned, some so badly that they also closed their doors. It was a moment of reckoning for the industry as deals got bigger and the stakes got higher. At the time, it was considered the largest deal (and then the largest default) in history.
Less than two years later, an even bigger deal was revealed, a $91M MCA made by Par Funding. Par also became a rather infamous failed business.
And some time in between the two, a $1B hedge fund that provided credit facilities to small business lenders, also failed and took some lenders down with it.
In each case there was a lesson learned.
1 Global Capital
In 1 Global Capital, internal emails revealed that the company knew the dealerships were on the brink of collapse, but were compelled to keep funding them to avoid taking the loss.
“…if they were to become insolvent, everyone loses,” said 1 Global’s Director of Accounting. The result was they dug a deeper and deeper hole until they were on the hook for tens of millions and their exposure became existential.
1 Global was not forthcoming about the performance of its portfolio to its investors and by the time the dealerships went bust, regulators and prosecutors moved in to deal with the fallout.
Par Funding
In the Par Funding case, foul play appears to have been the defining issue. The large funding amounts and low defaults looked good to the investing public because the books were not being accurately reported. Par was adamant that the power of “compounding” could make up for any losses they incurred, but regulators said they had not even properly disclosed their losses to begin with and investors were not aware of them. The $91M deal was just the tip of the iceberg. Another customer purportedly owed $35M, for example. And then those combined with the next eight largest deals on their books added up to $228M, which made up 54% of their entire portfolio. Par had very severe concentration risk and compounding probably could not save it on other deals if these went bust.
Direct Lending Investments
In the Direct Lending Investments hedge fund case, the CEO had famously proclaimed that small businesses were overpaying for credit and that was how their investors stood to profit. But over time, it became evident that some of the small business lenders they backed actually had customers underpaying for credit and the losses overwhelmed the hedge fund. Unfortunately, the CEO was unwilling to concede the losses and told investors they were actually profitable instead. To try and cover it up and make it back, the hedge fund loaned nearly $200M to telecom companies at high interest rates. And because they made these loans during a state of distress and probably were not underwriting them carefully, the borrowers scammed them and disappeared with the funds. There was no longer a way out and the CEO resigned. The receiver in the case initially estimated that portfolio was then worth $500M less than what they had last reported to investors.
Ironically, the CEOs of all three companies were convicted of crimes for their roles in the lies and the losses.
Concentration risk, misleading investors, and falling victim to the sunk cost fallacy ultimately were their undoing. For some, the deals got larger to try and keep a dead deal from failing. For others, it was a Hail Mary play to try and generate a return to make up for losses elsewhere.
The Fatal Flaw in Upstart CEO’s Vision for AI Underwriting in MCA: A response to Upstart’s view of AI in underwriting
June 12, 2026David Roitblat is the founder and CEO of AI My Advance and Better Accounting Solutions, a leading authority in specialized accounting for merchant cash advance companies alongside our new innovative CRM designed to solve the critical gaps holding the industry back. To connect or schedule a call about working with AI My Advance or Better Accounting Solutions, email David@betteraccountingsolutions.com
As deBanked reported (March 23, 2026), Paul Gu, CEO of Upstart, said something on his company’s Q4 earnings call that has been quoted approvingly in a few corners of the credit world. It deserves a careful read because some important points are incorrect when it comes to the MCA industry.
Gu’s argument, as reported, runs roughly like this. Humans have never been very good at precisely underwriting loans and projecting cash flows. That problem has always been a math problem, not a language problem. The recent wave of AI, the LLMs from Anthropic, OpenAI, and Google, is good at the things humans are naturally good at: reading documents, navigating messy paperwork, perfecting liens, and checking property records. Therefore, in Gu’s framing, LLMs are well-suited to the operational layer around lending but not to the underwriting decision itself. He puts it bluntly: “No matter how many humans you have, you don’t want that army of humans underwriting loans for you.”
The deBanked piece does a real service by reporting it. But the framing carries a serious blind spot. It implies that AI underwriting is essentially a solved problem, owned by structured-data shops like Upstart, and that the broader conversation about AI in lending is mostly noise. For consumer credit, that may be true. For the MCA industry, it is not, and treating it as if it were misses the actual point.
Begin with the parts of his argument that hold up. Underwriting, at its core, is a probability problem. Given a set of inputs, what is the likelihood of repayment, and what is the distribution of outcomes if it fails? That has always been the question, and Gu’s phrasing is exactly right: “That’s something that has always been solved as a big math problem.”
He is also correct in saying that LLMs, in their current form, are not the natural tool for that math problem. They are extraordinary at reading, summarizing, classifying, extracting, and reasoning over language. They are not, on their own, the right architecture for portfolio-level probability estimation. The deBanked piece links to Upstart’s own track record, 91% of their loans now fully automated, and that result was not built on top of GPT-class models. It was built on years of structured-data modeling. Gu is entitled to point that out.
He is also right that the most obvious near-term wins from LLMs in lending are operational: HELOC processing, lien perfection, document review, title work. Anywhere a human currently spends hours reading and routing paper, an LLM can do meaningful work. His framing of those as “the perfect problem to throw sort of LLM-style AI against” is well put.
The problem is the conclusion the framing pushes the reader toward: that because the underwriting decision is a math problem, and because the new wave of AI is mostly a language problem, the conversation about AI in underwriting is largely settled. That conclusion translates poorly from Upstart’s world to ours, and it does so in a way that matters.
Upstart underwrites consumer installment loans. The data is clean, the durations are predictable, the borrowers are individuals with credit files, and the question being asked is essentially: will this person make 36 or 60 fixed monthly payments on time. That is, as Gu says, a big math problem with a long history of structured inputs.
MCA underwriting is not that problem. It is a different problem with a different shape, and the difference is not cosmetic.
An MCA underwriter is not pricing a fixed-term installment loan to an individual with a credit file. They are pricing a daily or weekly remittance against a small business’s future receivables, over a horizon measured in months, where the inputs are messy by nature: bank statements with idiosyncratic categorization, industry-specific seasonality, owner behavior that does not show up in a FICO score, stacking risk, processor changes, lease events, partner disputes, and dozens of other signals that live in unstructured form. The decision is not made once and then monitored passively. It is revisited continuously as the merchant’s behavior evolves over the life of the advance.
That is a different beast, and the math that solves consumer credit does not, on its own, solve it. The part of AI that Gu sets aside, the language part, the unstructured-data part, the continuously-observing part, is precisely the part that matters for the underwriting decision itself in MCA, not just the paperwork around it. Setting it aside is not a clean theoretical move. It is a category error when applied to this industry.
In modern MCA operations, the most important thing AI is doing is not the initial decision. It is what happens after the capital goes out.
Underwriting does not end at approval. Our new and up-and-coming platform continues to ingest merchant behavior after funding. It links directly to merchant bank accounts, monitors post-funding activity, tracks changes in deposit patterns and remittance behavior, and detects patterns across defaulted deals. It does not simply record that a deal failed. It identifies what those failed deals had in common. That information does not sit in a static report. It feeds directly back into how new deals are evaluated.
That is underwriting, too. It is just underwriting, not the single-moment, single-file decision the term usually evokes. It is a feedback system: the decision at funding is the first input, the merchant’s subsequent behavior is the second, and the model that prices the next deal is the third.
Gu’s framing treats underwriting as the moment of decision. In MCA, the moment of decision is a single frame in a longer film. The frames that matter most are often the ones after funding, where a human underwriter cannot realistically hold the pattern in mind across hundreds or thousands of merchants, while a system can. Any framework that ignores those frames does not describe MCA underwriting. It describes something else and calls it by the same name.
This is also where the LLM-versus-structured-model dichotomy starts to fall apart. Reading a bank statement well is partly a math problem and partly a language problem. Categorizing a $4,200 ACH out as a vendor payment versus a stacked advance from another funder is not pure math. It requires reading the counterparty name, recognizing the funder, knowing the industry conventions. That work sits exactly at the seam between what Gu calls “solved as a big math problem” and what he calls “the perfect problem to throw sort of LLM-style AI against.” In MCA, those two are not separable layers. They are the same workflow, and pretending otherwise produces a model of the industry that does not match how the industry actually runs.
The deeper point is that the AI conversation in lending is not one conversation. Upstart’s answer is the right answer for Upstart’s problem. It does not automatically transfer, and the confidence with which it has been quoted in the credit world suggests the transfer is being assumed rather than examined.
Consumer credit, where Upstart operates, has had decades of structured-data infrastructure built around it: bureaus, scores, standardized loan documents, regulated disclosures, and well-defined repayment behavior. A math-heavy, low-LLM approach makes sense there because the inputs were already structured by the time the modeling started.
MCA grew up differently. The data is unstructured by default. The borrowers do not have meaningful credit files in the consumer sense. The product is non-recourse against a fluctuating revenue stream. The lifecycle is short and active. The signal that matters often lives in places, bank statement memos, merchant behavior, processor data, partner disputes, that look like language problems and behavior problems before they look like math problems.
That is why the LLM-style AI Gu is comfortable assigning “around the edges” work, which, in MCA, frequently involves core underwriting. Parsing the statement is part of underwriting. Reading the memo line is part of underwriting. Recognizing the third stacked funder is part of underwriting. Watching how a merchant’s deposit pattern shifts in week three of an advance is part of underwriting. Those are not auxiliary tasks bolted onto a clean math problem. They are the problem.
The disagreement with Gu, then, is not that AI cannot underwrite. He is not really arguing that. His actual position is closer to this: LLMs are not the right tool for the underwriting math, and you should not let the hype around LLMs convince you otherwise. On that, we agree.
The disagreement is this. In MCA, the underwriting problem is a math problem wrapped in a language problem wrapped in a continuous-monitoring problem. The math is necessary but not sufficient. The language and behavioral layers are where modern AI, LLM-style and otherwise, is genuinely changing how deals are priced, monitored, and learned from. With our new and up-and-coming platform, AI My Advance, this is exactly what we do: we parse the unstructured inputs, track merchant behavior after funding, and feed what we learn from defaulted deals back into how the next deal gets priced. Treating that work as merely “operational” is not a small mistake. It is the kind of mistake that produces a confident answer to the wrong question.
Upstart has earned the right to its view. The 91% automation figure is real, and the underlying modeling is serious. But that view was built on a problem whose inputs were already structured. The MCA industry is solving a different problem in real time, and the tools that work for it are not the same tools, in the same proportions, as those that work in consumer credit. The sooner that distinction is named clearly, the better the conversation about AI in lending becomes.