Business Lending
QuickBooks Capital: ~$1.7B Funded Last Quarter, Repeats that AI is Not a Threat, But Rather an Advantage
May 21, 2026 Intuit’s QuickBooks’s capital originated about $1.7B in small business loans in Q3 FY 2026. That brings the total for the trailing nine month period ending April 30 to $4.3B. During the earnings call, Intuit CEO Sasan Goodarzi said “We are growing our line of credit offerings with buy now, pay later, directly embedded within QuickBooks, and the launch of Intuit business credit card.”
Like other software companies, analysts have been questioning the sustainability of their product offerings as AI looms large as a threat. Like the previous quarter, Goodarzi offered a rebuttal on this subject, expressing that they are effectively the AI solution customers would seek.
“It is important to recognize that businesses, while they use Google, they use LLMs to do searches, do queries, you cannot run your business with an LLM because you are managing your books, you are managing your money, you are managing your payroll, and accuracy and compliance of doing that matters,” Goodarzi said. “And running a business is mission critical. And so psyche of businesses is such that and accountants is that they need us to be their AI platform to provide expertise so they can run and grow their business.” Goodarzi cited Anthropic and OpenAI as partners they are already working with, for example.
Goodarzi also said that winning customers is not necessarily about the best software anyway, but rather about the confidence the assistance with the work instills in the customer. And given the integrations they have, the reputation they have, the AI power that they use, and ability to assist customers, this is where they are actually structurally advantaged.
Barney Frank Once Answered My Question About Business Loans
May 20, 2026 Former Congressman Barney Frank has died. He was 86 years-old. While he left Congress in January 2013, his legacy has lived on through the Dodd-Frank Act of 2010. Readers may recall that’s the law that gave birth to the Consumer Financial Protection Bureau and with that a debate that has spanned more than 15 years over how to implement its small business loan data collection mandate.
In any case, I once personally crossed paths with Congressman Frank in a hallway at the Exponential Finance Conference presented by Singularity University and CNBC. It was in 2014 and I had official press credentials. I had limited time so I fired away the first question I could think of and that was “would you be in favor of a federal maximum cap on business loan interest rates?” He said that he would not be.
Talking further about this subject, Frank went on to say that he supported transparency in business loan transactions, such that the borrower should be easily able to identify the terms, but that the premise behind consumer loan protections was that consumers were less sophisticated.
In a second question, I brought up overdraft fees and their tendency to be characterized by critics as short-term loans. Should a loan term of just a single day be required to disclose an annual percentage rate? He believed that they should.
This exchange and a summary of topics discussed at the conference appeared in the July/August 2014 issue of DailyFunder’s periodic trade journal. RIP Congressman Frank.
Square’s Q1 Gross Profit Growth Driven by Square Loans
May 12, 2026Block didn’t divulge the precise number of business loans it originated in Q1 2026 but did say that it grew. deBanked, which tracks online small business lender originations, estimates the number to be ~$1.9B.
“Square gross profit grew 9% year over year in the first quarter, driven primarily by Financial Solutions, most notably Square Loans,” the company said.
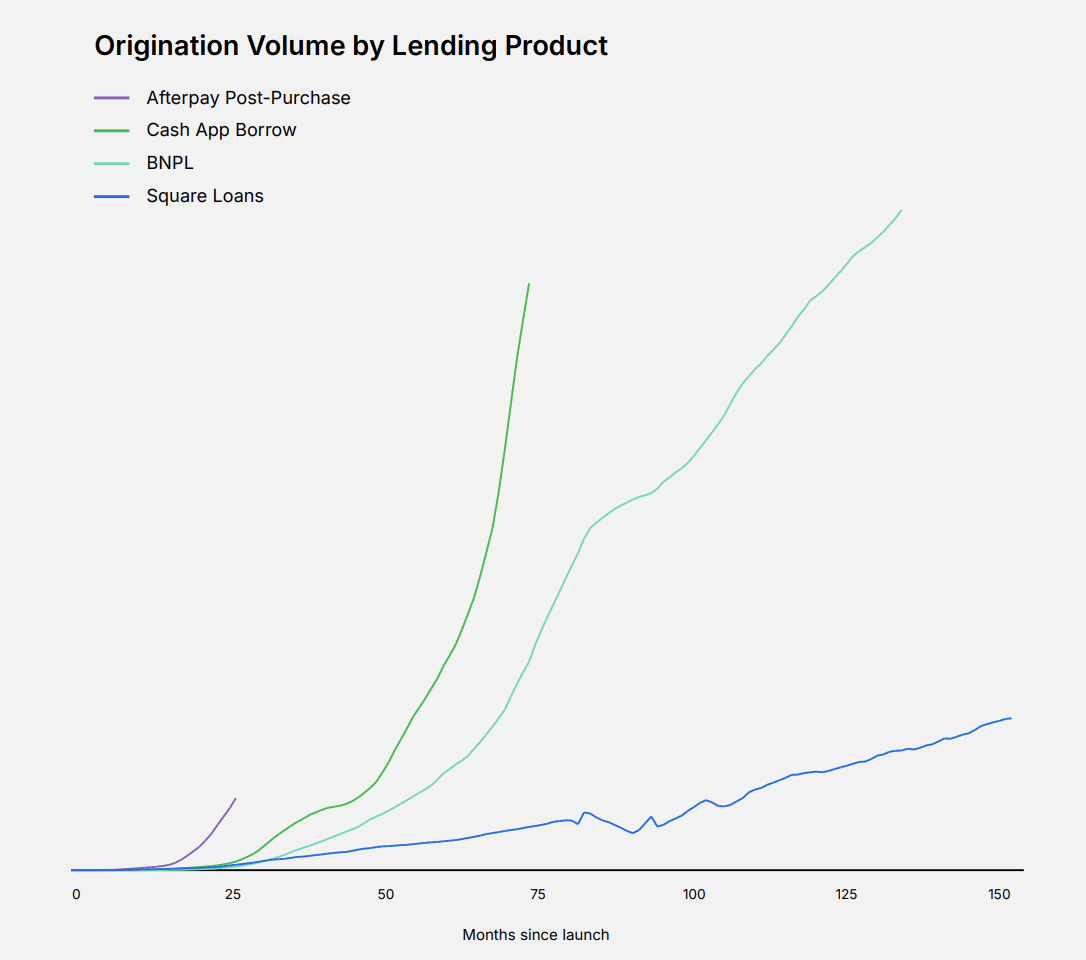
Lending has become a significant business for the company across all of its verticals. Consumer lending origination volume growth accelerated to 82% YoY, for example. Its “Borrow” product grew by 300% over that time period.
“Each new Block lending product has scaled originations at a faster rate than the last one,” the company revealed in its earnings presentation. A snapshot from that presentation is below:
LendingTree: SMB Lending Cools Slightly
May 7, 2026“When the war started in March and gas prices went way up, that was a shock to the system in that month specifically,” said LendingTree CEO Scott Peyree. “Now, on the small business lending side, I would say we are seeing a little bit of both—fewer small merchants looking for loans and smaller loan sizes than normal. On the lender side, credit is still available, but they are typically offering lower loan amounts at higher interest rates.”
Peyree believes this will correct on its own.
“When you have a cautious merchant to begin with, and then they are not getting the exact loan they want and at a higher interest rate, the sense we are getting is they are just not as urgently looking for money right now because of macro geopolitical stuff that is going on,” Peyree said. “I still think this is a short-term thing that will go away. Once consumer sentiment comes back up and, hopefully, things settle down geopolitically, I think we will be right back off to the races.”
Revenue from the small business segment of its business, however, was still up 49% YoY and they’ve brought on more people to help these businesses choose a solution.
“We have selectively added to our SMB concierge team to help more customers find the right financing options, while increasing the speed of application submission, approval, and funding,” the Q1 shareholder letter states.
Shopify Capital: $1.4B in Business Loans and MCAs in Q1
May 5, 2026 Shopify’s business loan and merchant cash advance offerings continue to increase. This follows a consistent decade-long rise with no down years. In Q1, the company originated $1.4 billion in business loans and merchant cash advances, up from $821 million YoY. Based on the weight of the respective receivables, the product mix is roughly 82% loan-based and 18% MCA.
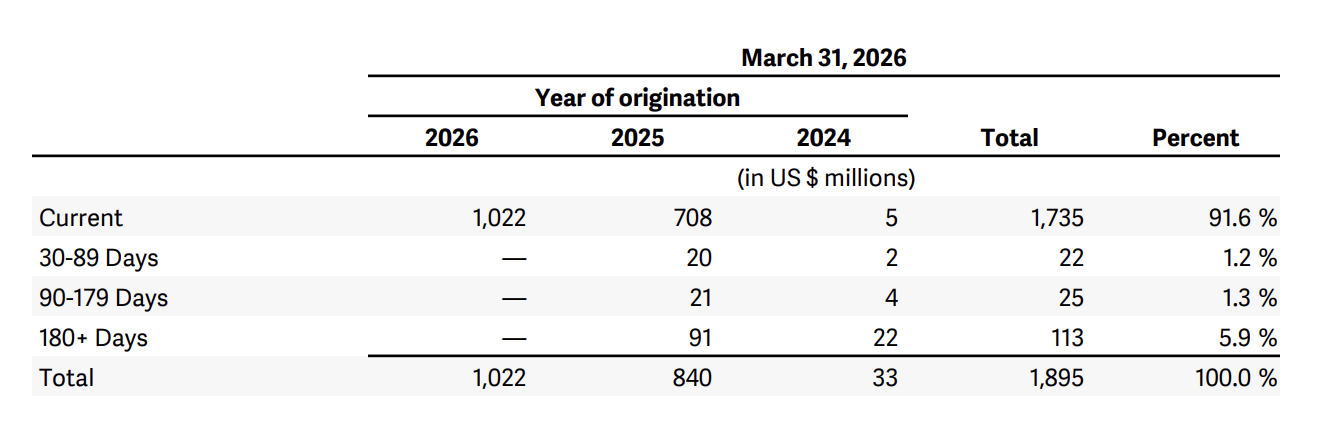
Of the loans it originated in 2025 that still have an outstanding balance, 10.8% were more than 6 months behind on their original payment schedule as of March 31, 2026.
Delinquency chart in in the Q1 docs:
Enova: $1.7B in Business Loans in Q1, New Record, Competition Hasn’t Changed
April 28, 2026“Our SMB business continued to deliver remarkable growth and stable credit as our leading brand presence, scale, and strong competitive position drove 42% year-over-year growth in originations to a record 1.7 billion dollars,” said Enova CEO Steve Cunningham during the Q1 earnings call. “Our SMB portfolio has grown 37% over the past year and remains intentionally well diversified across geographies and industries. In addition, the SMB net charge-off ratio remained in a tight range consistent with the past two years.”
The company indicated that economic signals look strong despite rising gas prices and that they expect the growth in SMB lending to continue.
When Kyle Joseph at Stephens asked Cunningham to size up the competitive environment they face in their sector, Cunningham said that they have the advantages.
Cunningham:
“The SMB market is large, and new business formation over the past five or six years has been really strong if you look at new business applications. Those companies that are a couple of years into their life and have shown staying ability become potential customers. So the market is growing, probably a little faster than the overall consumer market. Regarding our presence, brand, scale, and capabilities, our set of competitors has not really changed much over time, and we believe we have a lot of advantages. It is a great setup: a large, growing market and competitive advantages that allow us to be selective and generate growth that creates strong returns for us and our shareholders.”
Just the Facts With LendFax
April 1, 2026More than 76% of small business owners who apply for financing through their system do it from a mobile device. That’s the fax from LendFax, a one-stop shop for business owners (and consumers) to be paired with the most appropriate service provider for their needs. The information they submit through the curated intake process is pushed to their partners via API, and then LendFax continues to communicate with those customers to make sure they complete the process with them.
Nick De Jesus, LendFax’s Chief Marketing Officer, says that the process relies on enterprise-grade infrastructure to make it all work and is the culmination of years of in-house development and an obsessive desire to achieve the most optimal outcomes for all parties in the process.
“I’m working non-stop, 12 hours, 13 hours a day on this, 100% passion, I couldn’t see myself doing anything else,” De Jesus says of his time spent at LendFax.
That he’s there doing this at all is due to a chance intersection in his life. For example, De Jesus had been on an accelerated track in college and was bound for medical school at an extremely young age. His special area of study as a nineteen-year-old was heterotopic ossification and involved researching bone formation from trauma and soft stem cell tissues. And that was the path he had surrendered himself to until one night, a few acquaintances asked for his input on a tech project involving small business financing, thinking his broad knowledge could be insightful. But what De Jesus learned from them had him hooked immediately, and he dropped everything to be a part of it.
“I finished my cell biology exam and the next Monday I was in [their] office,” De Jesus said.
De Jesus says that they’re aware that LendFax isn’t the only operator of their kind in the space, but that by being lean and running efficiently, partners on their platform can get “enterprise infrastucture without the enterprise pricing.” Depending on the relationship setup, partners can get as little as a merchant’s qualified and completed application or as much as the entire deal with full docs, all managed by LendFax and ported into the partner’s CRM in real time.
De Jesus is a regular at the big trade shows and stressed just how important in-person relationships are in this field, but noted that the merchant side is different, that merchants looking for financing have trended toward solutions that produce the least amount of friction and interaction along the way.
“…things are moving definitely more to the digital landscape where people just want to go online, submit information, without even texting or talking or emailing anybody and get an answer,” De Jesus said. “So that’s kind of what we’re trying to do with LendFax, is we’re kind of just trying to bring them the offers based on the answer that they select.”
Eddie DeAngelis to Speak at Broker Fair 2026
March 31, 2026
Eddie DeAngelis will be speaking at Broker Fair 2026 in New York City on June 1. DeAngelis owns a high-performing small business finance brokerage.
About QualiFi
QualiFi’s journey is just getting underway and will be extraordinary. We get to push the reset button one more time and apply what we’ve learned from our many successes and failures. Our current mission with QualiFi is two-fold, and we’re inspired to make it happen. We’re determined to take the hassle out of small business financing by building an accessible, affordable #1 client experience for business financing, one client at a time.