Articles by deBanked Staff

DEBANKED?
October 14, 2026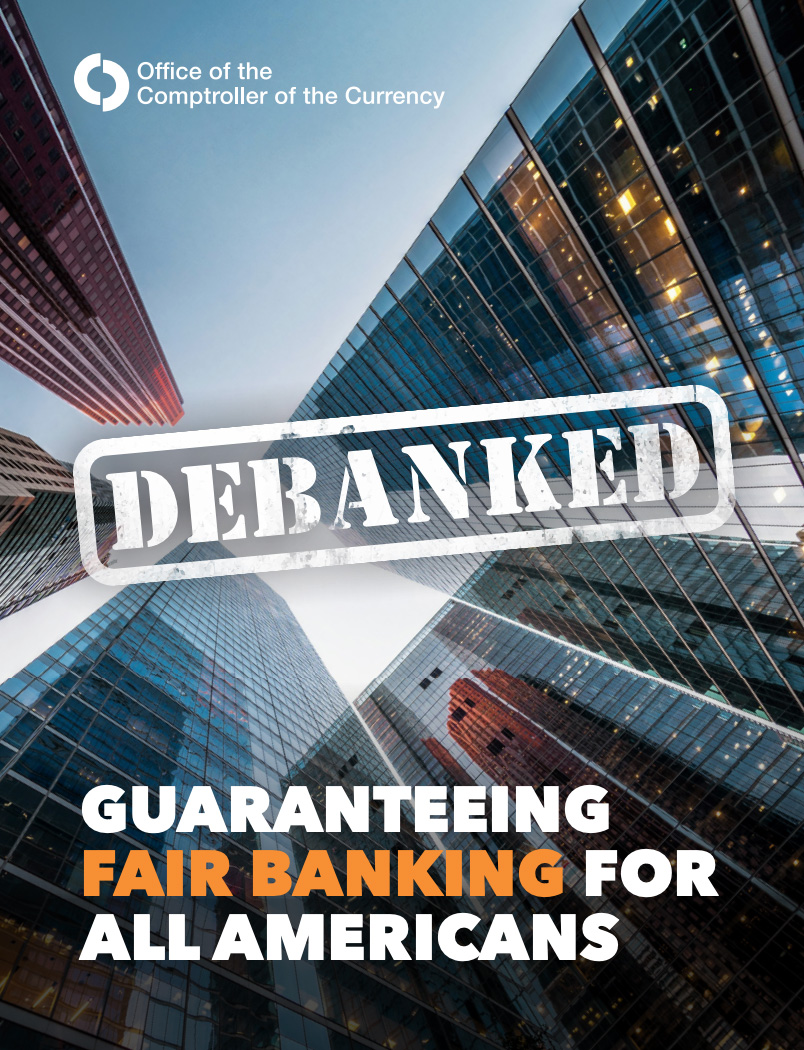
Imagine our surprise when it looked like another issue of deBanked Magazine had just been published…by a federal banking regulator. What actually happened is that the Office of the Comptroller of the Currency (OCC) published its final report on debanking, where its investigation determined that banks terminated or turned away customers on the basis of perceived reputational risk. OCC hopes to reduce or eliminate such practices in the future. “DEBANKED” is the signature headline printed on the cover. It would’ve fit in really well on our bookshelf had it been ours.
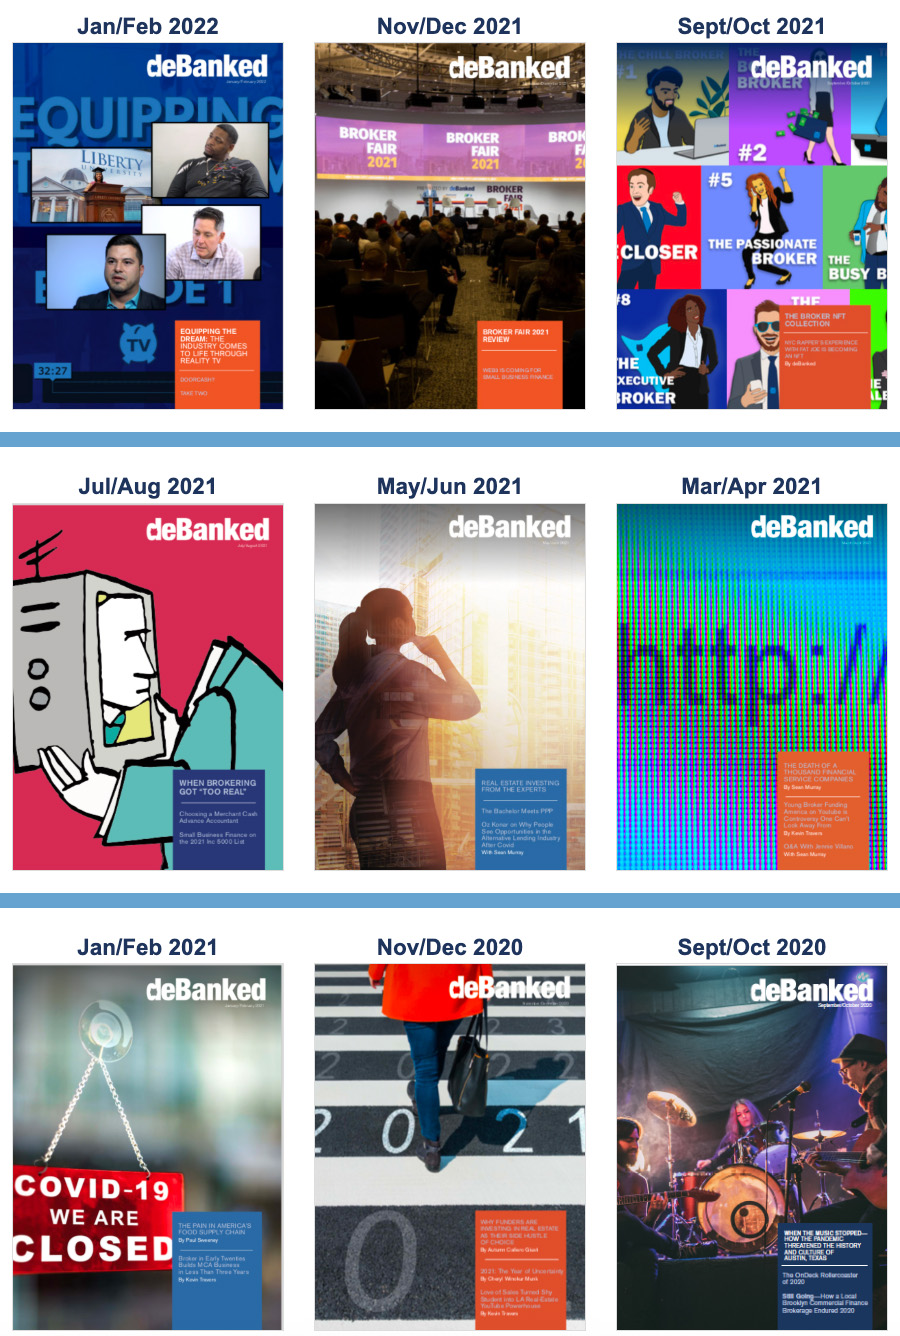
deBanked’s last magazine issue was published in January of 2022. All previous issues have been archived digitally here and print copies are still on display at our headquarters.
CFPB Reaffirms Excluding Merchant Cash Advances From Section 1071
October 13, 2026The CFPB recently published its annual Fair Lending Report. Under the section about small businesses, it reaffirmed its decision to exclude MCAs from the Section 1071 rule.
On May 1, 2026, the CFPB issued the final rule. The rule reduces the scope of “covered credit transactions” by limiting the types of transactions subject to reporting in order to focus data collection efforts on core lending products—loans, lines of credit, and credit cards—that are most utilized by small businesses. Accordingly, the rule sets forth certain exclusions: merchant cash advances, agricultural lending, and small-dollar business credit.
It further reiterated its decision to make other modifications to Section 1071.
In addition, the rule revises the definition of “small business” by reducing the gross annual revenue threshold from $5 million to $1 million. This will allow the CFPB to focus on collecting data related to micro and small enterprises, which are most relevant to section 1071’s goals. The rule also reduces the number of collected data points, extends and adopts a uniform compliance date of January 1, 2028, and simplifies the time and manner of data collection in order to allowinstitutions flexibility in how they comply with statutory requirements.
The rule updates are necessary to ensure reasonable implementation that does not restrict credit availability for America’s small businesses. The 2023 rule imposed a significant number of requirements that were not needed to advance the purposes of section 1071 of the Dodd-FrankAct. This rule recognizes those concerns and takes a more reflective approach, including just what the statute requires. The updates will result in cost savings for institutions and reduce the burden of data collection without sacrificing data availability.
Wells Fargo-supported Fund Aims to Refinance MCAs
October 8, 2026Sixty-one percent of all deals funded by Founders First Capital Partners went toward refinancing merchant cash advances. That’s intentional, according to the company, which just announced a capital raise of $19 million for one of its small business financing funds. Investors in the fund include Wells Fargo Foundation, Deutsche Bank Americas Foundation, Sunrise Banks, Community Reinvestment Fund USA, and others.
Founders First offers revenue-based financing, term loans, and hybrid loans that combine both. The company says borrowers that refinance their MCAs with Founders First experience an average effective APR decrease of 15 percentage points.
“To help meet that demand [of refinancing MCAs], Wells Fargo contributed $500,000 to Founders First, fiscally sponsored by Realize Impact,” a press release said.
Founders First does not advertise its own APRs, but according to a hybrid loan contract it originated in 2023 that deBanked obtained, it said that amounts collected from the revenue-based financing component of the loan should be excluded from interest and interest rate calculations and should not be considered when determining whether the loan exceeds a state’s maximum allowable interest rate.
Many of the company’s case studies tout the benefits of revenue-based financing. In one case, a borrower received $500,000 and grew revenue by 90% over 12 months. Founders First said that “revenue-based financing was ideal as the payments were increased during stronger revenue months.”
The company has deployed more than $20 million in capital, and 70% of its customers have increased their revenue. Its financing has also contributed to the hiring of more than 2,700 new full-time employees. Businesses can obtain funding of up to $2 million. In Founders First’s 2025 Impact Report, the company says its financing is better than SBA loans because borrowers do not need strong credit or assets. It also touts how more than half of its portfolio consists of refinanced MCAs.
True Food Kitchen Had $2.2M MCA Balance With Parafin Before Bankruptcy
October 7, 2026FRC Balance, LLC, which owns the True Food Kitchen restaurant chain, filed for bankruptcy this week. According to the company, True Food Kitchen has closed 12 restaurants, whose final day of service was Sunday, October 4. The company’s remaining 34 restaurants across 14 states are open and serving guests as usual.
Among the company’s listed creditors is Parafin, with an outstanding merchant cash advance balance of $2,206,502 reported in one of the bankruptcy filings. There is no indication that the MCA added to the company’s financial pressure (True Food Kitchen owes millions just to its food vendors alone, for example, and they cited organizational issues as the root cause). The balance is notable, however, for its size and for how the arrangement originated: through DoorDash Capital. deBanked was one of the first to discover DoorDash’s entry into MCAs in January 2022.
True Food Kitchen has been a poster child for DoorDash Capital since last year. In July 2025, DoorDash published a feature about the restaurant chain’s use of merchant cash advances. Titled How True Food Kitchen Used DoorDash Capital to Fuel Expansion, it opens by saying: “In September 2024, Peter Koumas, True Food Kitchen’s CFO, found DoorDash Capital while exploring the restaurant’s Merchant Portal, right as True Food Kitchen was in the middle of an exciting expansion phase, opening two new locations in Scottsdale, AZ, and Raleigh, NC.”
At the time, 10% of True Food Kitchen’s overall revenue came through DoorDash. The feature also noted that DoorDash Capital MCAs were provided by Parafin. In its bankruptcy filings, True Food Kitchen also listed a $1.8 million “MCA” balance with Rewards Network and a $7.1 million balance with InKind Credit, alongside debts to more traditional creditors.
Just a week ago, Parafin announced that it had been sold to Stripe for an undisclosed amount. It also revealed that it had originated $3 billion in funding since its inception in 2021. Until then, the scale of Parafin’s funding activity had been largely unknown. The True Food Kitchen bankruptcy now offers a glimpse of how large its exposure to a single client could be.
Counsel for the debtors said during a bankruptcy court hearing that they planned to reject Parafin’s contract and the payments towards it. True Food Kitchen blamed a combination of management turnover, changes in expansion strategy, failed investments, and product/branding issues as the reasons for its predicament.
Eighty Percent of Bluevine’s Customer Service Inquiries Are Resolved By AI Agents
October 6, 2026One striking detail emerged from Valley Bank’s acquisition of Bluevine: AI agents resolve 80% of inquiries to Bluevine’s Customer Care Center.
Many companies have touted their use of AI. For Bluevine, it also supports a key customer acquisition strategy: bundling business software into its banking platform.
“…we pack into the account a whole lot of software,” said Eyal Lifshiftz during the Valley Bank acquisition call. “So think about a small business that needs a lot of software to run their business: bill pay, invoicing, accounting, all of that. We just pack more and more software as part of the platform. So as a small business, instead of needing to rely on multiple sort of SaaS or online services, you’re able to integrate it all at once and everything magically works together.”
Opening a Bluevine account takes just five minutes, and AI now generates most of the company’s code.
“The majority of Bluevine’s code is AI generated today and approximately 80% of inbound client inquiries are resolved by AI,” said Valley Bank CEO Ira Robbins. “The team has built its own credit model, its own fraud, its own AML model, all supported by a single data layer that connects core banking and payment systems.”
Parafin Funded Over $3 Billion to Merchants in Five Years
October 1, 2026One of the key details revealed in the Stripe acquisition of Parafin is that Parafin originated $3 billion in funding since the company first started originating in 2021. Parafin supplied the financing infrastructure for platforms such as: DoorDash, Amazon, Gusto, SpotOn, Fullsteam, Jobber, and dozens more. Assuming the company experienced a normal growth curve, the company likely exceeded $1 billion in originations over the last 12 months, putting them roughly on pace with what Stripe’s own funding business was producing. deBanked previously estimated that Stripe Capital originated $1 billion in funding in 2025.
When the deal finally closes and Stripe Capital combines with Parafin, the resulting funding entity will rank among the largest online small business lenders in the country. Only Quickbooks Capital, Shopify Capital, OnDeck, and Square Loans will continue to be significantly larger, at least among the companies tracked by deBanked.
Valley Bank CEO Interviewed on CNBC About Bluevine Deal
September 29, 2026Following the Bluevine acquisition announcement, Valley Bank CEO Ira Robbins was a guest on CNBC where he was asked about the deal. Watch below:
5G Funding and its Owner Sued By SEC Over “MCA” Business
September 29, 20265G Funding represented that it had a profitable MCA business. But according to a lawsuit filed against the company and its CEO by the SEC, that was far from accurate. “The Portfolio was never profitable,” the lawsuit says. “5G Funding collected the full amount due on only about 30 of the 184 merchant cash advances.”
5G Funding formed in 2021 and by mid-2023 was insolvent. The company had raised $4.5M from 23 investors. Much of those funds are alleged to have been misappropriated by 5G’s owner and were used to “pay a down payment on a home, to pay his personal gambling expenses, and to purchase cars and watches.”
The SEC has sought relief on two securities fraud counts.