
 |
Phone: 844-222-6737 Learn More |
 Since: December 2015 |
Potential Match Found in deBanked UCC Filer list
| Company Name | Phone number | UCC Alias 1 | Alias 2 | Alias 3 | Alias 4 | Alias 5 |
| Accord Business Funding | 713-529-2570 |
Stories
Accord Business Funding Makes New Marketing Hire
April 3, 2018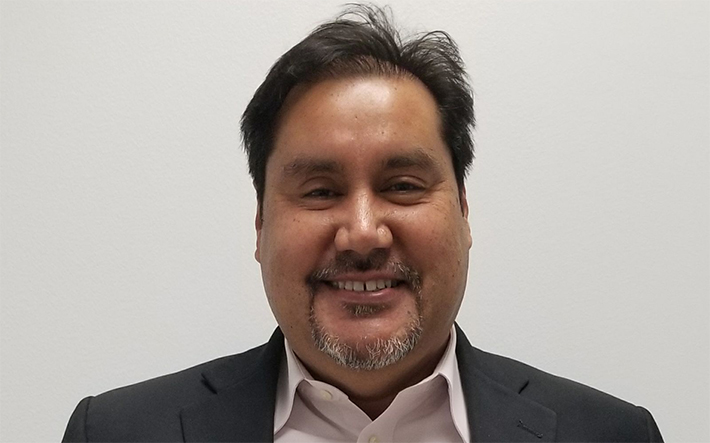 Houston-based Accord Business Funding recently hired Aldo Castro to lead its marketing efforts. His title is Vice President of Sales & Marketing.
“We are excited to have Aldo join our team,” Adam Beebe, co-founder of Accord Business Funding, told deBanked. “Aldo comes to us with over twenty years of experience in business-to-business sales and marketing experience… [and he] will use his experience and feedback from the ISO community to help Accord find new ways of adding value to our partners’ businesses.”
Prior to Accord Business Funding, Castro worked as a strategic marketing consultant and co-founded two digital marketing agencies in Texas. Founded in 2013, Accord is a B paper funder with terms between four to eight months and merchants that include auto dealers and trucking and construction businesses, among others. The company of 20 employees is entirely driven by ISOs.
“Accord offers our ISO associates a unique combination of integrity, speed, and flexibility, helping them close their deals faster and easier,” Beebe said.
How Scammers Could Defeat Your Time-In-Business Underwriting Requirements
August 5, 2026 The TIB checked out on the application and with the Secretary of State (SOS). The company had been in business for almost exactly five years—comfortably beyond the minimum underwriting guidelines. But its online footprint looked much weaker, almost as if the business had opened yesterday. Maybe it had. Or maybe the business did not actually exist at all, and the validated corporate records were simply part of a sophisticated fraud designed to slip past the gatekeepers.
But if something were really wrong, how could one explain the SOS-verified TIB?
“Ever heard of a Shelf Company?”
That was a question posed by Jamie Parker, CRO and co-founder of Heron Data.
A shelf company, or shelf corporation, is a legal entity that is formed, registered, and then placed “on the shelf” to age. At some point in the future, the entity may be sold, potentially allowing the buyer’s company to appear older than it actually is. Online forums such as Reddit, BiggerPockets, and CreditBoards contain years of discussion on the topic, including strategies, success stories, and failures.
According to Parker, there is a perception online that an older entity can provide a shortcut to obtaining business credit that a party might not otherwise qualify for. Anyone who follows the rabbit hole of shelf-company discussions will inevitably find websites that sell them.
Parker found himself on one such site. It listed the names of entities available for purchase along with their respective ages, and he became curious about what he could do with the information.
“I looked at that and so I went through all the archives, the Wayback Machine, I looked at all of the ones that had been sold in the last, like, five years,” Parker said.
He ran a test, searching Wayback Machine to determine which entities had been sold and whether any had later surfaced in the State courts as a defendant in a lawsuit with an MCA funder. He quickly found one: a business using a shelf entity that had received funding, defaulted, and was being publicly sued for breach of contract by three different funders.
“Time in Business, pretty much everyone has some policies,” Parker said. “The source of truth for Time in Business is considered to be the Secretary of State.”
Parker said that information alone may not be enough, given how freely advice about circumventing company-age requirements is proliferating online. It can be important to go one step further.
“So in the Secretary of State it will give you some information like when the business was formed, when control changed,” Parker said. “If whatever owner changed or the offices changed three months ago, that’s a flag. But you really have to get into the weeds for that.”
That is particularly true when underwriting teams perform every review manually. Parker noted that Heron’s technology can already retrieve that pertinent information as part of its system, however.
“…maybe you compare your Time-In-Business check with when the office has changed, and if the office has changed less than a year ago, that you’re probably not going to auto-decline, but you are going to want to just make sure that there hasn’t been like a significant change in control of the business,” he said.
Shelf companies are not a new phenomenon. In Parker’s view, however, the pace of underwriting in the small-business finance industry is rapidly approaching the speed of consumer lending. As automation begins to replace certain manual processes, seemingly minor tricks employed by applicants could derail the entire model.
For example, the buyer of a shelf corporation could use it to open a bank account and season that account with circular deposits and withdrawals over several months, creating the appearance of legitimate sales and expenses. In that scenario, there is a real legal entity with real bank statements, resulting in a more sophisticated form of fraud.
“You’re making faster and faster offers, you have less time for humans to look at stuff. This is the kind of thing that you’re going to get caught by,” Parker said.
In a social media post about the topic, Parker said, “Compare the transactions with the industry – if it’s a restaurant with only ATM deposits and checks, it merits further investigation. If you see lots of card deposits, that’s more likely to be safe. Look for signs of business activity – Facebook, Yelp, SAFER, whatever you would expect given the industry.”
Parker said Heron can automate those checks as well.
When it comes to company age, most scammers already understand that a corporation that does not exist—or one that was formed the night before—is unlikely to make it past the starting line.
“[Criminals] know funders care about Time In Business, they know funders care about revenue quality or whatever, and gaming that system,” Parker said. “So… you’ve got to be more proactive if you want to kind of keep up, because automation opens the door to more of this fraud.”
Need Capital for Your Funding or Lending Company? 3Jane Does it On Blockchain
July 27, 2026“I’m a big believer in agentic capital markets. I think we’re going to see a Cambrian explosion of novel primitives, driven largely by two pieces. Today, it’s just very easy to construct arbitrary financial building blocks using smart contracts,” said Jacob Chudnovsky, Founder of 3Jane, to deBanked.
3Jane provides credit facilities and forward flow arrangements across a range of products, including consumer loans, small business loans, and even merchant cash advances. The company previously provided a $10 million senior warehouse facility to consumer lender LendSwift, for example, and followed that with an inaugural $8.5 million purchase of small business loans from Slope, an embedded credit infrastructure provider that powers business lending programs for major players across the US, including Amazon. According to Chudnovsky, 3Jane would like to do even more deals in the small business lending and MCA space.
But with a twist.
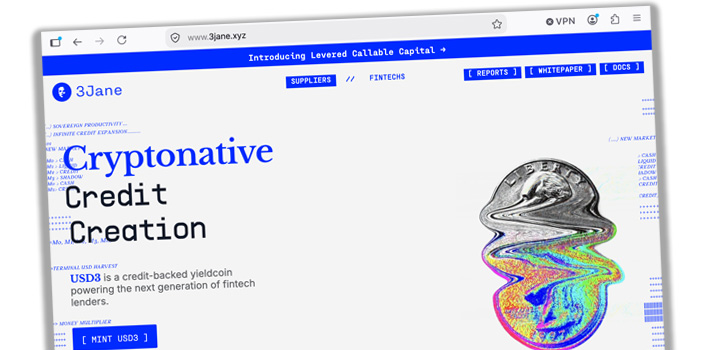 3Jane has built an entire protocol on the blockchain. It offers a credit-backed “yieldcoin” that earns its yield “from warehouse facilities, forward-flow programs, and credit-lines.” Investors can mint the coin on Ethereum, and it earns a yield backed by the performance of 3Jane’s credit assets. Minting is not open to US investors, but the company’s capital markets offerings are focused exclusively on North America. So, if you’re a small business funder seeking a credit facility or forward flow arrangement, 3Jane wants to speak with you.
Chudnovsky is a software engineer by trade and entered the DeFi space in 2020.
“…around 2024, I basically came to the realization that credit is still an extremely underdeveloped vertical in crypto and particularly both the capital aggregation and the capital distribution side of it,” he said. “My initial focus was ‘can we get the best of crypto to distribute capital in a better way?’ and so I founded 3Jane, and we started off by doing unsecured lines of credit for crypto users in the United States who had a bunch of these different assets and could not really borrow against it in a streamlined way.”
 That effort eventually led to 3Jane’s current business model. If the name 3Jane sounds familiar, it’s because Chudnovsky drew it from the 1984 novel Neuromancer, the famous William Gibson book that coined the phrases “cyberspace” and “the matrix.” By pure coincidence, Apple TV is releasing a 10-episode series based on the book in January 2027.
“I just think we’re going to enter this complete renaissance of new different financial primitives and I think it’s going to drive a lot of adoption, new ways of thinking about our financial system and that sort of really resonated with me with the book,” Chudnovsky said.
And that new way of thinking is starting to take root. The capital markets utilizing blockchain to create efficiencies is already cropping up around the industry. Since 3Jane last spoke with deBanked, its purchase of embedded finance products from Slope has increased to a total of $60 million.
3Jane’s customers do not need to be crypto experts. The company handles that side of the transaction while underwriting the risk and executing what is otherwise a conventional capital markets deal, but one in which the infrastructure is robust enough that this can be a lender’s first and last facility. On 3Jane’s part, doing this requires a strong understanding of the various financial products it evaluates, including MCA.
“…there are a number of MCA operators in the United States that are doing things right, they’re growing significantly and they need leverage to scale their business,” Chudnovsky said. “and so warehouse facilities and to a lesser extent forward-flows for MCAs sort of equally make sense for them as long as you are cognizant of the risks.”
American Brokers Help Fuel Canada’s Small Business Finance Boom
July 10, 2026 Canada’s small business finance industry is growing, and behind the scenes, American brokers are helping fuel that momentum.
“They’re kind of killing it here right now, from what we see from the partners that we work with,” said Vlad Sherbatov, President & Co-founder of Smarter Loans, an online lending marketplace in Canada. “…for the American players that have come in, they’re already really good at the broker channel.”
Some Canadian small business funders, particularly those offering an MCA product, told deBanked that a significant amount of deal volume is coming from south of the border. And with that, the environment and culture of the business itself is beginning to shift. In their view, it is becoming more Americanized.
“…a lot of the Americanization of the industry, if you will, is coming from US brokers and funders,” said Avrohom Bernstein, CEO at 2M7 Financial Solutions.
Part of that shift is a new level of competition among firms as brokers try to maximize the options available to their clients. Bernstein, for example, said it often starts with an American broker inquiring about submitting a few Canadian deals. Lately, however, it’s been escalating into situations where eight different brokers might submit the same clients.
“Every deal now you’ve got to hustle, you’ve got to fight, you have to really work it,” Bernstein said.
That competition once meant fighting to become the one and only exclusive partner for a merchant. Now, it has become more common to find that a submitted applicant already has multiple active advances.
“…that used to be unheard of in Canada, like that used to be excessively unusual to see more than three positions, now ten is not insane anymore,” said Bernstein. “It really escalated in a way that we haven’t seen, and that’s probably over the last 12, maybe 24 months, that it started really picking up,” Bernstein said.
Jodi Levy, Head of Sales and Business Development for BizFund in Canada, said she has made a similar observation. When she first started in the industry there, something like a third position was unheard of. Now, she said, they see it much more often.
“I feel like that’s definitely more an American influence,” Levy said.
BizFund has a large American operation as well, so the company is no stranger to how things work on the other side of the border. But like others, its Canadian funding arm also works with the American broker community.
“…partners are great, American, Canadian, we don’t care where you’re from, as long as you’ve got good business,” Levy said, adding that what matters is whether those partners have a direct relationship with their merchants. She also said that working with the broker community requires operating with a sense of urgency, something she has instilled in her team as a culture of NOW.
The diversity of products brokers can offer may not be as wide as what is available in the US. Sherbatov said that once a business steps outside of traditional banking sources, it is essentially entering MCA territory. As a result, much of the new competition entering the space is focused there.
“Among the new players that have come in, MCA is definitely the product that they’ve been leading with,” Sherbatov said.
“We have like five or six banks, and then like a couple credit unions, and then there’s not really anyone between, and there’s A-paper guys, and then B, C, D type of guys,” said Bernstein of 2M7.
According to Statistics Canada, banks provided 68.5% of all capital to SMEs in 2023, while credit unions and government institutions provided 20.6% and 9.4%, respectively. Only 2.2% was funded by “online alternative lenders.” The total market size at the time was estimated at $94 billion.
“I think the big gap is—there’s tons of businesses that want capital,” said Rafael Rositsan, CEO and co-founder of Smarter Loans. “There are some funders that offer it, but they’re pretty tight, and I feel like if somebody can come in and take on a bit more risk and open up their books a bit, then there’s plenty opportunity to fund a lot of Canadian businesses.”
 As for why there has been such a push from Americans into Canada, no one pointed to a single definitive reason, but the runway for growth in the alternative lending segment, as illustrated by the report, may provide a clue as to the interest. Bernstein of 2M7 said there has long been a pattern of Americans entering and exiting the Canadian market, but he had also long believed that sustained success required boots on the ground. Now, he is reconsidering that view, at least on the broker side, as the current wave of broker entrants appears to be holding more firm. For funders, however, he said it still does not really work as a remote business.
“Every funder that’s actually doing decent volume is here, except for one,” Bernstein said.
In 2019, deBanked held a conference in Toronto for what was then a burgeoning small business finance industry, but held off on further events there after Covid disrupted plans for 2020 and 2021. It did not go unnoticed, however, that deBanked’s more recent American-based events have had more email addresses ending in .ca on the attendee lists. At the most recent Broker Fair conference in New York City, for example, some firms were exclusively advertising Canadian funding products to American brokers.
Canada’s population is relatively small, at roughly 41 million residents. That is about the size of California and only 25% larger than Texas. Homegrown Canadian brokerages do exist, of course, and a lot of business in Canada stays within Canada. Not all of the deals are originating through brokers either. Some merchants prefer to work directly with a funding source, while others prefer the comfort of applying through a Canadian lending marketplace like Smarter Loans, for example. If a merchant is ultimately eligible for some kind of funding, Sherbatov said, they are going to know it through their platform.
“We love the fact that we can help the small business economy thrive in the country, it’s responsible for a lot of positive things,” Sherbatov said. And whether the funding sources originate from Canada or the US, he said those companies ultimately find their way to them.
“We’re just becoming a more critical part of that journey for the merchant, and I think that explains why a lot of the new companies, when they come in, they gravitate toward us,” said Sherbatov. “…because in the business financing space we’ve carved out a nice niche for ourselves after Covid, and usually the new players gravitate to us because they know that merchants come to us as well.”
Levy of BizFund said part of the Canadian business experience is kindness. “That stuff goes far, we love that stuff up here in Canada,” she said. On the company website, photos of the company’s team, including Levy, show them smiling and ready to fund businesses.
For stalwarts like 2M7, which launched in Canada in 2008, the market’s evolution has been dramatic. Bernstein said the industry has gone from being a bit quiet and under the radar to seeing a lot of energy recently, whether from American brokers or from Canadian brokers that have decided this is the niche they are going to focus on entirely.
“In the US, I know a lot of brokers who also do equipment and also term loans and also SBA and also all this other type of stuff, it doesn’t exist so much in Canada,” Bernstein said. “It’s like if you’re selling to small businesses and you’re offering them financing, there’s not that many products you could line up, so it’s like if you’re doing brokerage, you got to be all in, like if you’re doing MCA, you got to do MCA.”
“I think that it was evident to a lot of players outside of the market that there is a big market opportunity that’s untapped,” Sherbatov said, “just because so little financing is being released by alternative lenders, that they started to come into the space, and we’ve seen, I mean, not even for the past two years, but I’d say in the past 18 months, our own roster of business lenders on Smarter Loans has doubled, like we went from 10 to where now we have 20, and the majority of that expansion actually happened from US players coming into the country.”
And the growth is just getting started.
“There’s a lot more room for it,” said Rositsan of Smarter Loans.
SoFi’s Small Business Loan Product Details
July 2, 2026SoFi is now a small business lender, according to their most recent announcement.
But they’ve been in this market for a while. They first flirted with the idea in February 2023 and then launched a marketplace in January 2024 to warm up to it. As a marketplace, they referred their own customers to other direct providers of capital, including MCA companies. Under this new program, applicants will be evaluated for a SoFi business loan first and then referred to their marketplace if they don’t qualify, second. Fundbox is referenced by name as one of the possible destinations for these applicants.
SoFi’s in-house business loan comes with a max APR of 36% and dollar ranges of $2,500 – $250,000. They’re personally guaranteed and have max terms of 2 years. Applicants need not be a SoFi customer to apply and funding can take place in as little as 24 hours.
Fundfi Merchant Funding Ends the Year with Two New Product Launches in the United States
December 15, 2025December 15, 2025 — Fundfi Merchant Funding has launched two innovative financial products, marking a significant expansion of the company’s solutions portfolio. The new loan product and credit splits program provide businesses with enhanced flexibility and multiple pathways to access capital for growth and operational needs.
Both products, now available to qualifying merchants, have been developed in response to evolving small business needs and direct feedback from Fundfi’s client base. They offer competitive terms and streamlined processes specifically tailored for small and medium-sized businesses.
Innovative Financing Solutions
Fundfi’s new loan product provides traditional financing with terms designed specifically for merchant operations, supporting businesses with capital for expansion, equipment purchases, inventory management, and working capital needs.
“We’ve listened closely to our partners and identified clear gaps in the market,” said Efraim Kandinov, Co-Founder and CEO of Fundfi Merchant Funding. “These new products reflect our commitment to providing flexible, practical funding solutions that align with how modern businesses actually operate. The credit splits program, in particular, offers a payment structure that moves with your business when sales are strong, you pay more; when they’re slower, your payments adjust accordingly.”
The credit splits program represents an innovative approach to funding repayment, allowing businesses to allocate credit card processing revenues toward funding obligations. This seamless integration between payment processing and capital access creates a natural cash flow alignment for merchants.
“Our clients have varied and evolving financing needs, and a one-size-fits-all approach simply doesn’t work anymore,” said Natasha Dillon, Co-Founder and CFO of Fundfi Merchant Funding. “These products allow us to better serve businesses at different stages of growth and with different capital requirements. Whether a client prefers a traditional loan structure or the flexibility of credit splits tied to their daily sales, we now have solutions that work for them.”
Comprehensive Financial Partnership
The dual product launch demonstrates Fundfi’s commitment to innovation and responsiveness in the revenue-based financing space. While these new offerings are only available in the United States, company leadership has indicated that this represents part of a broader strategy to position Fundfi as a comprehensive financial partner for small businesses.
The new offerings complement Fundfi’s existing suite of financing solutions, providing business owners with multiple pathways to access capital based on their specific circumstances, goals, and cash flow patterns.
About Fundfi Merchant Funding
Fundfi Merchant Funding provides innovative financing solutions to small and medium-sized businesses across the United States and Canada. With a focus on flexible terms, responsive service, and business-focused solutions.
Online Search is King for How Merchants Shop For Funding, Survey Reveals
June 4, 2025Perhaps the most surprising statistic to come out of a 2025 small business lending survey conducted by IOU Financial is that 12% of merchants said they started their search for business funding options from a cold call. But as one might expect, phone calls are not necessarily the direction in which business is moving. Forty-one percent of respondents, for example, complained that they received too many phone calls from multiple reps.
The number one origin point—far above cold calls (12%), friends/referrals (8%), and social media (7%)—was online search (63%). And they’re not just looking at the first website and firing off a form. Fifty-eight percent, for example, said that online reviews were among the most valuable factors in choosing the right business funding provider, while loan calculators and comparison websites/tools also weighed heavily at 49% and 40%, respectively.
Historically, online search primarily meant Google, but according to a TD Bank survey, 30% of small business owners are already turning to AI assistants like ChatGPT for insights on financial health or financing.
And most merchants skip their bank. “More than 70% of small business owners do not apply for business funding with their bank before exploring non-bank options,” the IOU survey found. “This trend highlights a major shift in trust and preference away from traditional banks and toward alternative lenders—which could be driven largely by the desire for speed, flexibility, and ease of access.”
Carl Brabander, EVP of Strategy for IOU Financial, discussed some of the recent findings of this survey at Broker Fair 2025 this past May in New York City.
Eight Individuals Arrested by FBI in Small Business Loan Carroting Scam
April 18, 2025 Eight individuals have been arrested by the FBI and charged in connection with a scheme to defraud small business owners out of millions of dollars by charging them money in return for a promise of a large line of credit that would never come.
The individuals charged include: Joseph Rosenthal, Matthew Robertson, Nicholas Smith, James Missry, Paul Cotogno, Blaise Cotogno, Adam Akel, and Nicholas Winter.
As part of the alleged conspiracy the group used the following domain names: oakcapitalgrp.com, oldbridgefunding.com, wsfcap.com, opticapitalgrp.net, and more.
In addition, they used company names and entities that include: Clover Advance Group LLC, FFCG LLC, Advance Source Capital Group dba ASF Capital, WSF Capital Group, Forward Advance LLC, Delta Fund Grp, Oak Capital Grp, United Front Capital, Quick Call Capital, Pine Equities, D&D Equities, ASC Group LLC, and Old Bridge Funding.
“For some victims, the Defendants sent some of the Defendants’ funds to bank accounts provided by the victim,” the criminal complaint states. “The victim was instructed to then repay that same money back to the Defendants over several days, which would in turn improve the victim’s credit score, making the victim more credit-worthy. Further, to secure the loan or line of credit, the victims were required to make a larger, one-time payment comprised of the victim’s own money, which the Defendants typically referred to as a balloon payment. Once the Defendants had recouped their own funds and obtained the victim’s own money via the balloon payment, the Defendants did not extend financing to the victim. Instead, the Defendants kept the victim’s money and broke off communication with the victim.”
The scam had been going on for almost four years, according to the criminal complaint. Several of the names listed above had circulated on an industry message board as likely being involved in a bait and switch LOC fraud scheme.
“These defendants perpetrated a years’ long scheme to defraud hard-working business owners in New Jersey and across the United States, stealing millions of dollars from thousands of victims,” said U.S. Attorney Alina Habba. “These charges reflect our Office’s commitment to holding accountable those who prey on small business owners trying to support their communities and earn a decent living.”
Accord Business Funding | Direct Funder | ISO Partners | Up to 15 Pts Per Deal... accord business funding is a direct funder based in houston, tx. no brokers. no middlemen. we make decisions in house and we fund fast. if you are tir... |
Small MCA & Auto files welcome... open to reviewing small mca and auto related files at accord business funding. soft pulls. straightforward process. feel free to reach out.... |
New Program: 3% SPIFF, Up To 15% Commish, FREE to Merchant, $3,000 Digital Mkt S... accord business funding is excited to announce the new texas pilot program, texas 3+free. sign up today at www.accordbusinessfunding.com. (https://l.f... |
See Post... thanks @showtime73. @quickbizpartner, feel free to reach out and i'll send over our current guidelines., , i consider you a paper .... |
See Post... accord business funding) are still funding.... |
See Post... accord requires a minimum of 6 months in business, $15k monthly deposits, and 500+ credit score. send it over and we'll see what we can do., , you dec... |