SBA
A Path Forward to do More SBA 7(a) Loans
October 13, 2026 “We just saw the SBA’s final year end numbers, and the [7(a)] loan count fell over 27%, the volume is down about 12% and ironically, the average loan size is up by 21%,” said Chris Hurn, CEO of Lendesca. “Well, that’s probably a direct result of ‘it’s not as easy and simple to make these small loans like it was in the recent past.'”
The shift follows changes the SBA announced last year to reduce default rates, including a return to more conservative underwriting criteria for smaller loans. As average loan sizes have increased, the agency has also sought to raise the maximum loan amount from $5 million to $10 million.
Other changes may have contributed to the decline in lending, including the new 100% citizen ownership requirement and economic uncertainty surrounding the tariff debate earlier in the year. For businesses already using merchant cash advances or factoring, changes to the SBA’s refinancing rules have further complicated access.
The SBA initially made those obligations ineligible for refinancing with an SBA loan. Its new SOP, effective October 1, reopened a path for merchant cash advances, but only after a business refinances the advance into a term loan and makes payments on that loan for two years.
“When the original SOP came out and said ‘you couldn’t use SBA 7(a) debt to refinance an MCA,’ I felt like that was a bit misguided because, candidly, you were taking away one of the few lifeboats that’s out there for folks who are trying to get off that hamster wheel,” Hurn said.
Hurn believes the revised guidance gives those businesses a route back to SBA financing while creating an opportunity for non-SBA lenders to provide the term loan that bridges the two.
“Wait the 24 months, and then hopefully they’ll be eligible to be taken out by an SBA 7(a),” he said.
That route, however, begins after a business has already taken on an MCA. Another way to address the problem is to make SBA financing accessible earlier, before a business turns to faster, higher-priced funding. For Hurn, that means shortening the application and approval process while meeting the program’s requirements.
 That is the work Lendesca is pursuing as an originating Lender Service Provider. Hurn has all the experience required. He previously founded and led Fountainhead.
“We actually have multiple bank clients—soon to actually have some non-bank clients as well, who hire us to not only do the traditional LSP services but also predominantly to do the origination,” Hurn said. “Whereas that funding source, that balance sheet has the final say, and they’re the lender of record, of course. But it’s really kind of bringing a true fintech sponsor bank type partnership into the government guaranteed lending arena.”
Using Lendesca’s technology, Hurn said, the company can move from an initial conversation with a prospective borrower to an automatically generated conditional approval letter in less than two hours.
“It can actually even take less [time] if, in fact, we’ve timed it right,” Hurn said. “And the loan summary gets to our credit people as quick as possible. And I don’t think that’s ever been done before in the SBA space.”
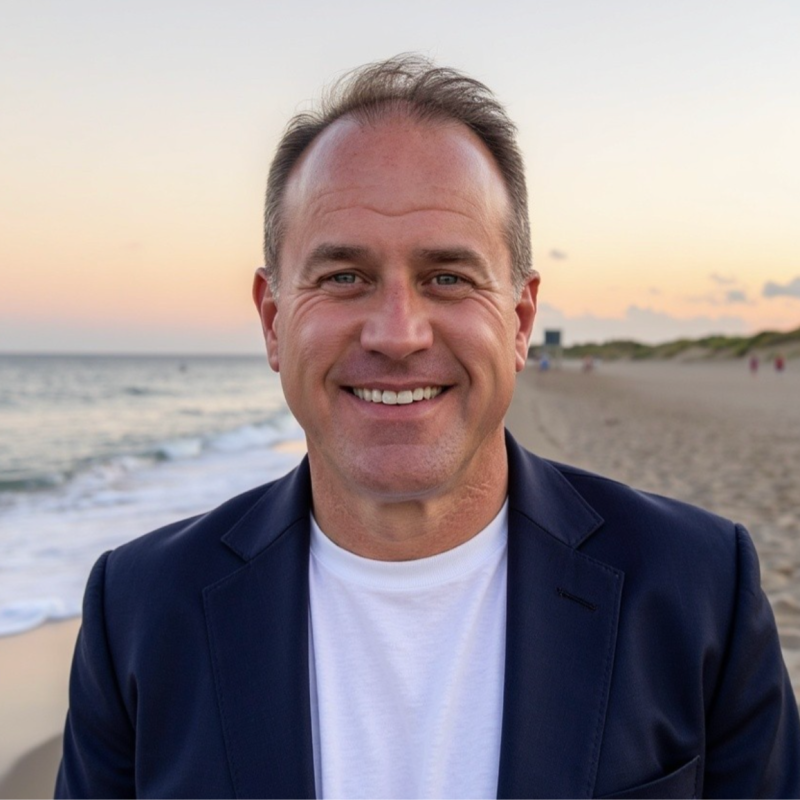 The initial call is recorded, automatically transcribed and analyzed, with information from the conversation incorporated into the credit memo. Borrowers and referral sources can then upload supporting documents.
“Then we allow our borrowers or brokers, referral sources to drag and drop the preliminary information that we need,” he added. “These are things like the personal and the business tax returns, the interim financials, personal financial statement, debt schedule, use of proceeds, things of this nature, basic stuff. Drop and drag that in.”
Lendesca’s business development team reviews the material and makes any necessary edits.
“…taking all that data and pushing it through to an SBA-compliant credit approval memo is another big factor in how you shorten the timeline for an SBA loan,” he asserted. “So that’s actually the tech that we’ve developed.”
For Hurn, the value of that speed extends beyond Lendesca’s own operations. It could make 7(a) financing a more practical first choice for businesses whose funding needs cannot wait.
“I think that’s going to be a good thing for the economy because back to what we were talking about before, you’re going to see more and more small businesses if they can get access to the capital quicker, then that solves their funding needs and they don’t have to take much higher priced financing just because it was more expedient to get it through MCA or perhaps some other non-SBA option,” Hurn said.
How to Pay Off an MCA With an SBA Under The New Rules Effective Oct 1
September 23, 2026The SBA has provided new guidance on its approach toward refinancing merchant cash advances: if you convert one to a term loan, you’ll have to wait a very long time to refinance it with an SBA.
According to the most recent Standard Operating Procedures that go into effect on October 1, “Sales-Based Repayment Agreements (e.g.; Merchant Cash Advances) are only eligible for refinancing if the original agreement has been converted to a term loan, has amortized for at least 24 months, and no additional Agreements have been implemented since the conversion of the prior agreement(s).” If there’s any uncertainty as to what that means, they go a step further and say “If the Sales-Based Repayment Agreement is still active, it is not eligible for refinancing.”
This is slightly different from last year’s SOP that said “merchant cash advances and factoring agreements are not eligible for refinancing.”
The new language was perhaps put in place to close a potential loophole where an MCA is converted to a term loan and then immediately refinanced by an SBA.
The 2026 Coleman SBA Lending Awards Recap
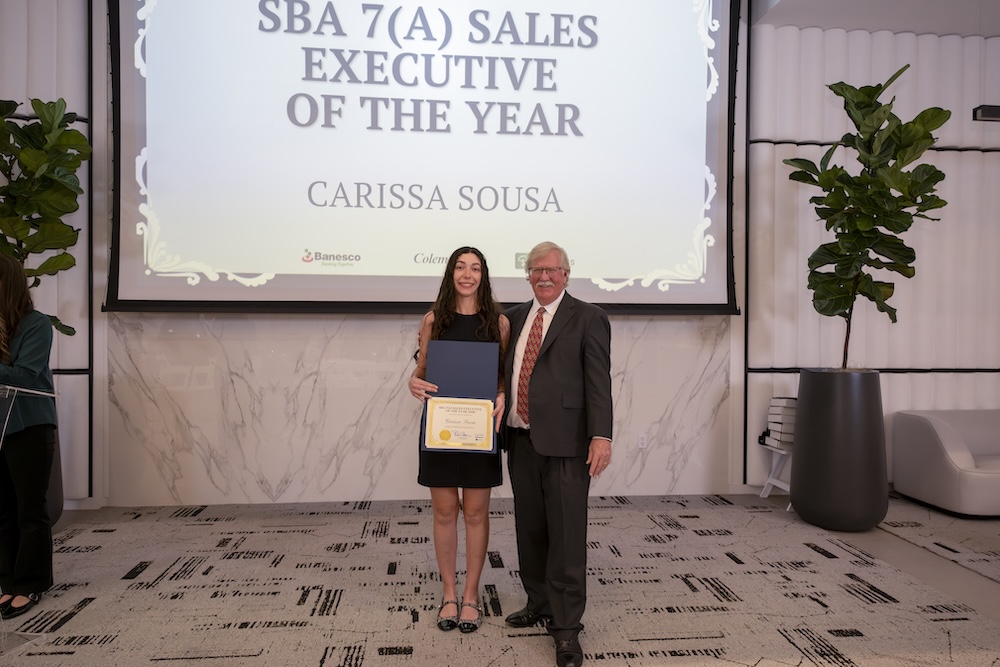
March 24, 2026Coleman’s 2026 SBA Lender Professional Awards ceremony took place last week in Miami at the corporate headquarters of Banesco. Bob Coleman, the organizer of the event and founder of the Coleman Report, was the host. The annual Coleman Awards first debuted in 2025. The full list of winners from 2026 can be viewed here.
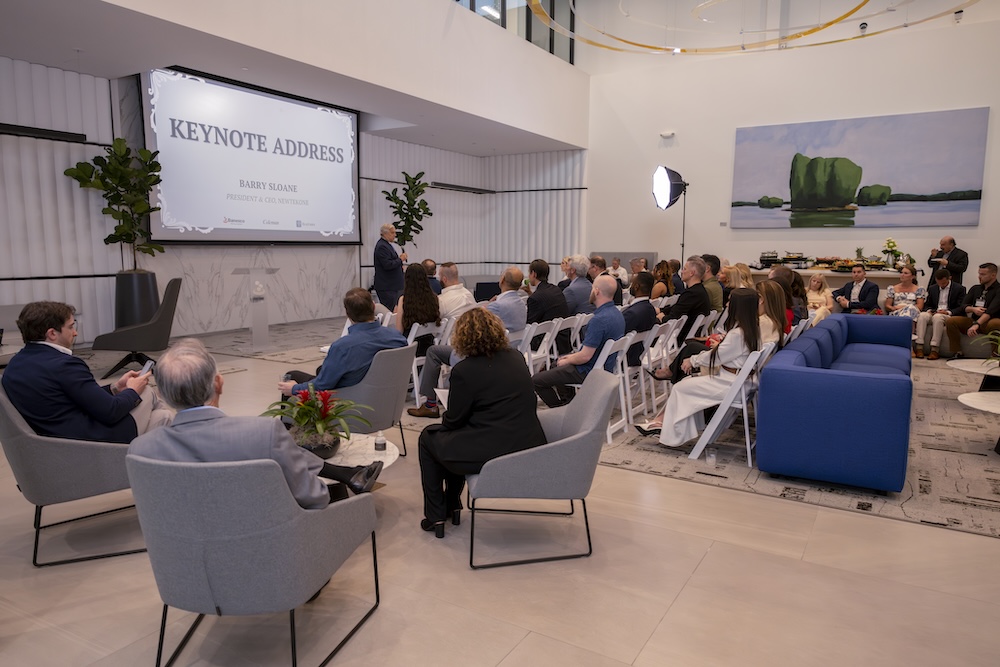
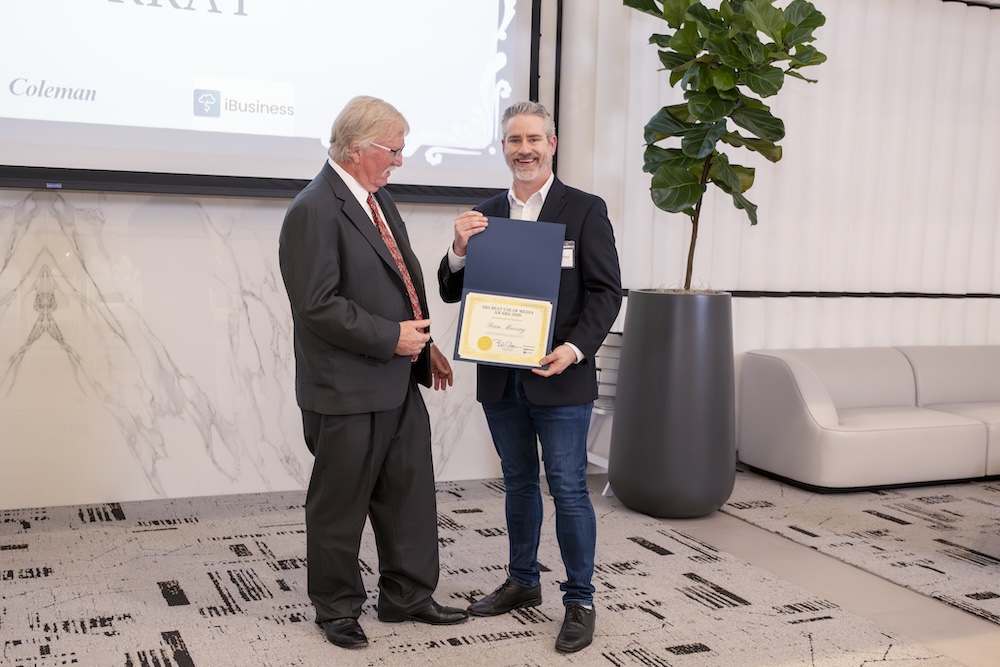
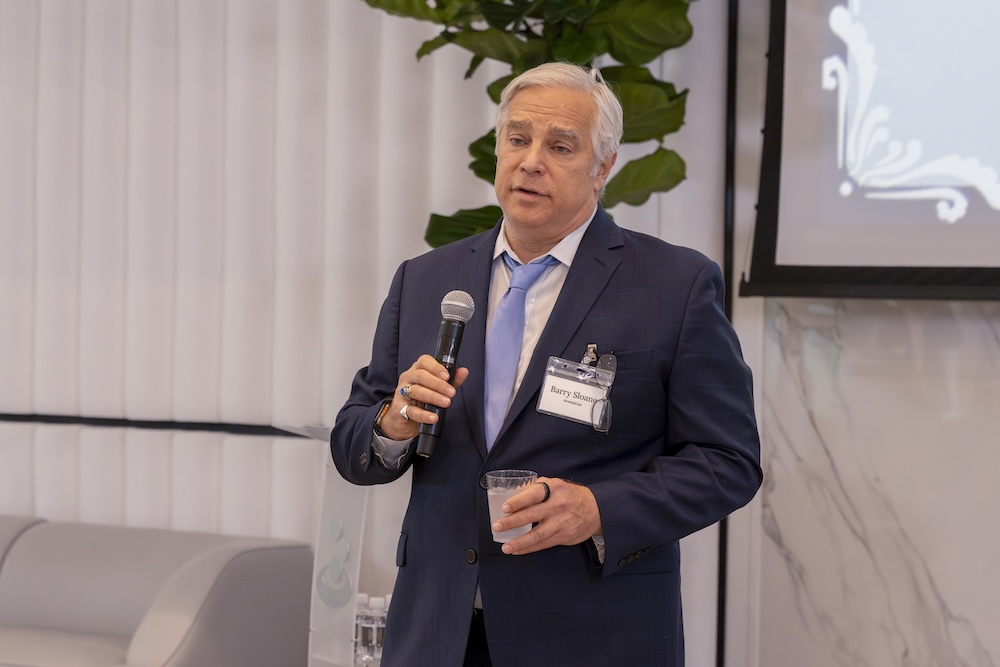
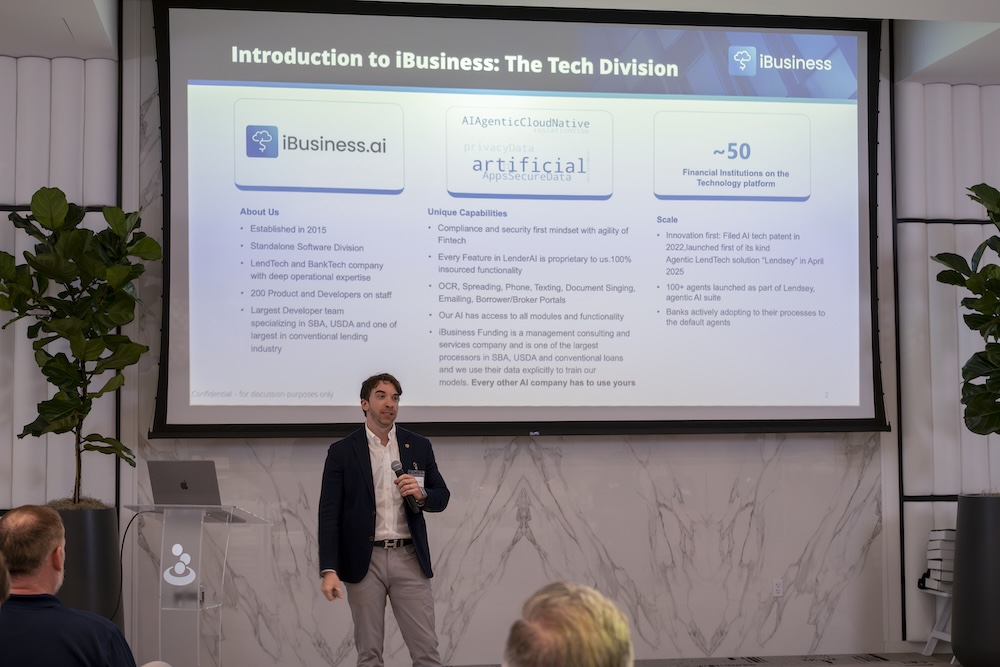
Among the keynote speakers were NewtekOne CEO Barry Sloane and iBusiness CEO Justin Levy. Sean Murray of deBanked won an award for SBA Best Use of Media. The event was well attended.
Coleman Report’s Bob Coleman is Out With a New Book: “Easy Money, Hard Time”
July 18, 2025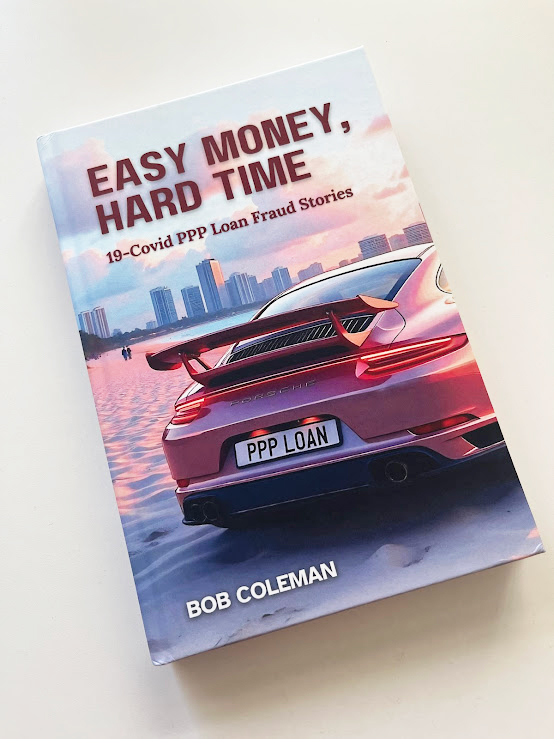 Bob Coleman, founder of Coleman Report, the leading provider of information to small business bankers to help them make less risky small business loans, recently authored a book. Titled Easy Money, Hard Time: 19-Covid PPP Loan Fraud Stories, the book dives into “the most shocking cases of PPP loan fraud, exposing the audacity, greed, and recklessness of those who saw an economic disaster as a chance to cash in.”
Coleman has also previously authored PPP Saves Millions of Main Street Jobs During Covid (2022) and Money, Money Everywhere But Not a Drop for Main Street (2011).
Coleman’s premium content trade newsletter began in 1993 and it provides critical analytical information for today’s small business lending professional. They are the largest producer of training courses and webinars for small business bankers.
Bob Coleman will be moderating a panel on SBA lending at the B2B Finance Expo in Las Vegas this October.