Related Headlines
| 07/03/2024 | Smart Business Funding prevails in suit |
Stories
Smart Business Funding Prevails in Trademark Lawsuit
July 3, 2024Smart Business Funding, the trademark owned by Collins Cash Inc, has officially survived a trademark infringement challenge brought by BillFloat Inc dba SmartBiz. Both companies began using their respective marks a decade ago and the two even had a partnership referral agreement at one point. However, in 2020, SmartBiz sent Smart Business Funding a Cease & Desist letter on the basis that it was allegedly infringing on its mark and causing confusion in the market. While they are both engaged in small business financing, each offers different products. SmartBiz eventually filed a lawsuit.
After the original trial went in favor of Smart Business Funding, the decision was re-examined on appeal. There, the United States Court of Appeals for the Ninth Circuit affirmed the original ruling. The Smart Business Funding mark does not infringe upon SmartBiz.
Need Capital for Your Funding or Lending Company? 3Jane Does it On Blockchain
July 27, 2026“I’m a big believer in agentic capital markets. I think we’re going to see a Cambrian explosion of novel primitives, driven largely by two pieces. Today, it’s just very easy to construct arbitrary financial building blocks using smart contracts,” said Jacob Chudnovsky, Founder of 3Jane, to deBanked.
3Jane provides credit facilities and forward flow arrangements across a range of products, including consumer loans, small business loans, and even merchant cash advances. The company previously provided a $10 million senior warehouse facility to consumer lender LendSwift, for example, and followed that with an inaugural $8.5 million purchase of small business loans from Slope, an embedded credit infrastructure provider that powers business lending programs for major players across the US, including Amazon. According to Chudnovsky, 3Jane would like to do even more deals in the small business lending and MCA space.
But with a twist.
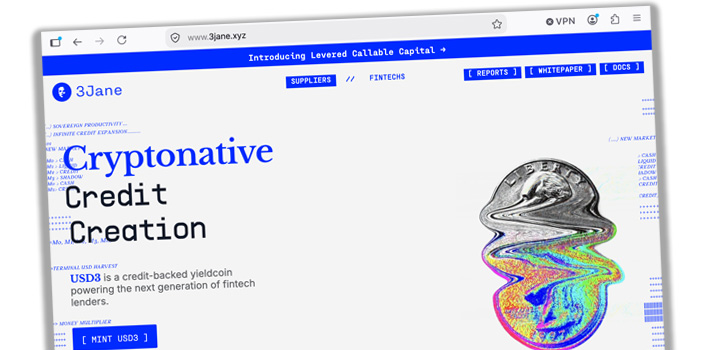 3Jane has built an entire protocol on the blockchain. It offers a credit-backed “yieldcoin” that earns its yield “from warehouse facilities, forward-flow programs, and credit-lines.” Investors can mint the coin on Ethereum, and it earns a yield backed by the performance of 3Jane’s credit assets. Minting is not open to US investors, but the company’s capital markets offerings are focused exclusively on North America. So, if you’re a small business funder seeking a credit facility or forward flow arrangement, 3Jane wants to speak with you.
Chudnovsky is a software engineer by trade and entered the DeFi space in 2020.
“…around 2024, I basically came to the realization that credit is still an extremely underdeveloped vertical in crypto and particularly both the capital aggregation and the capital distribution side of it,” he said. “My initial focus was ‘can we get the best of crypto to distribute capital in a better way?’ and so I founded 3Jane, and we started off by doing unsecured lines of credit for crypto users in the United States who had a bunch of these different assets and could not really borrow against it in a streamlined way.”
 That effort eventually led to 3Jane’s current business model. If the name 3Jane sounds familiar, it’s because Chudnovsky drew it from the 1984 novel Neuromancer, the famous William Gibson book that coined the phrases “cyberspace” and “the matrix.” By pure coincidence, Apple TV is releasing a 10-episode series based on the book in January 2027.
“I just think we’re going to enter this complete renaissance of new different financial primitives and I think it’s going to drive a lot of adoption, new ways of thinking about our financial system and that sort of really resonated with me with the book,” Chudnovsky said.
And that new way of thinking is starting to take root. The capital markets utilizing blockchain to create efficiencies is already cropping up around the industry. Since 3Jane last spoke with deBanked, its purchase of embedded finance products from Slope has increased to a total of $60 million.
3Jane’s customers do not need to be crypto experts. The company handles that side of the transaction while underwriting the risk and executing what is otherwise a conventional capital markets deal, but one in which the infrastructure is robust enough that this can be a lender’s first and last facility. On 3Jane’s part, doing this requires a strong understanding of the various financial products it evaluates, including MCA.
“…there are a number of MCA operators in the United States that are doing things right, they’re growing significantly and they need leverage to scale their business,” Chudnovsky said. “and so warehouse facilities and to a lesser extent forward-flows for MCAs sort of equally make sense for them as long as you are cognizant of the risks.”
American Brokers Help Fuel Canada’s Small Business Finance Boom
July 10, 2026 Canada’s small business finance industry is growing, and behind the scenes, American brokers are helping fuel that momentum.
“They’re kind of killing it here right now, from what we see from the partners that we work with,” said Vlad Sherbatov, President & Co-founder of Smarter Loans, an online lending marketplace in Canada. “…for the American players that have come in, they’re already really good at the broker channel.”
Some Canadian small business funders, particularly those offering an MCA product, told deBanked that a significant amount of deal volume is coming from south of the border. And with that, the environment and culture of the business itself is beginning to shift. In their view, it is becoming more Americanized.
“…a lot of the Americanization of the industry, if you will, is coming from US brokers and funders,” said Avrohom Bernstein, CEO at 2M7 Financial Solutions.
Part of that shift is a new level of competition among firms as brokers try to maximize the options available to their clients. Bernstein, for example, said it often starts with an American broker inquiring about submitting a few Canadian deals. Lately, however, it’s been escalating into situations where eight different brokers might submit the same clients.
“Every deal now you’ve got to hustle, you’ve got to fight, you have to really work it,” Bernstein said.
That competition once meant fighting to become the one and only exclusive partner for a merchant. Now, it has become more common to find that a submitted applicant already has multiple active advances.
“…that used to be unheard of in Canada, like that used to be excessively unusual to see more than three positions, now ten is not insane anymore,” said Bernstein. “It really escalated in a way that we haven’t seen, and that’s probably over the last 12, maybe 24 months, that it started really picking up,” Bernstein said.
Jodi Levy, Head of Sales and Business Development for BizFund in Canada, said she has made a similar observation. When she first started in the industry there, something like a third position was unheard of. Now, she said, they see it much more often.
“I feel like that’s definitely more an American influence,” Levy said.
BizFund has a large American operation as well, so the company is no stranger to how things work on the other side of the border. But like others, its Canadian funding arm also works with the American broker community.
“…partners are great, American, Canadian, we don’t care where you’re from, as long as you’ve got good business,” Levy said, adding that what matters is whether those partners have a direct relationship with their merchants. She also said that working with the broker community requires operating with a sense of urgency, something she has instilled in her team as a culture of NOW.
The diversity of products brokers can offer may not be as wide as what is available in the US. Sherbatov said that once a business steps outside of traditional banking sources, it is essentially entering MCA territory. As a result, much of the new competition entering the space is focused there.
“Among the new players that have come in, MCA is definitely the product that they’ve been leading with,” Sherbatov said.
“We have like five or six banks, and then like a couple credit unions, and then there’s not really anyone between, and there’s A-paper guys, and then B, C, D type of guys,” said Bernstein of 2M7.
According to Statistics Canada, banks provided 68.5% of all capital to SMEs in 2023, while credit unions and government institutions provided 20.6% and 9.4%, respectively. Only 2.2% was funded by “online alternative lenders.” The total market size at the time was estimated at $94 billion.
“I think the big gap is—there’s tons of businesses that want capital,” said Rafael Rositsan, CEO and co-founder of Smarter Loans. “There are some funders that offer it, but they’re pretty tight, and I feel like if somebody can come in and take on a bit more risk and open up their books a bit, then there’s plenty opportunity to fund a lot of Canadian businesses.”
 As for why there has been such a push from Americans into Canada, no one pointed to a single definitive reason, but the runway for growth in the alternative lending segment, as illustrated by the report, may provide a clue as to the interest. Bernstein of 2M7 said there has long been a pattern of Americans entering and exiting the Canadian market, but he had also long believed that sustained success required boots on the ground. Now, he is reconsidering that view, at least on the broker side, as the current wave of broker entrants appears to be holding more firm. For funders, however, he said it still does not really work as a remote business.
“Every funder that’s actually doing decent volume is here, except for one,” Bernstein said.
In 2019, deBanked held a conference in Toronto for what was then a burgeoning small business finance industry, but held off on further events there after Covid disrupted plans for 2020 and 2021. It did not go unnoticed, however, that deBanked’s more recent American-based events have had more email addresses ending in .ca on the attendee lists. At the most recent Broker Fair conference in New York City, for example, some firms were exclusively advertising Canadian funding products to American brokers.
Canada’s population is relatively small, at roughly 41 million residents. That is about the size of California and only 25% larger than Texas. Homegrown Canadian brokerages do exist, of course, and a lot of business in Canada stays within Canada. Not all of the deals are originating through brokers either. Some merchants prefer to work directly with a funding source, while others prefer the comfort of applying through a Canadian lending marketplace like Smarter Loans, for example. If a merchant is ultimately eligible for some kind of funding, Sherbatov said, they are going to know it through their platform.
“We love the fact that we can help the small business economy thrive in the country, it’s responsible for a lot of positive things,” Sherbatov said. And whether the funding sources originate from Canada or the US, he said those companies ultimately find their way to them.
“We’re just becoming a more critical part of that journey for the merchant, and I think that explains why a lot of the new companies, when they come in, they gravitate toward us,” said Sherbatov. “…because in the business financing space we’ve carved out a nice niche for ourselves after Covid, and usually the new players gravitate to us because they know that merchants come to us as well.”
Levy of BizFund said part of the Canadian business experience is kindness. “That stuff goes far, we love that stuff up here in Canada,” she said. On the company website, photos of the company’s team, including Levy, show them smiling and ready to fund businesses.
For stalwarts like 2M7, which launched in Canada in 2008, the market’s evolution has been dramatic. Bernstein said the industry has gone from being a bit quiet and under the radar to seeing a lot of energy recently, whether from American brokers or from Canadian brokers that have decided this is the niche they are going to focus on entirely.
“In the US, I know a lot of brokers who also do equipment and also term loans and also SBA and also all this other type of stuff, it doesn’t exist so much in Canada,” Bernstein said. “It’s like if you’re selling to small businesses and you’re offering them financing, there’s not that many products you could line up, so it’s like if you’re doing brokerage, you got to be all in, like if you’re doing MCA, you got to do MCA.”
“I think that it was evident to a lot of players outside of the market that there is a big market opportunity that’s untapped,” Sherbatov said, “just because so little financing is being released by alternative lenders, that they started to come into the space, and we’ve seen, I mean, not even for the past two years, but I’d say in the past 18 months, our own roster of business lenders on Smarter Loans has doubled, like we went from 10 to where now we have 20, and the majority of that expansion actually happened from US players coming into the country.”
And the growth is just getting started.
“There’s a lot more room for it,” said Rositsan of Smarter Loans.
VOX Funding and Cloudsquare Partner to Accelerate API-Driven Capital Automation
January 29, 2026New York, NY – VOX Funding, a leading fintech provider of fast and flexible capital solutions for small and mid-sized businesses, has partnered with Cloudsquare, the premier Salesforce-native alternative business lending CRM for brokers. Together, the companies are introducing a next-generation, API-powered funding workflow designed to eliminate manual handoffs and accelerate deal flow across the entire broker ecosystem.
This integration enables real-time submissions, faster approvals, and cleaner funding processes – reducing reliance on email communication and eliminating delays caused by traditional back-and-forth exchanges.
A Seamless, Fully Connected Lending Experience
Through this partnership, VOX Funding has expanded the reach of its SYNQ API by integrating directly with Cloudsquare’s Salesforce-powered platform. ISOs using Cloudsquare can now submit deals to VOX instantly, enabling a smoother and more transparent process from initial application through final approval.
Brokers and merchants gain true end-to-end visibility into the funding journey, including offers, documents, stipulations, and real-time status updates, all within the systems they already use.
“Too many brokers who submit to VOX are limited by CRMs that cannot support API submissions, and building their own integration is not realistic for most teams,” said Jeffrey Morgenstein, Co-Founder and CEO of Cloudsquare. “This partnership creates a seamless upgrade path so brokers can transition to Cloudsquare and work with VOX more efficiently, with improved speed and total transparency.”
Positioning VOX for Scalable Growth
For VOX Funding, this integration represents a major leap forward in scalability and partner enablement. By reducing manual touchpoints and automating key workflow steps, VOX can serve its broker network with greater speed, accuracy, and operational efficiency.
“Our mission is to make capital access fast, flexible, and tailored to the unique needs of every business,” said Louis Calderone, Co-Founder and President of VOX Funding. “Cloudsquare’s API-driven platform brings speed and transparency, allowing us – and our partners – to work smarter and deliver better outcomes for the clients who rely on us.”
About VOX Funding
VOX Funding delivers fast, flexible, and creative capital solutions for small- and medium-sized businesses. By tailoring funding to each business’s needs — often within 24 hours – VOX helps merchants seize opportunities, expand operations, and achieve sustainable growth without delay.
www.voxfunding.com
About Cloudsquare
Cloudsquare is the leading end-to-end lending platform, uniquely powered by Salesforce, to deliver unparalleled flexibility and innovation for lenders and brokers. With a commitment to optimizing lending processes through cutting-edge technology, Cloudsquare provides robust, scalable solutions that empower clients to achieve greater efficiency and growth. Celebrated by industry leaders, Cloudsquare has earned a place on the Inc. 5000 list as one of America’s fastest-growing companies and is consistently rated a top service provider on platforms like Salesforce AppExchange, G2, Clutch, and Manifest.
Dragin Technologies Launches the First True AI Pre-Underwriting Tool for Revenue-Based Financing, Redefining the Future of Digital Business Intelligence
May 16, 2025New York, NY — May 16, 2025 — Dragin, the automation engine behind some of the fastest-growing and largest revenue-based financing companies, announces the launch of its latest breakthrough: True AI Web-Based Pre-Underwriting. This powerful new AI tool delivers real-time digital presence analysis to deal teams just before offers are made.
Designed for Revenue-Based Financing
In an industry where speed, accuracy, trust, and decision confidence drive every dollar moved, Dragin’s new AI functionality equips funders with a clear picture of a merchant’s online credibility and activity, automatically pulled before a human ever touches the file.
Here’s what it uncovers:
- Ownership and business addresses
- Business website, social media pages, storefront images, and location markers
- Incorporation information, SOS details, and NAICS codes
- Legal exposure including lawsuits, arbitration, and personal risk
- News coverage and media presence
- Financial signals and business health
- Registrations and licenses
- Customer reviews (Google, Yelp, Trustpilot, etc.)
- Top social media posts and engagement
How It Works
The moment a deal hits your inbox, Dragin’s proprietary automation stack kicks in, extracting deal info, organizing docs, applying pre-decline logic, and now, launching the AI agent. In under 30 seconds, it builds a hyperlinked, easy-to-read Digital Presence Report and attaches it directly to the CRM deal view. No clicks, no searches, no lag.
Why It Matters to Funders
For revenue-based financing companies, every delay risks a lost deal. Every gap in diligence risks a burned book. Dragin AI closes those loops.
✔️ Cost savings
✔️ Faster pre-qual checks
✔️ Early fraud detection
✔️ Deal confidence pre and post contracts
✔️ Fewer merchant falloffs post contracts
✔️ Streamlined ISO and internal decisioning
From Dragin’s Founder
“In the revenue-based financing space, you need to move fast without missing the red flags,” said Mark Ross, CEO of Dragin. “This tool gives funders real time signals, whether the merchant is real, active, and viable, before you send an offer. No more hours of review.”
Part of a Larger Ecosystem
Dragin AI is just one tool in Dragin’s full-stack deal automation platform, which includes:
- Email parsing and file classification
- Bank PDF and application extraction
- Pre-qualification, auto-approve, and pre-decline logic
- Instant CRM syncing
- Auto-contract generation
- Merchant offer portal for real-time negotiation
and much more
About Dragin Technologies
Developed specifically for the revenue-based financing, alternative lending, banking, and insurance spaces, Dragin’s suite of underwriting tools automate deal intake, streamline underwriting, and gives funders a smarter way to scale. With its Machine Learning and AI-driven tech stack and its powerful CRM suite, DraginForce, Dragin is powering the next wave of fast, AI-powered, and compliant funding operations. Learn More About Dragin at https://www.dragin.io
Congressman Dan Meuser Visits CFG Merchant Solutions™ to Discuss Small Business Finance and Regulatory Trends
April 24, 2025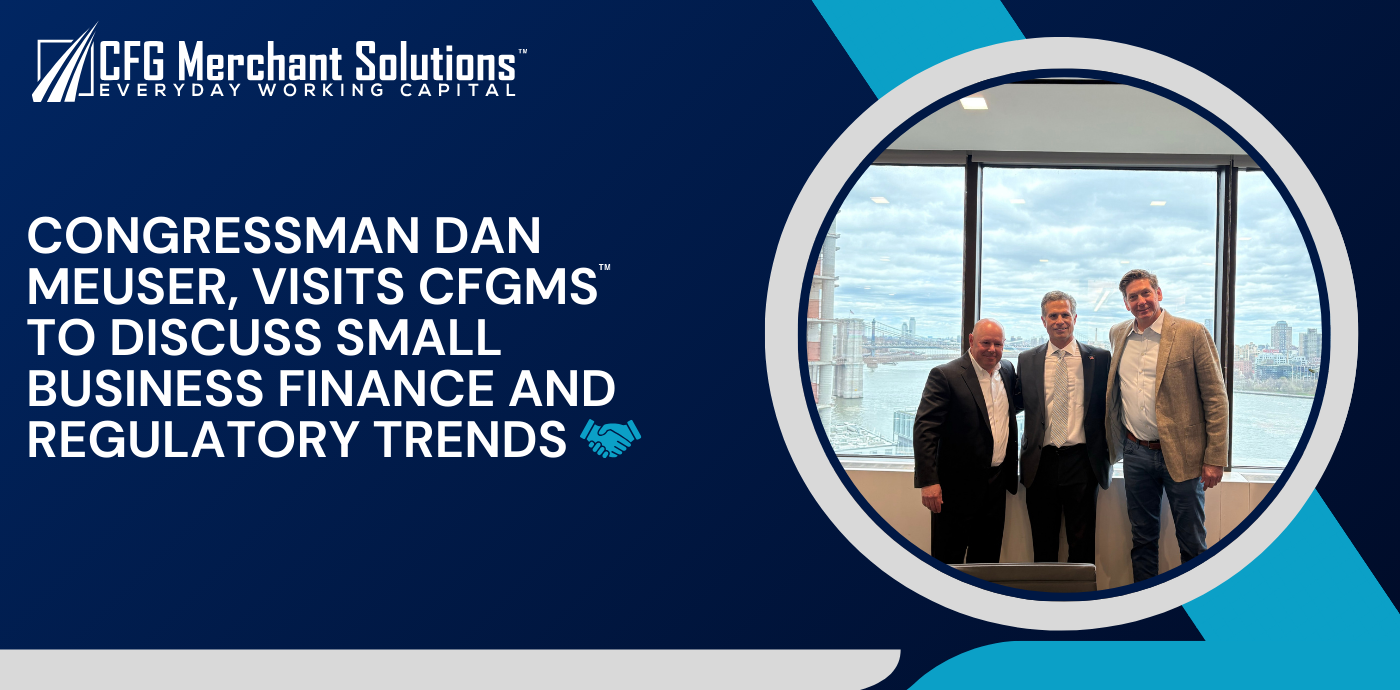
CFG Merchant Solutions™ (CFGMS™), a leading provider of revenue-based financing, was honored to welcome Congressman Dan Meuser (R-PA, 9th Congressional District) to its New York office for a discussion on the evolving landscape of small business finance and the importance of regulatory transparency.
During his visit, Congressman Meuser engaged with CFGMS leadership and staff to exchange insights on the current regulatory climate impacting small business funders. As a prominent member of the House Financial Services Committee—where he serves as Chair of the Subcommittee on Oversight and Investigations—and the House Small Business Committee, Rep. Meuser’s visit underscored his ongoing efforts to ensure small businesses have access to responsible, innovative funding solutions.
“CFGMS is committed to setting the highest standards of compliance, disclosure and transparency in our industry,” said Bill Gallagher, President at CFG Merchant Solutions. “We’re proud to work alongside policymakers like Congressman Meuser who understand the critical role small businesses play in our economy and who are advocating for smart, balanced regulation.”
Rep. Meuser has represented Pennsylvania’s 9th Congressional District since 2019. Prior to his election to Congress, he served as Pennsylvania’s Secretary of Revenue, where he was credited with making the department more efficient and customer focused. Earlier in his career, he was an executive at Pride Mobility Products, helping the company grow from $2 million to over $400 million in annual sales.
CFGMS continues to lead the industry in championing ethical, growth-driven funding practices for small businesses across the country. The company remains steadfast in its mission to expand access to capital while fostering transparency and accountability.
About CFG Merchant Solutions™
CFG Merchant Solutions™ (“CFGMS™”) is an independent, technology-enabled alternative funding platform focused on providing capital access to small and mid-sized businesses that have historically been underserved by traditional financial institutions and may have experienced challenges obtaining timely financing. CFGMS™ uses its historical transactional data, proprietary underwriting, predictive analytics, and electronic payment technologies and platforms to assess risk, and provide access to flexible and timely capital.
Media Contact:
Nick DeFeis
Head of Marketing
CFG Merchant Solutions™
(844) 662 – 3467
ndefeis@cfgms.com
cfgmerchantsolutions.com
Why You Specifically Need An MCA Accountant for Your MCA Business
September 11, 2024David Roitblat is the founder and CEO of Better Accounting Solutions, an accounting firm based in New York City, and a leading authority in specialized accounting for merchant cash advance companies.To connect with David or schedule a call about working with Better Accounting Solutions, email david@betteraccountingsolutions.com.
 Doing the books for a merchant cash advance (MCA) business isn’t like doing the books for other types of businesses. That’s something that seems pretty intuitive for those of us in the industry to understand, but often I see many business owners still trying to handle finances themselves or hand it off to a general accountant who isn’t well-versed in the MCA world, which leads to unfortunate messes that require some costly cleanup work. The reality is that while any accountant can keep basic, or even complex financial records, managing the finances of an MCA business requires more than just a surface-level understanding.
Take a situation I encountered recently: a business owner decided to use their regular accountant to handle their books, deciding that the cost of an MCA industry-qualified accountant was too much for him at that point in time. The accountant he picked was a competent elderly gentleman who produced the financials regularly and on time, and things appeared to be going smoothly until his investors realized their syndication income had been reported incorrectly. The accountant, unfamiliar with MCA-specific accounting, treated the income like a standard loan repayment and the business owner hadn’t noticed the misreporting when he passed the report on to his financiers. The investors were confused and frustrated with the mistaken report, and felt like they weren’t getting a clear picture of the company’s financial health and cash flow situation. I was actually able to help him clear up the issue, but the whole mess and subsequent (thankfully temporary) mistrust could have been avoided entirely if the accountant was someone who understood the specifics of the MCA business.
Handling the finances of an MCA business isn’t just about tracking the cash coming in and out. There are particular rules around recognizing income, such as how to deal with syndication fees, manage different types of funding, and correctly categorize income like commissions and fees. It’s also critical to understand how to report income for tax purposes versus what’s required for investor reporting. For example, recognizing income too soon or too late can have a big impact on your cash flow, tax obligations, and even how your business is perceived by others.
I’ve seen businesses try to use standard accounting methods and find themselves with financial statements that don’t accurately reflect their operations. In one case, a company overstated its income because it applied a generic accounting approach. This not only increased their tax burden but also strained their cash flow. They needed someone who understood the nuances of the MCA world to correct these issues, adjust the income recognition methods, and align them with industry standards.
Another challenge everyday CPAs struggle with is keeping up with the constant changes in MCA deals – from advances in different repayment stages to syndication agreements with external investors. Without careful tracking, discrepancies can quickly arise, and they’re often not noticed until they’ve become significant problems. Even for businesses using cash basis reporting because their revenue is under $10 million annually, it’s crucial to handle things correctly. Deferring tax liabilities by timing income recognition can be a smart move, but only if done accurately. Otherwise, there’s a risk of audits or having to pay back taxes with penalties. I’ve helped businesses navigate these tricky waters after they ran into trouble because their previous accountant didn’t know when to use cash basis versus accrual basis reporting.
A good MCA accountant knows how to navigate the specifics of your business. They understand what to watch out for, how to manage the unique aspects of the industry, and how to avoid problems that could end up costing you time, money, or reputation. I’ve seen too many businesses suffer preventable setbacks by either doing it themselves or relying on someone who didn’t have the right knowledge. The cost of hiring an accountant who specializes in MCA is minimal compared to the potential financial losses from mishandled books or compliance errors.
At the end of the day, having an accountant who understands the MCA industry isn’t just a nice-to-have; it’s a necessity. The complexities of this business require a specific set of skills, and working with someone who gets that can help you keep your business running smoothly and avoid unnecessary headaches in the future. Make sure you have the right support in place to protect your business and keep things on the right track.
Business Finance Companies on Inc 5000 List in 2024
August 13, 2024Here’s where small business finance companies rank on the Inc 5000 list for 2024:
| Company Name | Ranking | Growth |
| Clara Capital | 158 | 2,295% |
| 4 Pillar Funding | 251 | 1,620% |
| Fundible | 254 | 1,611% |
| Byzfunder | 303 | 1,404% |
| Valiant Business Lending | 337 | 1,286% |
| CapFront | 541 | 792% |
| SellersFi | 974 | 523% |
| SBG Funding | 1,158 | 443% |
| Splash Advance | 1,238 | 418% |
| Channel | 1,330 | 389% |
| iAdvance Now | 1,421 | 362% |
| Flexibility Capital | 1,513 | 342% |
| eCapital | 1,968 | 265% |
| Kapitus | 2,025 | 258% |
| Merchant Industry | 2,057 | 254% |
| ApplePie Capital | 2,265 | 230% |
| Backd | 2,282 | 228% |
| Capital Source Group | 2,306 | 226% |
| Direct Funding Now | 2,323 | 225% |
| Expansion Capital Group | 2,829 | 179% |
| Fora Financial | 3,560 | 134% |
| Percent | 4,047 | 111% |
| Smarter Equipment Finance | 4,566 | 89% |
| Gateway Commercial Finance | 4,598 | 88% |
Did we forget you?! Let us know at info@debanked.com and we’ll add you.
Earn A Higher Commission On Your Deals With Us!... hello, smart business funding here. we're a direct funding company based in brooklyn, ny specializing in mcas and we're currently interested in buildi... |
Direct funder seeking new partners to work with!... hello, smart business funding here. we're a direct funder based in brooklyn, ny and we're currently interested in building relationships with new iso ... |
Direct funder seeking new partners to work with!... smart business funding here. we're a direct funder based in brooklyn, ny and we're currently interested in building relationships with new iso partners. we have a... |
See Post... smart business funding, direct number: (866) 737-6278, email: anthony@smartbusinessfunder.com, website: https://www.smartbusinessfunder.com/... |
Smart Business Funding- Inc 5000 List of Fastest Growing Companies in the USA... smart business funding, the leading financial services company in brooklyn new york is happy to announce that it is number 1229 on the annual inc. 5000 lis... |