Legal Briefs
TomoCredit Sues Fintech Journalist
March 10, 2026TomoCredit, a company that identifies itself as “a software company providing a suite of software solutions designed to support financial literacy,” has filed a lawsuit against a fintech journalist named Jason Mikula for defamation and libel. Mikula operates Business Fintech Weekly, a widely read newsletter in the fintech space. TomoCredit alleges it has suffered damages as a result of statements that Mikula published online about the company.
Mikula shared news of the lawsuit online.
TomoCredit is also facing a lawsuit of its own. Two months ago, a class action lawsuit alleged the company had engaged in negligent misrepresentation and other claims related to its business.
Prosecutors: Industry’s Mystery Fraudster Spent Money on Lavish Lifestyle
February 27, 2026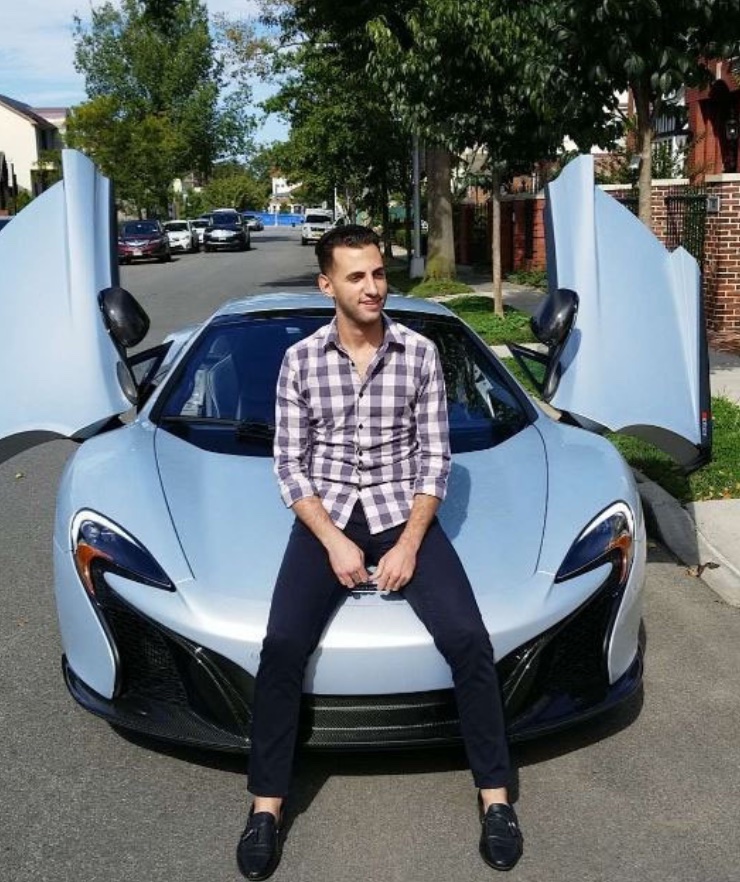 The suspect in the small business finance industry’s long running mysterious fraud was living large before being arrested in Spain and extradited to the United States. Saul Shalev has been charged with wire fraud, money laundering, and aggravated identity theft for stealing the identities of merchants, setting up fake loan brokerages, and tricking business owners and funders into funding his personal bank accounts. When the American authorities finally caught up with him, he had been residing in Dubai but vacationing at the Hotel Nobu Barcelona inside a country with an extradition treaty with the United States. That’s where they got him and his laptop with all the evidence.
According to the US Attorney, Shalev rented a Dubai apartment for $18,000/month, was photographed with a $250,000 McLaren 650S, rented yachts, and paid for chauffeured limousines in Paris. Shalev is currently 36 years old. He had been a fugitive from justice even before these charges. He fled the US in 2019 with three pending warrants against him in New Jersey and New York. His fraud scheme against the industry was carried out from abroad.
His alleged fake ISOs include the names Silver Oak Capital Funding, LEM Enterprises, and SpBiz. Authorities obtained a spreadsheet of 27 funders he had compiled on his computer that noted which ones he had already signed up with or “used and abused.”
Shalev is said to have determined which merchants had small business loans and the approximate date in which the loans were obtained through basic public UCC filing data. That was enough to contact those merchants and pretend to be their lender of record and initiate the first step of each scam.
In total, prosecutors believe Shalev fraudulently obtained over $4 million from merchants and funders.
Shalev has made a request to be moved from jail to home detention. Prosecutors have argued, however, that he is a classic case of an imminent flight risk because his dramatic overseas capture was a result of him having fled the law already
“If Shalev is released and flees the country again, it is very unlikely that the many small business owners and employees who suffered as a result of his criminal conduct will ever see justice,” they wrote.
Richmond Capital Leaves MCA Space With Negative Case Law On the Way Out
February 24, 2026“Substantive unconscionability is clear from the MCAs’ exorbitant and criminally usurious interest rates, among other things.”
– Appellate Division, First Judicial Department, Supreme Court of New York, February 19, 2026
Richmond Capital Group was never part of the mainstream merchant cash advance industry. The company made headlines for years for its alleged connection to Jonathan Braun, who is now back in prison. After landing in the crosshairs of the FTC, a federal court permanently banned the company and its owner from working in the MCA or debt collection industries ever again in June 2022. The New York State Attorney General piled on with its own legal action and secured a $77 million judgment against Richmond and affiliated entities in February 2024.
But the New York judgment was appealed and earlier this month the Appellate Division of the First Department issued its decision, ruling heavily in favor of the Attorney General. Some of its conclusions, while Richmond-circumstance specific, ought to be examined with a wider lens. Snippets of the Court’s rulings are as follows:
On Reconciliations
“Although the MCAs have mandatory reconciliation provisions, no reconciliation was performed in practice, even though it was supposed to be performed on a monthly basis, and daily payments were fixed and did not represent a good faith estimate of receivables; there is no persuasive evidence of any ad hoc incidents of reconciliation (upon a merchants’ request), which were subject to respondents’ “sole discretion,” and there is evidence that such requests were denied; bankruptcy was an express event of default in some of the MCAs, but even where it was not, repeated nonpayment was, as was breach of the MCAs, which was the case where a merchant “interrupt[ed], suspend[ed], dissolve[d] or terminate[d]” its business; and in the event of any of these circumstances, the full uncollected amount became due and respondents were empowered to enforce the personal guarantees they required the merchants to provide.
Usurious intent is also clear as a matter of law, as, absent reconciliation, the usurious interest rates can readily be calculated based on the information provided on the face of the MCAs.”
On Unconscionability
“The MCAs were also procedurally and substantively unconscionable. Substantive unconscionability is clear from the MCAs’ exorbitant and criminally usurious interest rates, among other things. As to procedural unconscionability, it is not dispositive that many, although not all, of the merchants were sophisticated businesspeople and all had prior experience with MCAs, and respondents misrepresented the terms and nature of the MCAs and used other high-pressure tactics.”
deBanked is not a law firm. To understand the implications of this legal decision, consult with attorneys experienced with the subject matter. For example: Hudson Cook, LLP, Murray Legal PLLC, or others listed here.
National Alliance of Commercial Loan Brokers LLC Back in Roglieri’s Hands
February 5, 2026The United States Bankruptcy Court ordered the Roglieri Estate return its interest in the National Alliance of Commercial Loan Brokers LLC back to Roglieri himself. The order was dated January 30, 2026. That interest includes all the assets and liabilities attached to the National Alliance of Commercial Loan Brokers LLC. The Trustee’s reasoning was that management over the business had become burdensome to the Roglieri Estate.
Nearly two years ago, Roglieri declared in a bankruptcy filing that National Alliance of Commercial Loan Brokers LLC (often referred to as NACLB) was valued at $1 million.
Roglieri is currently imprisoned at the Rensselaer County Correctional Facility. He pleaded guilty to wire fraud conspiracy this past November. His sentencing hearing is scheduled for March 11 and he is facing up to 20 years in prison.
Industry’s Mystery Fraudster Extradited to the United States
January 30, 2026A primary suspect in the small business finance industry’s long running mysterious fraud has been extradited to the United States. Saul Shalev, indicted this past August under seal (and unsealed in October) had eluded authorities for years but was finally arrested in Spain. On January 23, 2026, he was extradited to the United States and appeared before a US Magistrate Judge.
Shalev faces a nine-count indictment.
Between approximately December 2019 and November 2022, Shalev defrauded more than 20 small and medium-sized businesses (“SMBs”). As part of the scheme, Shalev obtained information about commercial loans received by the SMBs and offered the SMBs the opportunity to refinance the loans or to obtain additional financing, either from the original lender or from a new lender. Shalev, using stolen identities and making fraudulent representations, acted as a broker between SMBs and potential lenders. After obtaining new or additional financing for an SMB from a commercial lender, Shalev provided fraudulent payoff instructions to the SMB with respect to a prior loan, causing the SMB to send all or part of the loan proceeds to an account he controlled. Shalev also fraudulently received a commission from the lender.
Factor Gives Update on “Killing MCAs” in Texas
January 9, 2026Cole Harmonson, CEO of Dare Capital and a board member for the American Factoring Association, posted an update last month on the recent Texas MCA legislation and campaign to “fight the MCA cronies.” It appeared on the Commercial Factor’s magazine website. You can read it here.
Harmonson shared his strategy on how to kill MCAs in Texas, which focuses mainly on the DACA component of securing a first position: “If you get the Springing DACA, then the bank will not give anyone else (i.e., an MCA) a DACA, and therefore no MCA can legally sweep your customer’s account, thereby killing the MCAs in Texas,” he wrote.
Harmonson had previously shared that the factoring industry had been responsible for the MCA legislation in Texas and that it served as a “blueprint,” suggesting that a similar legal framework could be attempted in other states.
Indictment in the Small Business Finance Industry’s “Long Running Mysterious Fraud”
December 22, 2025 There has been a major break in the case of the industry’s Long Running Mysterious Fraud, an indictment. Less than a year after deBanked ran a story about a sophisticated scheme employed to steal millions from merchants, funders, and lenders through a network of stolen identities and cryptocurrency exchanges, a criminal complaint was quietly filed under seal on February 24, 2025 against an individual named Saul Shalev with addresses in Brooklyn and Israel. He is currently thirty-six years old. On August 20, 2025 that complaint progressed to a sealed indictment and on October 3, 2025 all the filings were finally made public.
Shalev may still be at large. He has dual American/Israeli passports. The original criminal complaint states that he traveled to Israel in February 2019 and had not returned to the United States since. IP addresses, email accounts, and other internet data were used by law enforcement in its investigation. The criminal complaint says that the scheme was still going on earlier this year and that more than 25 victims of the scheme have already been identified.
Shalev, who is innocent until proven guilty, is charged with Wire Fraud, Money Laundering, Aggravated Identity Theft, and Aiding and Abetting.
Brokers and Funders – Are You Ready for Changes to California Law Effective January 1, 2026?
December 20, 2025Bob Gage is a partner in Hudson Cook, LLP’s Michigan office. Kate Fisher is a partner in Hudson Cook, LLP’s Maryland office. https://www.hudsoncook.com/
California has a new law, California S.B. 362, impacting how brokers and funders communicate with merchants starting on January 1, 2026. The new law adds provisions to California’s Commercial Financing Disclosures Law (“CFDL”) which became effective in 2023 and established the first law requiring commercial financers and brokers (described in the CFDL as “providers”) to provide cost-of-funding disclosures to applicants. Here is an overview of what you need to know:
Don’t Say “Factor Rate”
Under S.B. 362, commercial financing providers are not allowed to use the term “rate” in a manner that is likely to deceive a recipient. A “recipient” is generally a person who receives an offer of commercial financing of $500,000 or less. The preamble to the new law (which is not part of the law but informs how the regulator will approach enforcement) gives the following example of what California means by likely to deceive:
- Describing the price of credit as “X% fee rate” or “Y% factor rate,” particularly when those “rates” diverge materially from the APR.
A factor rate will almost always be much lower than any APR. This means that California has effectively banned use of the term “factor rate” when communicating with applicants for loans, sales-based financing, merchant cash advance and yes – even factoring transactions. It is probably safe to talk in terms of “factor rates” internally. But, starting on January 1, 2026 – saying “factor rate” to a California recipient can get you into hot water.
Don’t Say “Interest Rate” Unless Referring to an Annual Simple Interest Rate
S.B. 362 also prohibits commercial financing providers from using the term “interest” in a manner that is likely to deceive a recipient. The preamble to the new law gives the following examples of what California means by likely to deceive:
- Describing the price of credit as “simple interest” when referring to a nonannual rate as opposed to a noncompounding annual rate that a reasonable person would understand “simple interest” to mean; and
- Describing the price of credit as an “interest rate” when describing a daily, weekly, or monthly rate and not an annual rate; and
This potentially impacts providers who describe the cost of commercial credit using a daily or weekly rate and describing that rate as “interest”. For example, loan agreements that use a daily, weekly, or monthly “interest rate” may need to be modified.
California Requires Brokers and Funders to Remind Recipients of the Disclosed “APR” or “Estimated APR”
S.B. 362 complicates post-offer negotiations between providers and recipients by requiring redisclosure of the APR or Estimated APR calculation already required by the CFDL. It does this by adding the following new provision to the CFDL:
- After extending a specific offer to a potential recipient, whenever a provider states a charge, pricing metric, or financing amount to the potential recipient for that specific offer during an application process for commercial financing, the provider shall also state the annual percentage rate of that commercial financing offer by using the term “annual percentage rate” or the acronym “APR.”
What this means for providers:
- The APR reminder requirement applies “during an application process.” The term “application process” is not defined, but it probably does not end until the recipient receives funding or the provider definitively declines to proceed with the financing.
- During the “application process,” anytime a provider communicates with the recipient and states a charge, pricing metric, or financing amount, the provider must remind the merchant of the APR or Estimated APR for that offer. Here are examples of how this might impact brokers and funders:
|
New York Already has a Similar Law
New York already has similar requirements in its Commercial Financing Disclosure Law. See 23 N.Y. Admin. Code Section 600.1(f)(1). Accordingly, brokers and funders should implement these practices in New York as well.
This is only a high-level overview and not legal advice. If you have questions regarding how these laws impact your business, please contact knowledgeable counsel.
Bob Gage is a partner in Hudson Cook, LLP’s Michigan office. Kate Fisher is a partner in Hudson Cook, LLP’s Maryland office. https://www.hudsoncook.com/