events
Regulatory Paranoia and the Industry Civil War
April 11, 2014Stacking is on everyone’s minds in the merchant cash advance (MCA) industry but that war is little more than smoke compared to the fire burning in our own backyard. One of the major topics of debate at Transact 14 has been Operation Choke Point, a federal campaign against banks and payment processors to kill off the payday lending industry and protect consumer bank accounts. Caught in the mix are law abiding financial institutions, some of which if affected, could potentially disrupt the merchant cash advance and alternative lending industries. Both have become heavily dependent on ACH processing. Could their strength become their Achilles heel?
Indeed, there was a rumor circulating around the conference that a popular ACH processor in the MCA industry is no longer accepting new funding companies. I know the name but was not able to confirm it as fact. There is a two-fold threat on the horizon:
1. The probability that ACH processors in this industry are also processing payments for payday lenders or other high risk businesses.
2. The likelihood that a bank or ACH processor would take preemptive action and terminate relationships with merchant cash advance companies and alternative business lenders, not because it’s illegal but as a way to make their books squeaky clean.
The sentiment at the conference however was that MCA providers and alternative business lenders had little need to worry. While Operation Choke Point specifies online lenders, they are narrowly defined as businesses making loans to consumers. MCA and their counterparts do not fall under that scope, even if they themselves lend exclusively online.
Is regulation coming?
There seems to be both a call for and paranoia about regulation, especially in the context of stacking merchant cash advances and daily repayment business loans. On the popular online forum DailyFunder, several opponents of stacking are under the impression that regulators will be busting down doors any day now to put an end to businesses utilizing multiple sources of expensive capital simultaneously. Many insiders who have had their merchants stacked on view the issue as both a legal and a moral one. Opponents get worked up about it for many reasons. They believe any one or multiple of the following:
- The merchant can’t sell something which has already been contractually sold to another party.
- That the merchant ends up borrowing and selling their future revenues at their own peril, endangering their cash flow and their business.
- That the stackers endanger the first lender or funder’s ability to collect.
- That the merchant taking on stacks won’t be eligible for additional funds with the first company, hurting the retention rate.
Stacking is not illegal, but it may be tortious interference. That allegation is the one that gets thrown around the most, but it’s important to recognize that actual damages are an integral part of any such case. If I stack on your merchant and the deal performs as expected for you, then what damages would you have suffered? But if I stack on your deal and it defaults 3 weeks later, you might be able to allege that I was the cause of it.
Insiders on DailyFunder’s forum that wonder how they might be able to get stacking to stop, only need to follow the example of what a few select funders are already doing, going on the offensive. The first thing one west coast MCA company does when they have a merchant default is find out if there was a stack that came on top of them. If they find out who it was, they send the offending funder a bill for the outstanding balance. That may sound cheesy, but given their industry prowess and litigious nature, they said that some stackers quietly mail them a check, rather than risk things escalating to the next level. The threats only hold weight of course if you’re actually prepared to bring the case to court.
I’ve spoken with dozens of proponents for stacking, many of sound character, high intelligence, and business acumen. They buck the stereotype of stackers as sleazy wall street guys with pinky rings. Few of these proponents believe that future revenue is a precise asset. It’s been said that, “future revenues are unknowable and possibly infinite. A business should be able to sell infinite amounts of these future revenues if there are investors out there that will buy them.” The general consensus on this side of the aisle is that a 2nd position stack, or “seconds” are here to stay. There’s a sense of calm and conviction, as if seconds were a boring subject of little contention. Many are okay with thirds “if the math works” but discomfort sets in on fourths, fifths and beyond. If they believe it’ll be a good investment, they’ll do the deal. They scoff at the notion that they’d willingly chance putting a merchant out of business since that would jeopardize their own investment.
To date, I’ve seen no data to support that stacking causes merchants to go out of business. I would not be surprised if there was a correlation between defaults and stacks, but that would not imply causation. A business that is on its way towards bankruptcy regardless may be able to obtain a few stacks in the process as a last ditch effort to stave it off. When the business finally fails, it may appear to look like the stacks caused it, even if they didn’t.
For those that don’t want to play cat and mouse with threats and lawsuits, there’s a growing call for regulation, both self-regulation and federal. That call feeds off the paranoia that regulators are knocking at the industry’s door already anyway.
NAMAA
In regards to self-regulation, insiders have been looking to the North American Merchant Advance Association (NAMAA) to create rules and become an enforcer. It’s no secret that their members are opponents of stacking, but as a powerful body of industry leaders, they’re up against a threat of their own, antitrust laws. Creating rules and enforcing them could be construed as anti-competitive. In truth, a lot of the MCA industry’s growth over the last 2 years can be attributed to stacking. A private association of the largest players actively working to establish rules to squash the fast growing segment of new entrants could indeed be perceived as anti-competitive.
But that doesn’t mean NAMAA is powerless to promote their views. Following in the footsteps of the Electronic Transactions Association, they could create a set of best practices, host workshops, and offer courses and sessions to train newcomers on these best practices. Such benefits and opportunities are a standard in the payments industry, but nothing like it is available in MCA or alternative business lending.
But is it too late for self regulation?
With all the government enforcement occurring in the rest of the financial sphere, fears of imminent federal involvement in MCA and alternative business lending are not unfounded… or are they?
In the wake of the financial crisis, the Consumer Financial Protection Bureau (CFPB) was formed to protect consumers in financial markets. The CFPB was instrumental in Operation Choke Point and they would be the most likely federal agency to field complaints about stacking. Unlike the Office of the Comptroller of the Currency which has jurisdiction over banks, the CFPB’s oversight extends to non-bank financial institutions. They’re the wild card agency that has financial companies across the nation on their heels.
I had the opportunity to speak with a former lead attorney of the CFPB off the record today about the definition of consumer. Could a small business be construed as a consumer? The short answer was no. The long answer was that there is no specific definition of consumer at the CFPB but it was meant to represent individuals. Although businesses at the end of the day are run by individuals, I got a pretty confident response that the CFPB would not have jurisdiction over a business lending money to a business, even if it was a very small 1 or 2 man operation. If they were acting in a commercial capacity, then they’re no longer consumers.
The other side of her argument was that it would take up too much resources to take on a case where the victim class was basically outside of their scope. The CFPB already has enough on their plate.
Is the government busy?
I also spoke with a few lobbyists and payments industry attorneys off the record and the unilateral response was that MCA and alternative business lending were not on any agenda, nor does the government have the resources to juggle something that is basically…insignificant in their eyes.
In the grand scheme of financial issues, a few billion year in small business-to-business financing transactions isn’t worth anyone’s breath. “A business acting in a business capacity was unhappy with a business contract they entered into? Take it up in civil court,” I imagine a regulator might say.
Regulators aren’t completely in the dark about MCA. Just a month or two ago, several industry captains and myself included were contacted by the Federal Reserve as part of a research mission to basically find out what this industry even was. The feds appear to have stumbled upon the MCA industry as part of their research into peer-to-peer lending. Who would’ve thought a 16 year old industry could be so stealthy?
If the big PR machines like Kabbage, Lending Club, and OnDeck Capital didn’t exist, I’m inclined to believe no one in the government would’ve heard of MCA for at least another 10 years. In 2014, they’re just now discovering it.
My gut tells me we’re a long way from any kind of regulatory enforcement. In a session I attended at Transact 14 today, a former member of the Department of Justice and a current member of the Office of the Comptroller of the Currency both offered examples of cases that took 3-8 years before there was an enforcement action. In each scenario, they alerted the parties there was a problem and they were given time to correct it. They had to show progress along the way and eventually when no such progress was made after years of warnings, they acted.
In the conversation of regulation, alternative business lending and MCA are relatively tiny. Lending Club does more in loan volume each year than the entire MCA industry combined. So long as there’s no fraud involved, small business-to-business financing transactions are not likely to make it on the agenda for federal regulators for a long time. That doesn’t mean it won’t be there some day in the future.
I think it was Brian Mooney, the CEO of Bank America Merchant Services that said in the Transact 14 roundtable discussion that if something feels wrong in your gut, don’t do it. Debra Rossi, the head of Wells Fargo Merchant Services added that you can’t tell a regulator, “I didn’t know.” Keep those suggestions in the front of your mind.
No police
For the foreseeable future it’s on us as an industry to find a resolution to stacking. There’s no such thing as the cash advance police. On one side is tort law. On the other is creating best practices and actively educating newcomers. That’s where the blood boiling debates need to turn to. After all, there’s already a large crowd that yawns over seconds, a group that wholeheartedly believes a stack is just as legitimate as a first position deal.
Instead of waiting for a referee to call foul on somebody, I think 2014 is the year to realize that you might be stuck in the room with the person you hate. Could you bring yourself to tolerate them for years to come?
Blind spot
We should consider that the greatest threat to the industry may not come from within, but from outside. More than 50% of MCA/alternative business lending transactions are repaid via ACH. Government action on ACH providers or the banks that sponsor them could end up hitting this industry as collateral damage.
One metric that banks and regulators consider is the return rate of ACHs, namely the percentage of ACHs rejected for insufficient funds or rejected because the transactions weren’t authorized. Daily fixed debits run the risk of rejects and boost the return rate. Could the frequency of your rejects eventually scare the processor into terminating the relationship? With the pressure they’re getting from the Department of Justice, there’s always the possibility.
Data security is another sleeping giant to consider. Do you keep merchant data safe? Are you protected from hackers?
Know your merchant. The push towards automated underwriting seems dead set on eliminating humans from the analysis. But what if the algorithm misses something and loans get approved to facilitate a money laundering scheme? Or what if it approves a known terrorist?
Paranoia
If you’re paranoid you’re doing something wrong, then maybe you are doing something wrong even if there’s no current law against it. Follow your gut, create value, and work together. Who knows, maybe one day there will be an ETA-like organization for MCA and alternative business lending. Now is a good time to be proactive.
Join Me at Transact 14
April 1, 2014 I’ll be at the ETA’s Transact 14 Conference in Las Vegas next week (Apr 8 – 10) wearing my journalist hat for DailyFunder. DailyFunder is currently the only publication dedicated to merchant cash advance and alternative lending and is a media sponsor of this year’s event. All attendees will be able to pick up a free copy of the latest issue of the magazine at designated distributions bins.
If you’re on the fence about going, allow me to convince you. The Annual ETA hosted conference is more than a social event or meet and greet. It’s a chance to ink deals, forge partnerships, and learn about opportunities that you’ll never hear about from the comfort of your office. Of course you’ll only get out of it what you put into it. The Who’s Who of payments and financing will be all in one place. Are you one of them?
CNBC will be broadcasting the event live. It’s been reported that this year’s show has enlisted a record amount of exhibitors.
Going to be our biggest show in history! MT @MWarehouse: Who's going to #ETATRANSACT next week in #Vegas? pic.twitter.com/5zFiUm8qbY
— Jason Oxman (@joxman) April 1, 2014
I’ll be taking photos and jotting down notes for both the live blog and post show recap for the May/June issue of the magazine. So if you’ve got something cool to show off, email me at sean@merchantprocessingresource.com or sean@dailyfunder.com and I’ll be happy to come pay you a visit.
pre-registration for the event closes in less than 5 hours but you’ll be to get tickets on site.
And of course if you’re planning to bring your wolf pack to Vegas, you might want to read DailyFunder’s helpful tips on how to keep your wolf pack in check. 😉
Hope to see you there.
ETA Expo Recap
May 3, 2013 Recap of the ETA Expo as it pertains to Merchant Cash Advance:
- Just about every funder has an ACH program or is working on implementing one.
- Many funders are licensed lenders or are working to become licensed in the states where it may be necessary. There actually seemed to be a lot of excitement about this. Funders are finding comfort in being subject to state mandated regulations as it probably raises their legitimacy and it will make their businesses easier to value when trying to raise money or sell.
- The ACH repayment market will be larger than the split-funding market this year. There’s no doubt in my mind about this. That means that ACH funding is now the primary protocol behind Merchant Cash Advance.
- Almost everyone is working hard to build up their technology. I got a personal demo of RetailCapital’s ISO/Agent system in addition to Capital Access Network’s new CapTap. Both are great. Capital Stack also has a beautiful platform.
- Stacking is the issue of 2013 as I heard that word uttered probably every 30 seconds for a whole week. I know the NAMAA folks are talking about it but I don’t know what the consensus is. It’s important to keep in mind that many funders aren’t NAMAA members and that affects NAMAA’s ability to dictate policy. Capital Access Network, the largest funder in the industry isn’t even a member.
- Speaking of NAMAA, they refaced their website and it looks A LOT better. I see only 14 members listed but it’s my understanding that there are closer to 20 of them.
- Factor rates are all over the place. Swift Capital has a new 1.099 program, which has got to be the first one to fall under the 10% threshold aside from Amex’s Merchant Financing. Higher risk deals however still operate in the 1.49 and up range. There is no one-size-fits-all product anymore.
- There were several direct lenders walking around that I had never heard of and they are apparently doing significant monthly volume. More and more people are getting into the funding business.
- It’s exhausting trying to keep up with the news surrounding On Deck Capital. They are on a very deliberate path and what we keeping seeing and hearing is them just checking things off on their to-do list. I bullet-pointed my theory on DailyFunder in response to a few posts.
- Discover and Priority Payments threw great parties.
- New Orleans has a lot of charm.
Make sure to check out my updates and photos that I’ve finally posted from the ETA Expo on DailyFunder and feel free to add your own if you were there.
Dozens of photos from the show
Also read: Soul Mates: Merchant Cash Advance and Silicon Valley VCs
Follow us at the ETA Expo
April 30, 2013May 3, 1:00am: I underestimated how easy it would be to make frequent updates. Wednesday was fantastic. I uploaded a couple dozen photos and updates all at once earlier today over on DailyFunder. As soon as the show was over, I found myself on Bourbon Street at the Discover party followed by the Priority Payments party. Both were a great time.
My Recap of the show is up now: ETA Expo Recap
Soul Mates: Merchant Cash Advance and Silicon Valley VCs
Original story about On Deck Capital’s investment from Google Ventures and Peter Thiel
My theory on why On Deck Capital took a paltry $17 million from Google Ventures and Peter Thiel
Photos and updates from the ETA
————————————–
May 1, 1:00am: Great start to the show this evening. Merchant Cash Advance providers and alternative business lenders continue to have a very strong presence in the payments industry. The booths I saw include: RetailCapital, NextWave Funding, Merchant Cash Group, On Deck Capital, Capital Access Network, Strategic Funding Source, American Finance Solutions, Swift Capital, MotherFund, and Principis Capital. GRP Funding and Paramount Merchant Funding are also on the exhibitor list but I didn’t spot their booths yet. That’s pretty substantial and it omits the major presence of Merchant Cash Advance companies that aren’t exhibiting. I bumped into Merchant Cash and Capital and walked the floor a bit with David Rubin of Capital Stack.
I met the guys behind Super G Funding which lends money against residuals. They’re great guys and they have such a unique role in the industry.
I think every funder I spoke with was quick to mention that they do 12 month deals and either offer direct debit repayment or will have it soon. The ACH train has disrupted the split-funding market pretty severely though many funders continue to do big numbers via split.
Nobody seemed to have an appetite for low FICO score deals (500s and below) except for Merchant Cash Group and Capital Stack which target the higher risk market intentionally. And when I say “don’t have an appetite for,” I literally mean when asking a funder if they do below 500 credit, the answer is some version of “HECK NO!!”
Overall tone, and perhaps its because opening night included open bar, but it was very optimistic. Most funders seemed intent on expanding and are eager to service as much business as possible. I definitely get that sense that there is a real focus these days on the bigger fish ISOs ($1 million+ in referral business a month). When newbie brokers enter the space, funders spend an enormous amount of resources developing them and many times they just don’t pan out. Either the brokers don’t have the capacity to do more than a handful of deals, or they just don’t “get it.”
If you’re a mom and pop ISO and you have just 1 or 2 deals a month, it’s more difficult these days to get time and attention from a funder. Capital is flooding into the industry and everybody wants partners that can produce volume. From a resource standpoint, the “1 and done” reps are not an efficient use of time.
Big ISOs have a lot of negotiating power at their disposal these days. In the last 7 years, it was good to be an ISO, then hard to be an ISO and now it’s good again. Many things in MCA have a weird way of going full circle. Hope to see you on Wednesday.
————————————–
Apr 30, 1:00am: 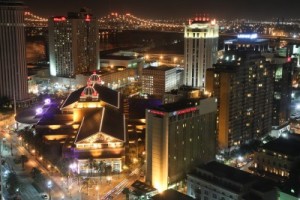 Merchant Processing Resource will be publishing updates as often as we can from the ETA Expo in New Orleans. I am very excited to be down here. Earlier today I had the opportunity to eat beignets at Cafe Du Monde, visit the French Market District, and take a ride on the Natchez Steamboat on the Mississippi River. But starting Tuesday, it’s all business. A schedule of events can be found on the ETA’s website.
You can follow along with everyone else in town on twitter using #ETAExpo2013 or #ETAExpo13
and of course via the DailyFunder Merchant Cash Advance iPhone App.
Some pre-conference tweets:
ETA Expo 2013 on Twitter
pre-conference tweets
Storified by Sean M· Mon, Apr 29 2013 22:21:50
Here’s to learning, networking, and having fun!
– Merchant Processing Resource
https://debanked.com
It Got Said – Merchant Cash Advance – Friday Fun
April 26, 2013In honor of Friday, we’re having some fun…
Caught on twitter
And Also
Business Financial Services landed an $82 million credit line
A third industry captain will be joining DailyFunder’s CEO Corner early next week at the ETA Expo. Stay tuned! Read articles put out by two other MCA CEOs.
Sean of Merchant Processing Resource and the DailyFunder co-founders will be on the trade show floor of the ETA Expo next week. Considerable time will be spent at Merchant Cash Group‘s exhibit at booth #751 and a guest appearance at Strategic Funding Source‘s booth at #916. We’d love to see you there. Make sure you download the DailyFunder iPhone app as we will try to maintain a live blog of the events.
Merchant Cash Network Hosts MCA Info Session
April 20, 2013I recently had the opportunity to sit in on an informational session for small business owners hosted by New York City based ISO, Merchant Cash Network (MCN). On Wednesday April 10th, small businesses packed into a room at 1375 Broadway to learn about alternative financing with a focus on Merchant Cash Advance. MCN’s vast knowledge on the subject was obvious and I definitely believe these grass roots sessions are an excellent way to both educate the public and to bring businesses together to network. Great work guys!
Merchant Cash Group NCAA Contest Winners Announced
April 10, 2013 If you weren’t in this year’s NCAA bracket competition hosted by Merchant Cash Group, you missed out on a lot of fun!! But that’s okay, because well there’s always next year 🙂
From Heather at Merchant Cash Group:
“Merchant Cash Group had the privilege of hosting a NCAA March Madness Bracket Challenge offering a top cash prize of $500.00. We invited people from all over the financial industry to join our friendly competition where even the losers walk away with a cool prize. The Brackets were shaken up severely with the Cinderella story of Florida Gulf College and the early elimination of some of the top schools, uh hum Kansas St, New Mexico and UNLV to name a few. By April 8th we were down to only one person (Billy Crowe) who had Louisville winning it all and with that made a come behind win with a 15 point spread.
Now, while Billy is walking away with the Grand Prize all the other participants will be receiving a basketball bobble head trophy announcing to everyone that they in fact our bracket challenged. I would like to thank everyone who participated in the competition and I look forward to hosting more networking opportunities for our space. Below is the final standings and in the interest of saving ego’s please do not rag the losers to hard after all they are stuck with a bobble head.”
- Billy Crowe – PricewaterhouseCoopers Final Score: 111
- Heather Francis – Merchant Cash Group Final Score: 96
- Badger Morning – Merchant Cash Group Final Score: 80
- Sean Murray – Raharney Capital Final Score: 74
- Kara B – Merchant Cash Group Final Score: 73
- Jason Fullen – NVMS Final Score: 69
- Michael Bernier – SBS Capital Final Score: 59
- J. Mark Anderson – Business Funding USA Final Score: 50
- Scott Williams – Financial Advantage Group Final Score: 48
————————————
My chances at bracket gold were dashed when New Mexico lost in the first round to Harvard. Harvard…
Thank you Heather for the fun and also I want to let everyone know that I will be spending some time at Merchant Cash Group’s booth during the ETA expo (#751) on behalf of MPR and DailyFunder. Merchant Cash Group is a great MCA company and I am honored to participate in their exhibit.
ETA Expo 2013 is Approaching
April 9, 2013 The ETA Expo 2013 in New Orleans is fast approaching. If you haven’t registered yet, you should probably go and do that over at http://www2.electran.org/am13/. This will personally be my first time to New Orleans and I am excited to meet and speak with a lot of you. Merchant Processing Resource and DailyFunder will be running a live blog to cover the happenings both big and small each day. So if you’ve got an iPhone and you haven’t downloaded the app yet, now is a good time to go and do that so that you can follow along.
David Rubin, a co-founder of DailyFunder will also be on site and we plan on having some fun giveaways.
So don’t forget plan your meet-ups, what to do, and who to see before you arrive. Talk about it on DailyFunder.