
Sean Murray is the President and Chief Editor of deBanked and the founder of the Broker Fair Conference. Connect with me on LinkedIn or follow me on twitter. You can view all future deBanked events here.
Articles by Sean Murray

New York’s Fourth Department: Revenue Purchase Agreements Are Not Loans
August 25, 2023A lawsuit brought by Samson MCA LLC against Joseph A. Russo M.D. P.C./IV Therapeutics PLLC, DBA Aspire Med Spa & Joseph Russo & Marco V Beatrice has brought revenue purchase agreements back in to the legal spotlight in New York State. Once again its been affirmed that they’re not loans.
In May 2021, plaintiff Samson MCA sued defendants for breach of contract and won on summary judgment despite defendants’ contentions that the revenue purchase agreements at issue were actually “criminally usurious loans.” Defendant Marco V Beatrice appealed. After a very careful analysis of the agreements, a final decision was issued by the Appellate Division, Fourth Department on August 11, 2023.
“On appeal, [defendant] contends that the agreements are void because they are criminally usurious loans and that the court therefore erred in granting plaintiff’s motion and denying defendants’ cross-motion with respect to him,” the Court stated. “Thus, the central question before us is whether the two agreements were, in fact, revenue purchase agreements or whether they were, instead, loans.”
The Court said that when determining whether a transaction constitutes a loan, courts must determine whether the amount is repayable absolutely or under all circumstances:
“Usually, courts weigh three factors when determining whether repayment is absolute or contingent:
(1) whether there is a reconciliation provision in the agreement;
(2) whether the agreement has a finite term; and
(3) whether there is any recourse should the merchant declare bankruptcy”
Final decision:
Contrary to [defendant’s] contention, plaintiff established as a matter of law that the agreements were revenue purchase agreements rather than loans, and [defendant] failed to raise a triable issue of fact with respect thereto (see Principis Capital, LLC, 201 AD3d at 754). Here, the agreements submitted by plaintiff contained reconciliation provisions requiring the adjustment of the remittance amount upon request based on changes to the entity defendants’ revenues, and had no finite term and no payment schedule. Additionally, as noted, each agreement contained an acknowledgment “that [plaintiff] may never receive the purchased amount in the event that [the entity defendants’ business] does not generate sufficient revenue” and, for the most part, plaintiff did not have recourse in the event that the entity defendants declared bankruptcy (see Streamlined Consultants, Inc. v EBF Holdings LLC, 2022 WL 4368114, *5 [SD NY, Sept. 20, 2022, No. 21-CV-9528 (KMK)]).
We have reviewed [defendant’s] remaining contention and conclude that it does not warrant reversal or modification of the judgment.
The original lawsuit can be found under Index No. 129401/2021 in the New York Supreme Court.
Full decision by the Appellate Division, Fourth Judicial Department can be found here.
Only 1 Month Until deBanked CONNECT San Diego
August 21, 2023
There’s just one month until deBanked CONNECT San Diego. The Wyndham San Diego Bayside was thankfully spared any impact from the weather that passed through the area this past weekend, which means the big show is ON IN FULL FORCE! Here’s some of the speaking sessions you can expect to see:
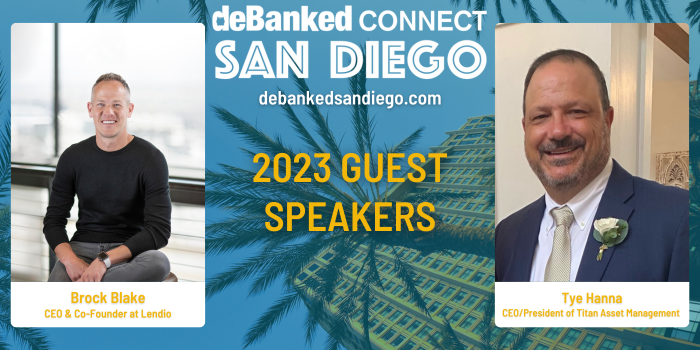
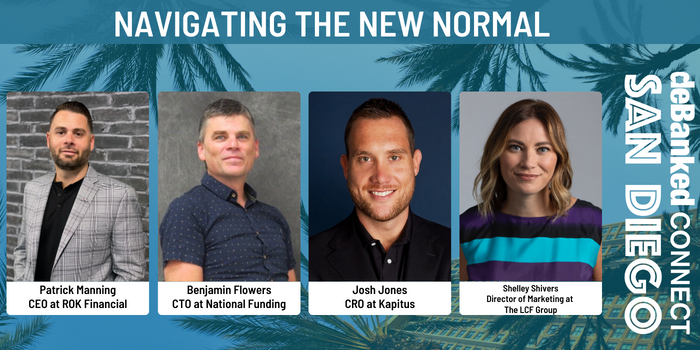
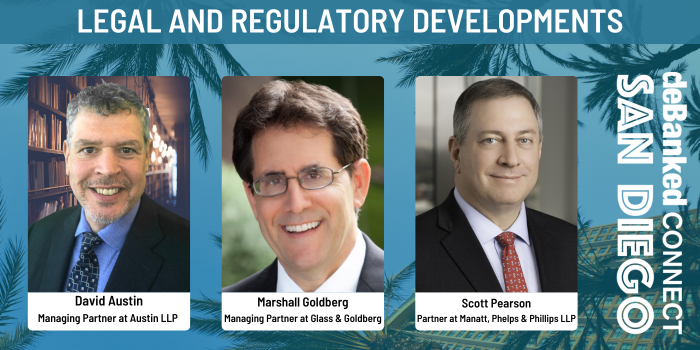
Plus, take advantage of the incredible networking opportunities that a deBanked CONNECT event offers!
We’ll see you there!
The New York Disclosure Law is Here
August 1, 2023 The New York commercial financing disclosure law has arrived. Are you in compliance with it?
The 53-page requirements can be viewed here.
While the law is similar to the one recently rolled out in California, there may be some key differences. Your best bet is to contact a lawyer that is equipped to help you with this very thing. If you need a recommendation for one, email me at sean@debanked.com.
If you have no idea what this disclosure law thing in New York is all about, you need to catch up ASAP! This law was passed in 2020 and went through a formal rule-making process that lasted years. The rules were finalized on February 1, 2023 and were mandated to go into effect six months from that date.
Here’s a map of what you should be paying attention to right now!
New York State Loan Initiative Takes on Fintech Type Pitch
July 24, 2023 If a business owner told you they had been approved for a 3-6 year loan up to $150,000 with no origination fees, no prepayment penalties, and interest rates ranging from 9.25 – 12.25%, would you believe it was a real offer?
The criteria, after all, is just a matter of:
– having been in business at least 1 year
– having strong previous cash flow and projected cash flow
Not only is this real but it’s being rolled out by New York’s “Forward Loan Fund 2” as a working capital loan that can be used for equipment, payroll, utilities, rent, supplies, marketing and advertising, building renovations, and other expenses. The state stops short of calling itself a fintech platform or online lending platform, instead referring to itself as a “virtual platorm” that is “accessible anywhere in the state.”
This is the second run of this program. The first distributed loans to 1,700 small businesses.
“It was a godsend,” one testimonial posted on the NY loan fund site says. “NDC made it so easy. It took two weeks and the money was in our account. Can you feel my joy?”
The program offers more than just capital, promising that there is a “network of Entrepreneurship Assistance Centers (EAC) available to provide free support before, during, and after the loan application process.”
The program is backed by participating lenders that include Accion Opportunity Fund, Ascendus, NDC, Pursuit, and TruFund Financial Services. There is about $150M available to be loaned out “with plans to recycle and lend additional funds over the life of the program.”
“Due to a limited amount of funding availability and the high volume of applications expected, it is anticipated that not all applicants will be able to receive a loan,” a disclaimer says.
At a minimum, the documents required to be considered are:
1. Most recently filed tax returns OR internal financial statements.
2. Schedule of ownership
3. Personal guarantee from each individual owner greater than 19%
4. Articles of organization
5. Credit report
Congressional Effort Underway to Reinstate the SBLC Moratorium
July 23, 2023 It only took 40 years for the SBA to lift the moratorium on licenses for Small Business Lending Companies. Now there’s a congressional effort underway to reinstate it. The “Community Advantage Loan Program Act” which had not been assigned its own individual bill number in the Senate at the time of this writing, nevertheless garnered 18-1 approval by the Senate’s Small Business and Entrepreneurship Committee last week.
First, the proposal concludes that the SBA does not have adequate resources to issue more than 3 new SBLC licenses. Second, it calls for a 5-year moratorium on new licensees having Delegated Authority which is the authority granted to a lender to process, close, service, and liquidate SBA loans without prior SBA review. Third, it imposes new annual stress tests that would enable the SBA to revoke the new licenses. All in all, it is effectively a rollback of the new SBA rules, and those are just some key components of it.
Senators Ben Cardin, D-Md. and Joni Ernst, R-Iowa, are the sponsors of the proposal.
Among the small business lending companies that would be impacted by this is Funding Circle. Ryan Metcalf, Head of U.S. Public Affairs at Funding Circle, told deBanked that “We estimate that the proposed Cardin/Ernst bill would reduce 7(a) Small Loans made by Funding Circle over the next three years by 26%, of which 33% is to SMB in LMI neighborhoods and 40% in rural areas.” That’s without considering the increased regulatory costs or the likely reduced borrower conversion rate as a result of having non-delegated authority, Metcalf added.
The initiative by Cardin and Ernst does not come as a surprise. The two had been critical of the the SBA’s plans to allow more SBLCs all along, arguing that new licensees were likely to be fintechs who were “the very entities responsible for issuing billions of dollars-worth of Paycheck Protection Program (PPP) fraud”
Virginia Now Has 150 Registered Sales-Based Financing Providers
July 11, 2023 The number of registered sales-based financing providers in Virginia is increasing, according to the most recent available public records. At last count there were 150. Both funders and brokers are required to be registered if they plan to do any MCA business with VA-based merchants.
If you’re not on the list and you believe you registered, you may not have completed all the steps. Not only do you have to register as a sales-based financing provider but you also have to register to transact business in the state.
1. Register as a sales-based financing provider.
2. Register to transact business in the state.
So there are two applications and registrations to fulfill the requirement, per deBanked’s understanding. See more info here. Please consult an attorney if you have questions.
The state has been very quick to add new registrants to the list so if someone said they registered months ago but that the government has been slow to add them, it might actually be a matter of them missing a requirement instead.
Sales, Tech, Funding, and the Law in California
July 7, 2023deBanked sat down with three individuals from across the spectrum of the small business finance world in Southern California.
With David Austin, an attorney and Managing Partner at Austin LLP, we discussed merchant cash advance law and the importance of legal counsel to run one’s business correctly.
With Trey Markel, VP Sales & Marketing at Centrex Software, we discussed corporate finance, AI, blockchain, tech, and more.
With Justin Thompson, Chief Revenue Officer at National Funding, we talked about what’s changed in sales and the state of selling.
They’re all on deBanked TV or listen to them on Spotify!
And don’t forget to register for deBanked CONNECT San Diego!
Can’t Watch Videos In the Office? deBanked is On Spotify
June 30, 2023Can’t watch videos on company time? Catch up with what’s going on in the industry by listening to deBanked’s podcast on your commute. With more than 500 deBanked TV segments altogether since 2020, we’ve been adding some of the most memorable and informative ones to Spotify.
Recent interview guests include:
- Justin Thompson – National Funding
- Andrew Carman – PerCina Report
- Steve Geller – Leasing Solutions LLC
- George A. Parker – VenSource Capital
- Nancy Robles – Eastern Funding
- Alyssa Guglielmi – JRG Funding
- Porsha Brooks – Lenpick