
Sean Murray is the President and Chief Editor of deBanked and the founder of the Broker Fair Conference. Connect with me on LinkedIn or follow me on twitter. You can view all future deBanked events here.
Articles by Sean Murray

Mike Steeneck Joins American Finance Solutions & Opens East Coast Office
January 29, 2012For release on MPR — AFS is proud to announce that after five years in sunny Los Angeles, we have finally opened our first East Coast office. More importantly, we have added another valuable member to the AFS team.
We are pleased to announce that Mike Steeneck, an industry veteran with years of experience in the payment processing and alternative funding arena has joined AFS as Vice President of Business Development. Many of you know Mike from his last position as EVP/COO of OnePay. Mike has also held positions as President of Business Development at AdvanceMe and Senior Vice President of Sales and Acquisitions at First Data where he successfully launched many newly formed business units.
Mike’s focus will be on building relationships with East Coast ISOs and processors nationwide. In addition, Mike will be instrumental in crafting sales strategy and product development as AFS enters new markets and diversifies its sales channel. Most importantly, Mike will work closely with our existing and new ISO partners to increase sales and help AFS build on its reputation as the funding source of choice.
Mike brings tremendous experience and expertise to AFS and we’re thrilled to have him. Mike can be reached directly at 800-760-5516, ext 141 or by email at msteeneck@americanfinancesolutions.com
Source:
American Finance Solutions

The Small Business Lending Climate is Bad, But it’s Not a Disaster
January 27, 2012 We’re proponents of the Merchant Cash Advance (MCA) financial product, but we also believe in objectivity. Over the last several years, MCA providers have collectively rallied the masses by branding themselves as a source of business financing in an economy where financing is scarce.
Many people consider the collapse of Lehman Brothers on September 15, 2008 to be the official start of the latest recession. Some will argue that we’re still in that recession. We would probably agree with that. Either way, there hasn’t been much improvement in the financial markets.
Yesterday, on Sean Hannity’s radio show, guest speaker Donald Trump, said “banks aren’t lending.” That’s verbatim and it says a lot, considering that yesterday was January 26th, 2012, a full three years after Lehman’s demise.
A friend of ours that does commercial banking in Philadelphia reiterated the same thing to us a few months ago and even went so far to reveal that restaurants and retail establishments are on their lending blacklist. These revelations paint a grim picture and it’s fortunate that the MCA industry has risen to the challenge to support small business owners.
But there is light at the end of the lending world’s black hole. This morning we had a meeting with a big bank in New York City and of course we asked the question, “Are you lending to small businesses?” They responded, “yes”, and we expected them to follow it with a “but.” Except they didn’t. In fact, they said that small business lending was their biggest market right now.
Intrigued, we demanded to know more. Approximately 50% of applications are being approved and the criteria is as follows:
- Minimum two years in business
- Minimum personal FICO score of 680
- Minimum $250,000 in annual sales
- Must have consistent pattern of sales
- No history of overdrafts or NSFs
- Must prove history of keeping substantial cash reserves in the business account
- Must be current with all vendors and business property landlord
- Collateral may be required
- Maximum approval amount is 20% of annual gross sales
This checklist is challenging. That’s why leveraging your future credit and debit card sales to obtain a large chunk of capital upfront is not only the preferred method of financing for businesses with bad credit, but also for those that are making a serious investment in themselves.
Nonetheless, if a bank IS lending, we’ll be the first ones to admit it. MCAs offer a lot of powerful benefits, but if all banks start lending again one day in the future, quoting Donald Trump might not have the same impact it once did. Fortunately, there are twenty other reasons why MCA is a solid solution, and what banks are doing or aren’t doing is completely irrelevant.
– deBanked
https://debanked.com
Note:
If you are a small business located in the New York City area that is interested in a loan as described above, we would be happy to personally refer you to that bank.
Put Your FUNDED Pants On – It’s Time for Merchant Cash Advance
January 27, 2012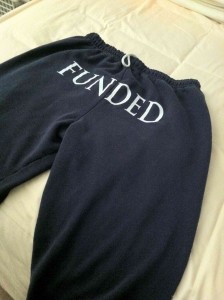 Put your FUNDED pants on because today you’re going to find out just how easy it is to get business financing.
The Merchant Cash Advance industry is expected to surpass $1 Billion in annual funding within the next two years. There are at least thirty two major nationwide providers of capital who want you to be part the revolution. They’ve all got different strengths so you can simply choose the one you believe to be the best fit.
Stop sitting on the sidelines while your competitors are getting funded with less than stellar credit, no collateral, and no fixed payments. The industry average turnaround time from application to funding is approximately seven days.
Do you:
- Accept credit or debit cards as a form of payment?
- Have a copy of your most recent merchant account and bank statements?
- Have a copy of your business property lease or recent mortgage statement?
- Have time to fill out a one page application?
If you answered ‘yes’ to all of these questions and you’ve never considered Merchant Cash Advance financing before, you’re part of a growing minority. There is no cost to apply and no reason not to at least learn about what your options are. Each and every provider in our directory is staffed with experts that can explain exactly how their program works, how much funding you’re eligible for, and how long you can expect the process to take. There are offices and agents all over the country, so whether you prefer to do business in person or over the phone, we’re pretty confident you’ll find what you’re looking for.
If you couldn’t tell, we’re really excited about how Merchant Cash Advance will help rebuild the economy in 2012. So choose a few providers to contact, gather up the documents stated above, and make sure you dress for the occasion. You can never go wrong with FUNDED pants.
Express Working Capital Gives Back
January 21, 2012According to their latest release, Dallas based Merchant Cash Advance Provider, Express Working Capital (EWC) has donated $1,000 to a worthy cause. “The funds went to Dress for Success Dallas, a company striving to empower disadvantaged women with professional attire and a network of support. The donation was made possible by EWC’s recent Facebook campaign.”
Express Working Capital is most known for its business cash advance solution called Convenience Capital™. Money is advanced and repaid through a very simple process so businesses can receive a much-needed merchant cash advance without the snowball effect caused by many other loans that leads to overwhelming debt.
Learn more by visiting EWC’s Facebook page
The 28% You Don’t Want – New IRS TIN Matching Regulation
January 21, 2012 If your merchant service provider (MSP) doesn’t have your proper business information on file, you could be in for a world of hurt. As per Section 6050W of the Housing Assistance Tax Act of 2008, all electronic payment transactions have been reported to the IRS since January 1st of last year. In order to ensure this reporting is accurate, certain business data must match the data on file with the IRS, such as:
- Your Taxpayer Identification Number (TIN)
- Your Legal Business Name
- Your Legal Business Address
- Your Business Organization Type (e.g. Corporation, LLC, Partnership, Sole Prop., etc.)
MSPs are required to report gross revenue, so chargebacks and refunds are included. The official ruling states:
Section 6050W(a) provides that each payment settlement entity must report the gross amount of reportable payment transactions for each participating payee. The proposed regulations defined gross amount as the total dollar amount of aggregate reportable payment transactions for each participating payee without regard to any adjustments for credits, cash equivalents, discount amounts, fees, refunded amounts, or any other amounts.
And if your tax information doesn’t match, the IRS will withhold 28% of all your payments starting on January 1st, 2013, whether it’s your fault or not. Once that happens, your MSP can’t refund you and all issues must then be handled with the IRS directly. If you haven’t received any kind of alarming notice that your information doesn’t match, this warning doesn’t apply to you. Although, it can’t hurt to call your account representative to confirm that all information is up to date and verified. Better safe than sorry.
If you didn’t know about this law, now is a good time to read up on the dense technicalities of it in this 520 page document.
Rewards: The Next Phase of Merchant Cash Advance Evolution
January 21, 2012 Sky miles and 1% cash back are practically standard benefits of using your credit card, so why shouldn’t you get a little something extra with your Merchant Cash Advance (MCA)? I pay my credit card bill on time every month because I am a responsible customer. As a result, the bank continues to extend me credit when I need it. But that’s not all they do, they also send me a check for 1% of every purchase that I make. That’s pretty nice of them!
Sure, it’s a great way to encourage spending but it also promotes loyalty. I get a million credit card offers a year and I have no desire to switch. Isn’t that something?
The Merchant Cash Advance (MCA) industry could learn a thing or two from this. While funding small businesses is practically a blessing in that of itself, there is a lot of fierce competition between MCA providers. Once a business has used MCA, it seems everybody starts fighting over whose going to fund them next. It must be quite an experience for business owners who are by now used to banks tossing them around like an unwanted hot potato. In the MCA industry, everyone wants to fund the potato.
The truth is though, the terms won’t vary much between firms and even if they do, the transaction cost might not be worth it. Switching to a new MCA provider can result in any of the following:
- A termination fee on your existing merchant account
- The purchase or lease of new POS equipment
- The installation of new POS equipment
- An additional service fee on top of the cost of financing
- Unexpected issues with trust or the service
If you have found success with the company that financed you, we can both agree that it’s easier to stay with them. But without additional incentives, you may be feel like your business isn’t appreciated. That’s probably not true and sometimes our sense of entitlement gets the best of us. The thing is though, we believe a little reward is just what you deserve. What makes a great MCA provider great is their ability to become a true partner in your success, instead of just silently collecting their purchased receivables. That’s why we propose the following:
- Cash back for hitting certain monthly sales targets
- Rewards for hitting certain monthly sales targets (gift cards, free advertising, a small business makeover)
- Access to free consulting (consultations from experts on how to best invest the money you receive)
Imagine the motivation you’d feel if your financing not only got approved, but led to a whole bunch of rewards if you invested that money wisely. We don’t have control over the nation’s MCA providers but we can plant the seed and wait for someone to do it first.
Let’s pretend that your business does $8,000 a month in credit card sales on average. One month, you hit $12,000. I think a little reward is in order! Send us an e-mail and tell us what you think.
– deBanked
A Personal Review of ROAMpay – The Mobile POS
January 4, 2012 According to ROAM Data, ROAMpay works in tandem with a compatible merchant account. That’s great, but we wondered throughout most of 2011 if the swiping unit and POS interface were any good. We wonder no more because Santa got us ROAMpay for Christmas. Thanks Santa!
When we tried out Square a few weeks back, we couldn’t believe how easy it was to set up and use. We figured nothing else would come close, but we were wrong. ROAMpay is awesome! We dare not claim one to be better than the other because both platforms are different.
Square has no activation fees or monthly fees but is limited in the sense that Square must also be your merchant processor.
- PLUS: Money is deposited the next day!
- PLUS: No monthly fees or setup fees.
- MINUS: The processing rates are non-negotiable.
- MINUS: You must use the Square POS technology to manage all your payments.
ROAMpay has a small activation fee and monthly fee to use but you can choose from a variety of merchant processors.
- PLUS: You have a variety of processors to choose from and therefore the ability to negotiate your rates.
- PLUS: You can supplement the ROAMpay mobile unit with your normal credit card terminal or desktop POS. They can all work together with the same merchant processor.
- MINUS: Most merchant processors charge regular monthly fees in addition to the ROAMpay fee.
- MINUS: You are not guaranteed to get overnight deposit. This is up to the processor to approve.
The MINUSes for ROAMpay are not necessarily negative marks. If you are a small business owner that already has a traditional merchant account, you can easily add mobile processing to your existing mix of payment methods. Nothing is different aside from the costs we mentioned.
Once you’ve got the swiping unit, the setup on your phone is unbelievably simple. You can even track cash payments through the POS interface and issue instant e-mail receipts to your customers. For instance, if you’re at a trade show, street fair, or similar event and a customer pays you with cash, those transactions can also be recorded and processed professionally through your phone. All historical transactions both cash and plastic can be accessed, reviewed, refunded, or voided if need be.
We don’t have a relationship with ROAM Data so Santa took the big risk that we’d dislike the product and put it on the Merchant Processing Resource’s naughty list. But that didn’t happen because this product is NICE!
Sean describes the experience of receiving and setting up ROAMpay in a 45 second video he created below:
To learn more about ROAMpay, visit ROAM Data’s official site.
Review Summary:
ROAMpay
Mobile Card Reader and POS
Reviewed by: Sean Murray
ROAMpay Swiper
Rating: 5 out of 5 stars
Date of Review: January 4, 2012