Regulation
DEBANKED?
October 14, 2026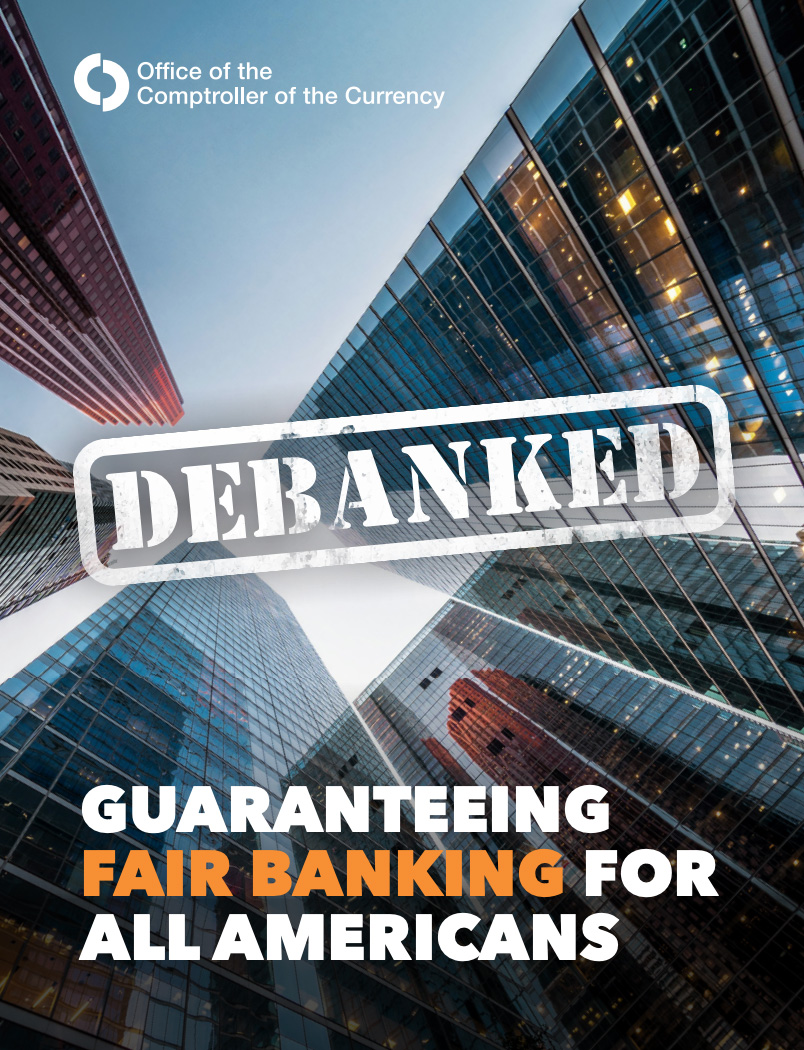
Imagine our surprise when it looked like another issue of deBanked Magazine had just been published…by a federal banking regulator. What actually happened is that the Office of the Comptroller of the Currency (OCC) published its final report on debanking, where its investigation determined that banks terminated or turned away customers on the basis of perceived reputational risk. OCC hopes to reduce or eliminate such practices in the future. “DEBANKED” is the signature headline printed on the cover. It would’ve fit in really well on our bookshelf had it been ours.
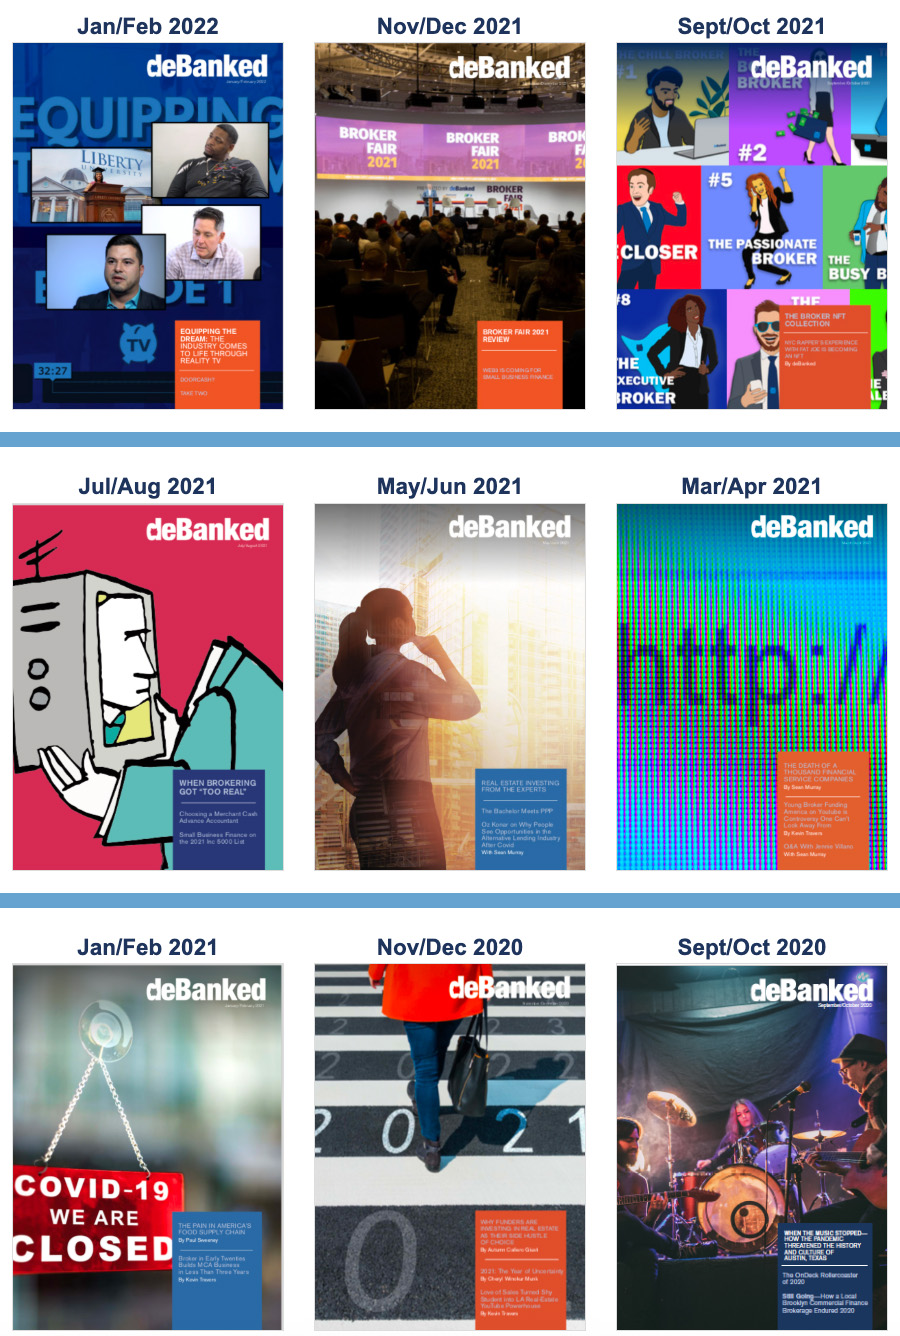
deBanked’s last magazine issue was published in January of 2022. All previous issues have been archived digitally here and print copies are still on display at our headquarters.
CFPB Reaffirms Excluding Merchant Cash Advances From Section 1071
October 13, 2026The CFPB recently published its annual Fair Lending Report. Under the section about small businesses, it reaffirmed its decision to exclude MCAs from the Section 1071 rule.
On May 1, 2026, the CFPB issued the final rule. The rule reduces the scope of “covered credit transactions” by limiting the types of transactions subject to reporting in order to focus data collection efforts on core lending products—loans, lines of credit, and credit cards—that are most utilized by small businesses. Accordingly, the rule sets forth certain exclusions: merchant cash advances, agricultural lending, and small-dollar business credit.
It further reiterated its decision to make other modifications to Section 1071.
In addition, the rule revises the definition of “small business” by reducing the gross annual revenue threshold from $5 million to $1 million. This will allow the CFPB to focus on collecting data related to micro and small enterprises, which are most relevant to section 1071’s goals. The rule also reduces the number of collected data points, extends and adopts a uniform compliance date of January 1, 2028, and simplifies the time and manner of data collection in order to allowinstitutions flexibility in how they comply with statutory requirements.
The rule updates are necessary to ensure reasonable implementation that does not restrict credit availability for America’s small businesses. The 2023 rule imposed a significant number of requirements that were not needed to advance the purposes of section 1071 of the Dodd-FrankAct. This rule recognizes those concerns and takes a more reflective approach, including just what the statute requires. The updates will result in cost savings for institutions and reduce the burden of data collection without sacrificing data availability.
5G Funding and its Owner Sued By SEC Over “MCA” Business
September 29, 20265G Funding represented that it had a profitable MCA business. But according to a lawsuit filed against the company and its CEO by the SEC, that was far from accurate. “The Portfolio was never profitable,” the lawsuit says. “5G Funding collected the full amount due on only about 30 of the 184 merchant cash advances.”
5G Funding formed in 2021 and by mid-2023 was insolvent. The company had raised $4.5M from 23 investors. Much of those funds are alleged to have been misappropriated by 5G’s owner and were used to “pay a down payment on a home, to pay his personal gambling expenses, and to purchase cars and watches.”
The SEC has sought relief on two securities fraud counts.
Soliciting Investments into an MCA or Business Lender on Behalf of Someone Else? Be Careful
August 19, 2026A recent civil lawsuit brought by the SEC against the orchestrator of an MCA funder-turned-Ponzi scheme came packed with claims against two other individuals who “acted as unregistered brokers.”
“The two were alleged to have solicited investors, explained the investment terms to those investors, vouched for the merits of the investment opportunity, facilitated the collection of investor funds, and received transaction-based compensation without ever registering as a broker-dealer with the Commission or associating with a registered broker-dealer,” the complaint alleges.
Unlike some syndication models, where investors pick and choose the individual deals they want to invest in, the defendants here told investors that the owner of the funding company would select which deals to fund with their money on his own. Investors were not entitled to know the names of the merchants due to confidentiality. Overall, the funder solicited at least 87 investors, raising at least $47 million, and promised fixed returns of between 22% and 53% on one-year investments and between 9% and 10% on shorter, two- to three-month investments.
The owner, who just pleaded guilty to wire fraud, misappropriated at least $11 million for himself—to pay gambling debts, personal credit card bills, home renovation expenses, and mortgage and car payments. He also used investor funds to pay earlier investors. While he did fund some deals, there were not that many. The scheme was able to go on for five years before collapsing in mid-2023.
The brokers who marketed the investment opportunity received commissions ranging from 5% to 25% of the amounts they brought in. They personally face claims that they violated Section 15(a) of the Exchange Act and should be enjoined.
The SEC complaint describes each of their violations “as a natural person not associated with a broker or dealer which is a person other than a natural person, made use the mails or any means or instrumentality of interstate commerce to effect transactions in, or to induce or attempt to induce the purchase or sale of, any security without being registered with the Commission as a broker-dealer.”
Factoring to Take MCA Fight to Federal Level
July 2, 2026In the wake of new merchant cash advance laws passed in Texas and Vermont, American Factoring Association President Cole Harmonson posted the next step is to take the fight against MCAs to the federal level.
Post below:
Vermont Follows Texas on Merchant Cash Advance Regulations
June 23, 2026“Certain automatic debts prohibited. A provider shall not establish a mechanism for automatically debiting a recipient’s deposit account unless the provider holds a validly perfected security interest in the recipient’s account under Title 9A, with a first priority against the claims of all other persons.”
Vermont has followed Texas with an identical automatic debit prohibition on sales-based financing. The new law, identified as House Bill 648, goes into effect on July 1, 2027. Technically it only applies on deals where the funding amount is less than $1 million. COJs are banned, APRs are required, and nobody can solicit a Vermont-based business with funding unless they have a lending license. The full language can be viewed here.
The Governor signed the bill into law on June 16, 2026. While this law copied some of the language enacted in Texas, its actual origins is from the Factoring industry that took full credit for the Texas law.
Serial Litigants May Target Websites and “Trackers” As Alternative to TCPA
June 12, 2026 The small business loan brokerage had played it safe. Rather than robodial and take their chances in the minefield of TCPA compliance, they ran ads on Facebook and Instagram and had the merchants call them. Inbound leads were gold, they cheered, until one of those inquiries came through a little differently. It was a demand for damages for having been tracked on the internet.
The merchant alleged that they had only been served ads on social media by that company because they had been tracked from a prior website visit. They hadn’t wanted to be tracked and there was no option to opt out of tracking. As a result, they demanded to be compensated, heftily.
By now, most internet users have at least heard the term GDPR, the General Data Protection Regulation that became a never-ending source of controversy throughout Europe, but not all are aware that states and litigants in the US have tried to create a similar framework for privacy. For some in the small business finance industry, the vast complexity of compliance was not fully understood until the lawyers came calling.
“Pretty much every MCA company is potentially a victim because they’re all doing advertising,” said Richart Ruddie, CEO of Captain Compliance, a firm that specializes in safeguarding companies against these sorts of threats. “What we do is we protect against the rise and surge in privacy lawsuits and privacy litigation. So, anybody running TikTok ads, Facebook ads, Instagram ads, any sort of technology that does session-replay where it watches you move the cursor on the screen, if they’re running Google Analytics, all of these are cases that have been tried and are being litigated over.”
Ruddie said that companies within the small business finance industry, including a few within the segment of MCA, have been hit with claims, and they’re now actively working with them to make sure it doesn’t happen again.
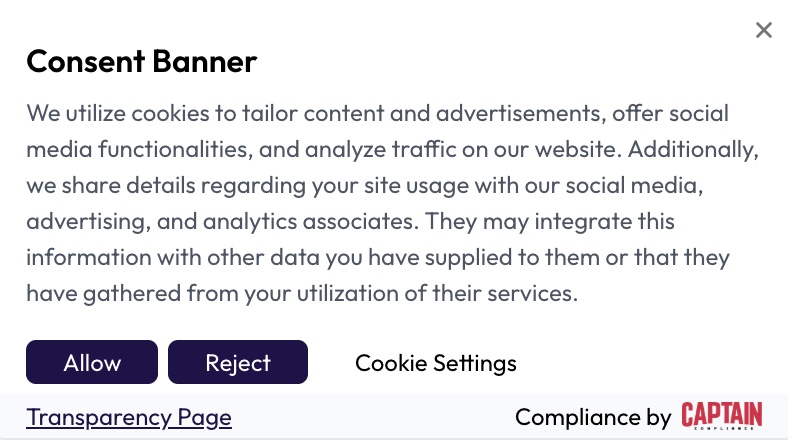 “What our software does is provides the ability for users to have consent to opt-in or opt-out of any sort of ad targeting, tracking, session-replay technology,” Ruddie said. “And then we also provide software that constantly keeps businesses’s privacy notices and privacy policies up to date with their tracking and what they’re doing as well as their data handling practices.”
The larger issue is that for companies that might already be aware of the risks, the solutions they’re using may not actually be compliant with the laws.
“What’s happening now is there’s a handful of these cookie banner softwares but they don’t work and they’re creating bigger issues because they’re like ‘Hey, you told me I could opt out, and then I turned off the selling and sharing of my personal information and you still track me,'” Ruddie explained.
This is made all the more complex by the fact that there are nearly two dozen states with their own twists on compliance. And a growing cottage industry of serial litigants that know this complexity could make website operators easy targets to profit off of. For instance, some of them are going around and running automated website scans just to see who to target. Ruddie said that he’s seen claims reach into the tens of thousands or hundreds of thousands of dollars for alleged privacy violations.
Preventative measures are within reach, however. Ruddie says that for a brand new customer they can get a company compliant in one to three business days. It’s hard for companies to hide in the shadows if they’re online because it doesn’t take much to see what’s there and what isn’t.
“You can right-click and look at the code and then you can see all the different tech and what’s running on the website,” Ruddie said.
New York State Bill Seeks to Criminalize Invoice Factoring, Merchant Cash Advances, and More
May 6, 2026A Senate Bill in New York hopes to rewrite the state’s criminal usury laws to include invoice financing, revenue-based financing, merchant cash advances, retail installment contracts, “or any transaction that in substance functions as the advance of funds in exchange for a future payment or obligation, regardless of the label assigned to such transaction.” S10127, introduced by Senator Rachel May (D), says that the purpose is to ensure “that businesses cannot evade New York’s longstanding usury laws by re-labeling high-cost financing products as services or other non-loan transactions, and to apply existing civil and criminal interest rate protections to covered financing arrangements.”
Any product that falls under these definitions would be deemed criminal if its all-in cost exceeds 25% per annum or the equivalent rate for a longer or shorter period. Depending on the circumstances it would either be considered a Class E felony punishable up to 4 years in prison or a Class C felony punishable up to 15 years in prison.
The bill has merely been introduced and has not yet made its rounds through the legislature. It can be viewed here.