MPR Authored
Kabbage: The Merchant Cash Advance of the Online Business World
August 23, 2011
Show me the Kabbage! Kabbage offers working capital to Ebay sellers that have difficulty qualifying for a bank loan.  They describe their financial product as an advance and funds are collected back automatically via the seller’s PayPal account. Sound strikingly similiar to something else?
Kathryn Petralia, the COO of Kabbage provided details in an interview with practicalcommerce.com. Funding ranges from $2,000 to $15,000 and approval is based on the following factors:
- Minimum 1 year in business
- Historical Ebay sales volume
- Historical PayPal account activity
- Credit score (although they are flexible)
- Business type
- Chargeback history
Petralia describes the cost as fee based, not rate based. “So it’s a maximum six month period that an advance can be held by a merchant and all of the merchants have to enroll in auto-payback system via PayPal. We automatically take a percentage of the initial advance amount every month. So the idea is in no more than six months, this sum of money will be paid off. A business will not be approved for an amount they cannot payback in that timeframe.”
Take away the fixed timeframe and we have all the signature features of a Merchant Cash Advance (MCA). The term loan, is even for the most part absent from Kabbage’s website. It’s difficult to overlook another feature of Kabbage, the ability to obtain funds in 10 minutes.
It’s easy to see if you qualify for an advance with Kabbage. Do you have about 5 seconds to spend with us? Simply enter your eBay marketplace ID and we will start the process. If you have sufficient activity and a great history of selling on eBay, we will then ask you to complete our application. You can go from eBay ID to cash (in your PayPal account) in as few as 10 minutes!
10 minutes? Traditional MCA funders don’t move THAT fast, nor should they. There’s a few things that alternative funding sources have learned since the financial crisis, and that’s not to go overboard. Funding in 10 minutes is great for the business owner, but doesn’t give the funding company any time to actually underwrite the deal. There’s a few questions we would like Kabbage to answer or consider.
- Do you ask where your applicants store their inventory?
- Is drop shipping an acceptable business model?
- Do you ask applicants if they’re current on their business property or home? If they’re renting a location, this isn’t going to show up on their credit report. If they’re on the verge of eviction, how would you know?
- Do you require contact information for any of their suppliers?
- Do you perform a criminal background check on your applicants?
- If the business conducts sales on a separate website in addition to their Ebay store, what’s to prevent them from discontinuing their Ebay operation while a balance is outstanding?
- What is the recourse in the case of default? What collateral is there?
- What if a business stops using the designated PayPal account and starts using another one. Are there any worthwhile deterrents?
- What if Ebay changes how they conduct business in a way that prevents or decreases the sales capability of their sellers? Are you prepared to adapt?
Though Kabbage is not exactly a Merchant Cash Advance, it’s close enough that we should welcome them to the community. A few tips for these folks though. The more automated the approval process, the higher the default rate. Does a business really need funding in 10 minutes or less? Also, the less grounded a business is, such as a long term lease in a brick and mortar location vs. an Ebay store, the less likely they will survive in the long run.
Good luck!
– The Merchant Cash Advance Resource
Our Favorite Merchant Cash Advance Commercials
August 23, 2011Posted on May 7, 2011 at 1:23 AM
 TV has never been a popular venue for Merchant Cash Advance (MCA) providers to advertise. There is a highly specific target market, small business owners that accept credit cards as a form of payment that are looking for funding, that simply reduces the cost effectiveness of mass media. Why pay to reach 100 people when 97 of them may not even fit basic criteria such as owning a business? It doesn’t make sense.
That doesn’t mean that TV or online video commercials for MCA don’t exist, they do. Unfortunately most of them tend to be poorly self-produced webcam miniclips that are so boring, they are more likely to turn someone away from the product, than to help anyone. No offense. But there are some providers that actually took the time, effort, and money to create something worth watching. Here are some of our favorites:
Does anyone else have one they’d like to share? We’ll be happy to show it off!
– The Merchant Cash Advance Resource
Credit Card Fees Hurt Waiters Tips
August 23, 2011
According to Fox Philadelphia, a few restaurants in the city are deducting the credit card processing fees from the waitstaff’s tips. “Basically, when you use a credit card to pay your bill and leave, say a 15 percent tip, your waiter may only get 12 percent.” It epitomizes the issue brought to light in an article we wrote back in March (Could Your Credit Card Tip Be Hurting Your Server?). Fox has no information at this time as to what restaurants are involved but a hearing is expected next month. We will keep you updated.
In the meantime, it never hurts to tip in cash. 
Mega Banks Enter Alternative Payments Market
August 23, 2011
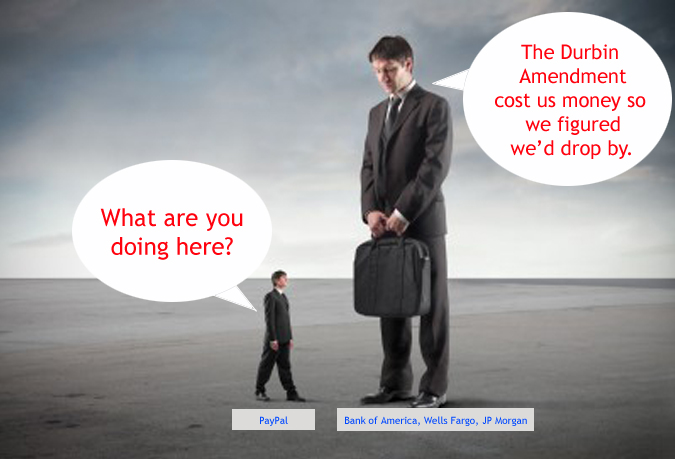
The banks are losing the fight against the Durbin Amendment but don’t count them out yet. The threat of billions dollars losses from interchange fees revenue has inspired them to innovate. So much so that alternative payment processors such as PayPal will soon face the wrath of a sleeping giant.
Bank of America, JP Morgan and Wells Fargo have teamed up to form clearXchange, a payment system for simple bank to bank transfers. In what they have dubbed a ‘coopetition’ (cooperative competition), there’s no new bank or merchant account needed. “PayPal and other systems require you to create an account separate from your bank account to transfer money, this new service will let customers simply log in to their existing bank account and enter the recipient’s name and e-mail address or phone number. The person they’re paying will then instantaneously receive an alert that money is being sent their way.”
And this doesn’t just compete against PayPal, it threatens cash and check payments as well. No longer will you be able to tell your friend that you don’t have any cash on you when they ask for the $20 you owe. D’oh!
Major retailers like Walmart stand to win big as a result of the Durbin Amendment, a triumph that will ultimately come to haunt them. With no interchange fees to earn, banks will get bored of debit cards and eventually phase them out. clearXchange is the new dawn of electronic payments and revenue for the big banks. And guess what? Durbin’s laws aren’t applicable to it. What have we done?
– deBanked