Stories
Soliciting Investments into an MCA or Business Lender on Behalf of Someone Else? Be Careful
August 19, 2026A recent civil lawsuit brought by the SEC against the orchestrator of an MCA funder-turned-Ponzi scheme came packed with claims against two other individuals who “acted as unregistered brokers.”
“The two were alleged to have solicited investors, explained the investment terms to those investors, vouched for the merits of the investment opportunity, facilitated the collection of investor funds, and received transaction-based compensation without ever registering as a broker-dealer with the Commission or associating with a registered broker-dealer,” the complaint alleges.
Unlike some syndication models, where investors pick and choose the individual deals they want to invest in, the defendants here told investors that the owner of the funding company would select which deals to fund with their money on his own. Investors were not entitled to know the names of the merchants due to confidentiality. Overall, the funder solicited at least 87 investors, raising at least $47 million, and promised fixed returns of between 22% and 53% on one-year investments and between 9% and 10% on shorter, two- to three-month investments.
The owner, who just pleaded guilty to wire fraud, misappropriated at least $11 million for himself—to pay gambling debts, personal credit card bills, home renovation expenses, and mortgage and car payments. He also used investor funds to pay earlier investors. While he did fund some deals, there were not that many. The scheme was able to go on for five years before collapsing in mid-2023.
The brokers who marketed the investment opportunity received commissions ranging from 5% to 25% of the amounts they brought in. They personally face claims that they violated Section 15(a) of the Exchange Act and should be enjoined.
The SEC complaint describes each of their violations “as a natural person not associated with a broker or dealer which is a person other than a natural person, made use the mails or any means or instrumentality of interstate commerce to effect transactions in, or to induce or attempt to induce the purchase or sale of, any security without being registered with the Commission as a broker-dealer.”
How Scammers Could Defeat Your Time-In-Business Underwriting Requirements
August 5, 2026 The TIB checked out on the application and with the Secretary of State (SOS). The company had been in business for almost exactly five years—comfortably beyond the minimum underwriting guidelines. But its online footprint looked much weaker, almost as if the business had opened yesterday. Maybe it had. Or maybe the business did not actually exist at all, and the validated corporate records were simply part of a sophisticated fraud designed to slip past the gatekeepers.
But if something were really wrong, how could one explain the SOS-verified TIB?
“Ever heard of a Shelf Company?”
That was a question posed by Jamie Parker, CRO and co-founder of Heron Data.
A shelf company, or shelf corporation, is a legal entity that is formed, registered, and then placed “on the shelf” to age. At some point in the future, the entity may be sold, potentially allowing the buyer’s company to appear older than it actually is. Online forums such as Reddit, BiggerPockets, and CreditBoards contain years of discussion on the topic, including strategies, success stories, and failures.
According to Parker, there is a perception online that an older entity can provide a shortcut to obtaining business credit that a party might not otherwise qualify for. Anyone who follows the rabbit hole of shelf-company discussions will inevitably find websites that sell them.
Parker found himself on one such site. It listed the names of entities available for purchase along with their respective ages, and he became curious about what he could do with the information.
“I looked at that and so I went through all the archives, the Wayback Machine, I looked at all of the ones that had been sold in the last, like, five years,” Parker said.
He ran a test, searching Wayback Machine to determine which entities had been sold and whether any had later surfaced in the State courts as a defendant in a lawsuit with an MCA funder. He quickly found one: a business using a shelf entity that had received funding, defaulted, and was being publicly sued for breach of contract by three different funders.
“Time in Business, pretty much everyone has some policies,” Parker said. “The source of truth for Time in Business is considered to be the Secretary of State.”
Parker said that information alone may not be enough, given how freely advice about circumventing company-age requirements is proliferating online. It can be important to go one step further.
“So in the Secretary of State it will give you some information like when the business was formed, when control changed,” Parker said. “If whatever owner changed or the offices changed three months ago, that’s a flag. But you really have to get into the weeds for that.”
That is particularly true when underwriting teams perform every review manually. Parker noted that Heron’s technology can already retrieve that pertinent information as part of its system, however.
“…maybe you compare your Time-In-Business check with when the office has changed, and if the office has changed less than a year ago, that you’re probably not going to auto-decline, but you are going to want to just make sure that there hasn’t been like a significant change in control of the business,” he said.
Shelf companies are not a new phenomenon. In Parker’s view, however, the pace of underwriting in the small-business finance industry is rapidly approaching the speed of consumer lending. As automation begins to replace certain manual processes, seemingly minor tricks employed by applicants could derail the entire model.
For example, the buyer of a shelf corporation could use it to open a bank account and season that account with circular deposits and withdrawals over several months, creating the appearance of legitimate sales and expenses. In that scenario, there is a real legal entity with real bank statements, resulting in a more sophisticated form of fraud.
“You’re making faster and faster offers, you have less time for humans to look at stuff. This is the kind of thing that you’re going to get caught by,” Parker said.
In a social media post about the topic, Parker said, “Compare the transactions with the industry – if it’s a restaurant with only ATM deposits and checks, it merits further investigation. If you see lots of card deposits, that’s more likely to be safe. Look for signs of business activity – Facebook, Yelp, SAFER, whatever you would expect given the industry.”
Parker said Heron can automate those checks as well.
When it comes to company age, most scammers already understand that a corporation that does not exist—or one that was formed the night before—is unlikely to make it past the starting line.
“[Criminals] know funders care about Time In Business, they know funders care about revenue quality or whatever, and gaming that system,” Parker said. “So… you’ve got to be more proactive if you want to kind of keep up, because automation opens the door to more of this fraud.”
Federal Judge: Legal Challenge to California’s Commercial Financing Disclosure Law Has Merit, Orders SBFA Case to Proceed
April 3, 2023 A federal judge has ordered the Small Business Finance Association’s (SBFA) case against Clothilde Hewlett in her capacity as Commissioner of the California Department of Financial Protection & Innovation (DFPI) to proceed. On March 30, The Honorable R. Gary Klausner denied defendant’s motion to dismiss the claims that the State’s commercial financing disclosure law is both unconstitutional and preempted by the federal Truth in Lending Act (TILA).
The case, originally filed on December 2, 2022, argued, broadly speaking:
- That the regulations violate the First Amendment on the premise that they compel the group’s members to make inaccurate disclosures to customers while at the same time prohibiting members from engaging in communications that could be used to clarify or correct the required false or misleading information to customers.
- That APR is defined and governed at the federal level by TILA and that California’s own customized spin on it would only serve to confuse customers.
The Court has now ruled that these claims have been sufficiently alleged, allowing the SBFA the opportunity to prove its case.
Steve Denis, the Executive Director of the SBFA, told deBanked that the win at this juncture was validation for what the organization has been saying for the past few years.
“I think [this victory] is really good news. It’s a lawsuit that the entire industry should be behind,” he said.
The outcome of the case could have far reaching effects. New York, for example, has enacted similarly misleading APR rules that are soon slated to go into effect while other states have contemplated following in its footsteps.
“I think if we win this lawsuit the APR argument is over,” Denis said.
To that end, anyone in the industry that would like further information about what’s taking place can contact Denis at sdenis@sbfassociation.org.
Small Business Group Advocates For Community Anchor Loan Program (CAP) In Wake Of PPP Wind Down and Possible Refresh
April 17, 2020 At last tally, more than 800,000 small business PPP applications have gone unfunded since the program reached its limit, many of which are genuine mom-and-pop shops that employ less than 25 people.
Congress is considering another round of additional PPP funding but Americans may be worrying that such funds will once again go into the hands of some of America’s largest chains. (44.5% of the $349B PPP funds went toward loans over $1 million)
Outspoken successful businessman Mark Cuban has proposed a solution, a lottery system next time around to improve the chances that smaller businesses get their share of the pie. While the public debates the merits of such an approach, one organization (the SBFA) is calling for something much more direct, a targeted fix via a Community Anchor Loan Program (CAP) that would appropriate $10 billion for businesses that were PPP-eligible for loans under $75,000 but did not receive funds.
Deployment of this capital under CAP can and should be administered by non-bank alternative lenders with proven success with this particular small business market, they say.
The proposal also calls for 25% of the funds to specifically be allocated for minority, women, and veteran-owned and agricultural businesses.
In a letter the SBFA submitted to Congress earlier this week, the organization said:
“Women and minority-owned businesses are historically smaller and employ fewer people and, in some communities, are under-banked without the established relationships required to secure a PPP loan. Small farms and agricultural businesses are important to communities and often have trouble qualifying for traditional financing.”
The Small Business Finance Association is a non-profit advocacy organization whose mission “is to take a leadership role in ensuring that small businesses have access to the capital they need to grow and thrive.”
GOING NATIONAL: How David Gilbert Built One of the Largest Small Business Lenders in the Country
October 17, 2018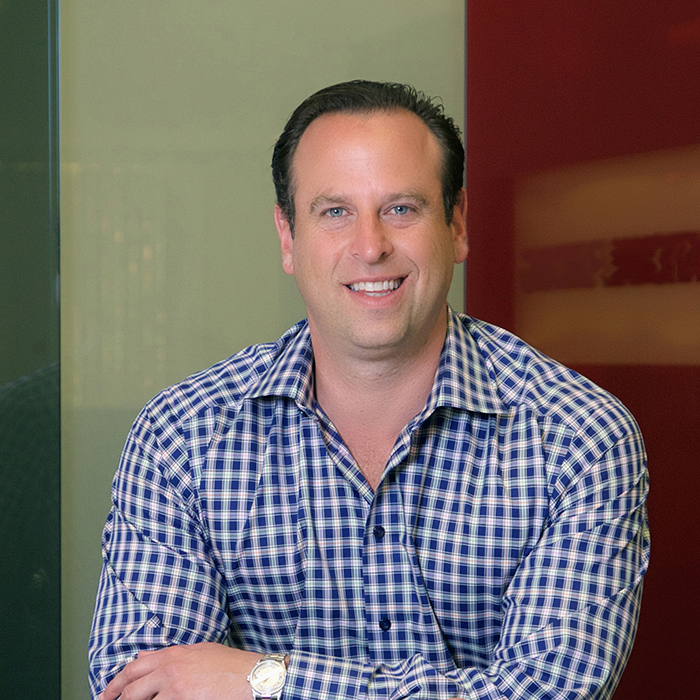 When Ty Austin, who owns a florist shop in West Palm Beach, secured a $5,000 loan from National Funding last year, he was happy to have working capital and could build inventory for mini-gardens and landscaping,
The experience, moreover, was surprisingly pleasant. “The guy I worked with was really cool,” Austin says, referring to the sales representative at the San Diego-based financial technology firm. “It turned out that he was getting married and I ended up giving him and his fiancé advice on floral arrangements.”
The borrowing worked out so well that the Floridian, who is 46 and the sole proprietor of Austintatious Designs, re-upped for a second loan of $12,000 to help purchase a commercial van. The van will be used to transport flowers, plants and tools while doubling as a billboard-on-wheels. “It gives me more ‘street cred,’” he jokes.
To register his approval with National Funding, Austin went online to TrustPilot and posted a rave review of the sales rep: “James Johnson Rocks!”
Pam, a Texas wellness coach who provides clients with an array of holistic health therapies, needed extra money to buy an infrared sauna to add to her portfolio of services. But her credit rating was “poor,” she told deBanked in an e-mail interview, “from when I changed careers and lost my health and struggled to make my credit card and student loan payments on time.”
Like Austin, Pam — who asks to be identified by her first name —found National Funding through an online search. And she too secured $5,000, although her transaction was structured as a merchant cash advance, rather than a loan. The terms of the MCA require a daily debit from her bank account. She reckons that the total cost of the MCA to be roughly $1,500.
 Pam pronounces herself satisfied with the deal and mightily impressed with the way National Funding treated her. The process took about three days — and would have gone even quicker if she’d located her professional licenses sooner. Best of all, she says, the agent at the company tailored the financing to suit her circumstances. “They were great as far as getting my questions answered, even listening to my past situation, which others may not have cared about,” she says.
“They really wanted to get me an option that they knew I’d be able to repay,” Pam adds. “They said they were in the business of helping small businesses grow rather than putting them in a hard financial situation.”
The positive experiences that Austin and Pam had with National Funding are not isolated instances. Rather, they are representative of clients’ dealings with the company. Witness its online reviews from business borrowers at TrustPilot which go back three years, run for 36 pages, and merit National Funding a 9.4 rating on a scale of 10. That’s a straight-A grade on any report card. Although there’s the occasional naysayer — four percent assert that their experience was “poor” or “bad” (and some negative comments can be blistering) — the weight of the reviews is almost embarrassingly positive.
Typical postings find that National Funding and its agents win kudos for, among other things, being “prompt and professional,” providing service that is “hassle free and about as friendly as you can be,” and even being “accommodating and gracious.” A man named Al McCullough spoke for many when he declared: “My experience was great. Professional and on time. Couldn’t ask for more.”
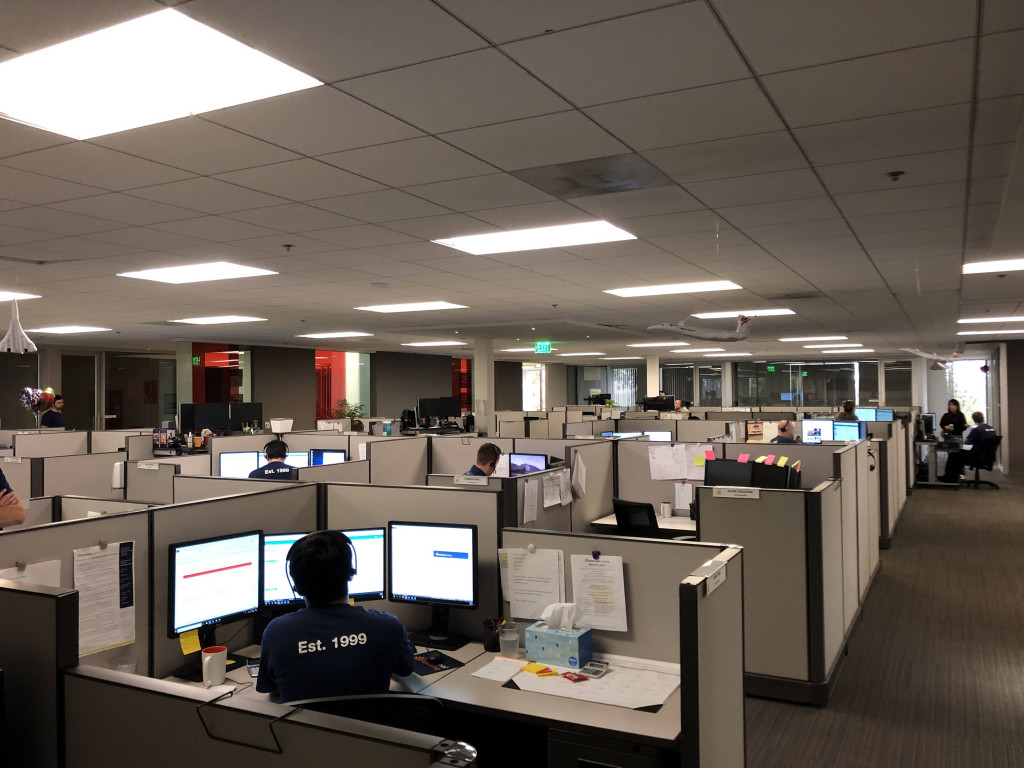 All of which helps account for why National Funding — its 230 employees working out of a sleek suburban office building guarded by a tall stand of palm trees in San Diego — is a rising star in the world of alternative business lending and financial technology. In 2017, the company raked in $94.5 million in revenues, a 24.8 percent bounce over the $75.7 million recorded a year earlier and nearly fourfold the $26.7 million posted in 2013.
In recognition of the company’s three-year growth rate of 142%, Inc. magazine included National Funding in its current list of the country’s 5,000 fastest-growing companies, the lender’s sixth straight appearance on the coveted roster. Since its inception in 1999, National Funding reports that it has originated more than $2 billion in loans to some 35,000 borrowers.
The company’s impressive performance has similarly merited accolades for David Gilbert, the 43-year-old chief executive who started the company on little more than a shoestring and whom employees regularly describe as “visionary.” Among Gilbert’s trophies: Accounting firm Ernst & Young recently presented him with its “Entrepreneur of the Year 2017 Award” for San Diego finance.
At first glance, the San Diego financier doesn’t look too much different from its cohorts. The company proffers unsecured loans of $5,000 to $500,000 to a mélange of small businesses in all 50 states and across multiple industries, including retail stores, auto repair shops, truckers, construction companies, heating-and plumbing contractors, spas and beauty salons, cafes and restaurants, waste management, medical and dental clinics, and insurance agencies.
To qualify for financing, a prospective borrower should have been in business for a year, have at least $100,000 in revenues, and boast a personal credit score of at least 500. While there’s no collateral required for loans, National Funding insists on a personal guarantee. The website reviewer NerdWallet cautions borrowers that this “puts your personal assets and credit at risk if you fail to repay the loan.”
Along with unsecured loans, National Funding offers equipment leasing – usually for heavy trucks and construction equipment – as well as merchant cash advances. The equipment lease is secured by the machinery. As in the case of Pam, the wellness coach cited above, MCAs are debited daily, the money automatically withdrawn from bank accounts.
There are a number of businesses that National Funding disdains, no matter how stellar their credit. “We won’t finance casinos, strip bars, tobacco, or firearms,” Gilbert says. “We’re not going to support industries like that.”
For CEO Gilbert, doing business ethically is a signature feature of the company. Among other things, National Funding presses its salespeople to steer clear of putting people into dodgy loans that are likely to default. “We’re lending capital,” Gilbert says, “and one of our core values is the way we support our customers. Are we placing people with the right product to meet their needs or are we being selfish? The best way to be customer oriented is to get a better understanding of what capital will do for them.”
That corporate ethos, coupled with the company’s remarkable performance, has raised its profile while earning it a measure of esteem among industry peers. “What I do know about National Funding,” says Douglas Rovello, senior managing partner at Fund Simple, a lender and broker in the Tampa area, “is that they have five or six different programs and set their rates high but competitively. They’re known for fitting their products to a client’s needs,” he adds. “And in a business that has its share of bad actors, they have a reputation as a company with a conscience.”
A company with a conscience. Customers come first. And yet National Funding turns heads with its sales production of roughly 1,000 financings a month and triple-digit growth rate. So how do they it? A good place to start is with Gilbert, whose leadership skills, business acumen, and second-to-none work ethic “set the tone,” says Kevin Bryla, the company’s 52-year-old chief marketing officer.
For his part, Gilbert credits his family background and an upbringing in which education and academic achievement were strongly encouraged. The fifth of six children, he’s the only one who opted for a business career. “There are three doctors, two lawyers – and me,” Gilbert says.
 The son of a prominent physician, his mother a homemaker and volunteer docent at the nearby Nixon Library for the past 25 years, Gilbert grew up in Yorba Linda. He attributes his keen interest in business to observing how his father, a pathologist, operated his own laboratory, which employed 60 people. “It was the business side of medicine that fascinated me,” he asserts.
Even so, his two closest friends at the University of Southern California — fraternity brothers Marc Newburger and Sean Swerdlow– tell a somewhat different story. They remember Gilbert as someone who found his true calling, his métier, during his college years. Enrolled initially in pre-med courses, he was a diligent student but, his friends assert, manifestly unsuited for a career in medicine.
“Formative,” says Swerdlow, the older of the two fraternity brothers and now a management consultant based in Southern California, “would be a very good word” to characterize that period during which Gilbert abandoned medicine in favor of the world of commerce. In 1997, he earned a bachelor’s degree in business administration “with an emphasis in entrepreneurship.”
But it was fraternity life just as much as the classroom, his friends agree, that shaped him and foreshadowed his future. “It wasn’t ‘Animal House,’” Swerdlow says of Alpha Epsilon Pi. “We boasted the highest GPA (grade point average) on fraternity row.”
Nonetheless, Gilbert took to the social life and camaraderie that the fraternity offered with gusto, and his friendship with the colorful Newburger was especially fateful. A freewheeling entrepreneur today, Newburger takes a measure of credit — Gilbert’s disapproving parents might have preferred the word “blame” — for contributing to his fraternity brother’s metamorphosis. “Dave hated all of his pre-med classes,” Newburger insists. “He had zero stomach for it. He was so much like I was: a natural people person and a born entrepreneur.”
Newburger is the quintessential soldier of fortune. After college, he tried his hand as an actor, supporting himself by playing poker and getting paid to be a contestant on TV game shows including “The Dating Game,” “Card Sharks,” and “3’s A Crowd.” He’s now the co-president and co-inventor of Drop Stop, a patented device that “minds the gap” between a car’s front seat and the console and prevents coins, keys, glasses, and mobile phones from disappearing down that rabbit hole. (Drop Stop really took off after Newburger and his business partner appeared on the television show “Shark Tank” and scored a $300,000 capital injection from celebrity-investor Lori Greiner who took a 30% stake in the company and slapped her name on the brand.)
Back at the frat house, Newburger and Gilbert collaborated on business ventures. The pair once sold T-shirts sporting an off-color message about USC’s archrival, the University of California at Los Angeles. “The (anti-UCLA) message was pure hatred,” Newburger recalls. “But it was just for the day of the football game and it was all in fun.”
At first, sales at the stadium were lackluster. USC students kept trying to bid down the price or importune them to throw in an extra tee. As for the game itself, USC’s chances for victory looked equally unpromising. As time ran out, however, the Trojan quarterback completed a Hail Mary pass and USC won. The two fraternity brothers grabbed the bundle of shirts and sprang into action. “We got to the exit just in time and sold out in a matter of seconds,” Newburger recalls.
Newburger takes credit too for introducing his friend to Las Vegas’ gaming tables. Gilbert, his friend says, immediately demonstrated a knack for counting cards, handling money, and taking risks. “It was typically blackjack,” recalls Swerdlow, who sometimes accompanied them. “We didn’t have much money then. But there were moments when Dave would bet a big pile of chips. He’s willing to make a bet and live with the consequences.”
Sports are another of Gilbert’s enthusiasms. His friends say that, whether he’s returning serve at ping pong or standing over a putt — he plays to an 11 handicap at golf – he wants to win. Remarks Newburger: “He’s competitive to the point that — when he beats you — he wants the Goodyear blimp flying overhead to announce his victory.”
Gilbert, who is married with two children, is legendarily loyal to friends and family. While most members of a college fraternity might keep up with old companions after graduation by exchanging greeting cards and attending college reunions, Gilbert goes the extra mile.
 He once footed the bill for Swerdlow to travel with the USC football team to an away game, arranging it so that his fraternity brother could view the action from field-level. After Newburger had a recent health scare (no worries, he’s O.K.), Gilbert rounded up a couple of dozen fraternity brothers and their wives (or companions), and put together a four-day bash in his buddy’s honor. The event was held at Cabo, the Mexican beach resort in Baja California, and Gilbert underwrote a fair amount of the cost. “He shares his success with his friends,” Newburger says, adding: “I don’t know anybody who works harder on friendships.”
Many of the personality traits described by friends and colleagues — tenacity and competitiveness, self confidence and leadership — played a key role in the development and success of National Funding, which Gilbert founded just two years out of college with $10,000 borrowed from his uncle, Howard Kaiman, of Omaha.
He’d worked a couple of quick jobs right after college, including a stint at small-business lender Balboa Capital, but he was always destined to be his own boss. Gilbert’s start-up was called Five Point Capital and, at first, it was located in the affluent Chatsworth section of Los Angeles and concentrated on equipment leasing.
“The first two years we were a cold-calling company and then we got into direct mail and saw some success and then we moved to San Diego and started to scale up the company,” Gilbert says. The decampment, he explains, was “for the quality of life, but we also felt we could hire from a better talent pool than L.A. We wanted to set ourselves apart.”
By 2007, Five Point was cranking up operations, revenues shot to $28 million and its headcount totaled 210 employees. “Then the Great Recession hit” in 2008-2009, Gilbert says. The company was forced to furlough 140 employees, two-thirds of its workforce. Yet even as it retrenched, the company managed to branch out. It began making merchant cash advances, Gilbert says, and, also in 2007, it linked up with CAN Capital to do broker financings. “We were pretty well known and they were looking for partners for factoring and leasing,” Gilbert explains.
It took time to recover after the financial crisis. But by 2013 – the year that Gilbert re-branded his company “National Funding” – the company was able to hire back as many as 15% of its laid-off employees (most had found other jobs, in many cases relocating to Silicon Valley, Gilbert reports). By then, the company had secured a $25 million credit facility from Wells Fargo Bank, which allowed it to move up the food chain to “become a balance-sheet lender,” Gilbert says, and offer a wider selection of financing options.
Key to driving the company’s phenomenal growth has been its flood-the-zone marketing and sales strategies. The company spends $16 million annually on marketing using a full panoply of channels and media, both online and offline. These include direct mail and targeted marketing, paid advertising, search-engine optimization or SEO, and sports sponsorships. “We try to build a whole range of marketing mechanisms,” explains marketing chief Bryla, “and when you get the mix right, they all help each other.”
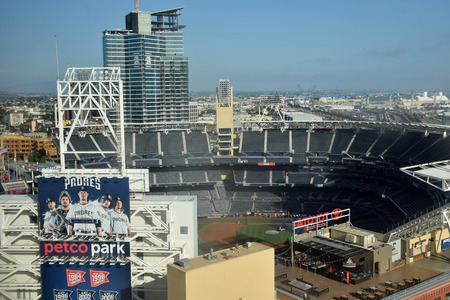 Gilbert is a big believer in the benefits of sports marketing, the company’s website featuring the logos of the San Diego Padres (baseball), and Anaheim Ducks and Los Angeles Kings (hockey). Ever the faithful alumnus, Gilbert and his company back USC football as well. During the 2015 2016 college football season, the company paid for naming rights for what became, for one night, the “National Funding Holiday Bowl” at Qualcomm Stadium.
Janet Fink, department chair at the McCormack School of Sports Management located at the University of Massachusetts-Amherst, told deBanked that sponsorship programs can easily cost a million dollars or more. “It’s not cheap,” she says. “When a company sponsors a team, they get a number of benefits. One is that they get to put the team’s logo on their website. The idea is that fans are passionate or have an affinity for the team and that it will rub off on a sponsor.
“Sports enthusiasts,” Fink adds, “often make good customers. When you have enough disposable income to go to these sporting events, you’re probably a good prospect for a loan.”
The sponsorships — which include civic involvement such as offering Holiday Bowl tickets to members of San Diego’s large military contingent as well as to company employees — also build good will in the community and team spirit among the workforce. (National Funding also makes an effort to hire veterans, says Bryla.)
Gilbert believes in the old adage that you have to spend money to make money. The company spends $14 million rewarding its network of outside brokers. Inside the company, high-performing salespeople are compensated with commissions, bonuses and an assortment of rewards, including resort trips.
But sales representatives’ must conform to company guidelines. Justin Thompson, National Funding’s sales chief, explains that the “customer comes first” philosophy is not just a slogan but a core value. “We’re not a factory spitting out widgets,” Thompson says. “We’re here to build relationships and sell a repeatable product. We want that customer to come back to us. Every loan is customized. Six of ten customers who pay off their loans come back for a second financing. Whether your business is dog grooming or you’re an asphalt company,” he adds, “people will do business with people they like and trust.”
Using the software program “customer relationship management” (CRM), National Funding expends a lot of effort gathering data on its business customers and extrapolating the information for use in credit evaluations. But the use of technology only goes so far.
 Gilbert reckons that the art of the deal involves about “70 percent algorithm and 30 percent people.” He adds, “You still need the people component to look at credit profiles. The algorithm spits out a recommendation but we still need the human element.”
If there’s a fly in the National Funding ointment, it’s that the company’s fees can be more expensive than a bank loan.
But borrowers who have been denied loans at a bank or other lender are likely to overlook those costs. Austin, the florist in West Palm Beach, for example, came to National Funding when his bank, North Carolina-based BB&T Bank, gave him the cold shoulder despite the $15,000 in deposits that he averages each month. “I’ve been with them for six years,” he fretted, “and they treated me shabbily.”
Even more grateful was Jimmy Frisco, of Annapolis, who is co-owner with his wife of Lisa’s Luncheonette, a business that includes a food trailer and several cafeterias located in the city’s office buildings. They employ about a dozen people.
Frisco had taken a nasty spill and was laid up for seven months. Health insurance covered the $18,000 in medical costs but he and Lisa fell behind in their bills and needed working capital to pay for food purchases and other business expenses. By the time a flyer from National Funding popped up in his mailbox, he and his wife “had been turned down by several other lenders, including banks,” he says, adding: “Things happen in life and we don’t have the best of credit.”
Getting that loan for $25,000 from National Funding took just three days. Frisco’s health is much improved and business is back to normal. He won’t discuss the terms of the financing, other than to say “it was reasonable.”
He adds: “There were no problems with National Funding, no hassle with the paperwork. They’re great people to work with.”
Déjà Vu: Some Small Business Funders are Fading Away
June 20, 2017 Apparently I’m old enough to see this happening all over again. A handful of big names in the alternative small business space are faltering and many of you have asked what this means for the industry. It really doesn’t mean anything other than those who do not learn history are doomed to repeat it.
We already went through this in 2008-2009 when at least half of the funders in the merchant cash advance industry were wiped out over the course of several months. Merit Capital Advance, Fast Capital, First Funds, Summit, and Global Swift Funding were the Goliaths of their time. Those companies going out of business seemed unthinkable in principle and for what that would mean for the industry as a whole. Smaller players disappeared too, names like iFunds, Infinicap, and others for those of you who might remember.
Those companies failed. The industry continued.
While it’s easy to finger the financial crisis as the culprit for their demise, the truth, or at least the truth through the fog of war and days gone by, is a lot more relatable. Funders were undone by their dependence on a single source of capital, sloppy underwriting, defaults, rogue ISOs, a race to hit origination targets, overpaying commissions, misplaced predictions, and even stacking. If any of those things remind you of what’s happening today, well then of course there are companies failing.
One lesson from the past is that you won’t necessarily get a year or two to adjust and figure things out. It will seem like everything is great and then suddenly it’s not. No company is going to sit you down and tell you their 1-2 year going-out-of-business plan to prepare you for change. They probably don’t have any such plan, will fight to avoid it and their end may be just as much a shock to themselves as it is to everyone else.
What we’re learning again this time is that some business models just won’t pan out long term. And some business models that used to work no longer work so much today. Things like stacking are not going away. It’s not illegal and no legal precedent has been established against it. If you’re an ISO though, you may be risking a relationship or breaching your own ISO contract by helping a merchant engage in it. So it’s a slippery slope but one that has permanently disrupted the landscape.
I have heard a lot of complaints from ISOs about the supposed decay of funder loyalty, as in they feel their deals are getting swiped. Another lesson from 2008 is that in times of strain, parties are more likely to look to their contracts for guidance and if the contract says they can take your deal after a certain amount of time and they very much financially need to, they probably will do it. The whole hey, we’re friends, we wouldn’t do that kind of thing goes out the window if survival is at stake and the contract allows for certain actions. That also means that if you’re an ISO who has violated an ISO agreement before and got nothing but a shrug in the past, don’t be surprised if suddenly one day you’re put on notice of a breach and are forced to reckon with the consequences of it.
What failures in the industry may also mean is a return to a semblance of order, a return to a code. 2010-2011 was a refreshing time to be in the business with so much unhealthy competition out of the way even though approval terms were less flexible and there were fewer options to shop around for. By 2013 however, a flood of participants discovering the industry for the first time, believed that they had stumbled upon something brand new and lost were the lessons of yore. Some of them introduced lasting change, like ACH debits over merchant accounts splits. Others just replicated the cavalier tactics that had proved fatal in the previous generation, distorting a happy market equilibrium in the process.
Ultimately, the market will prevail, albeit with some new names and new faces at the top. This is the way of things. It has happened before. It will happen again. Look at the companies rising rather than those that are falling. Whatever they are doing may be the future, whether you agree with how they do business or not.
Some Small Business Funders Are Pivoting or Closing Shop
October 20, 2015 One of the unique insights deBanked gets as a company that sends a lot of email and snail mail to folks in the industry is the rejection rate. One day an entrepreneur is telling us all about their new lending business and the next day the Post Office returns their magazine for a vacant address. Sometimes there’s a change in the model or a partnership didn’t work out. Other times lead generation became too hard or too many merchants defaulted very early on. The truth is, as much as the industry is growing, some companies are pivoting or closing their doors.
At Lend360, there were whispers around the trade show floor that acquisition costs have spiked and it was being felt on the bottom lines. Broker houses are opening, closing, merging with each other and being acquired. Funders have reacted by giving them lines of credit to either help them grow or stay afloat, hoping that their sources of deal flow don’t fall apart.
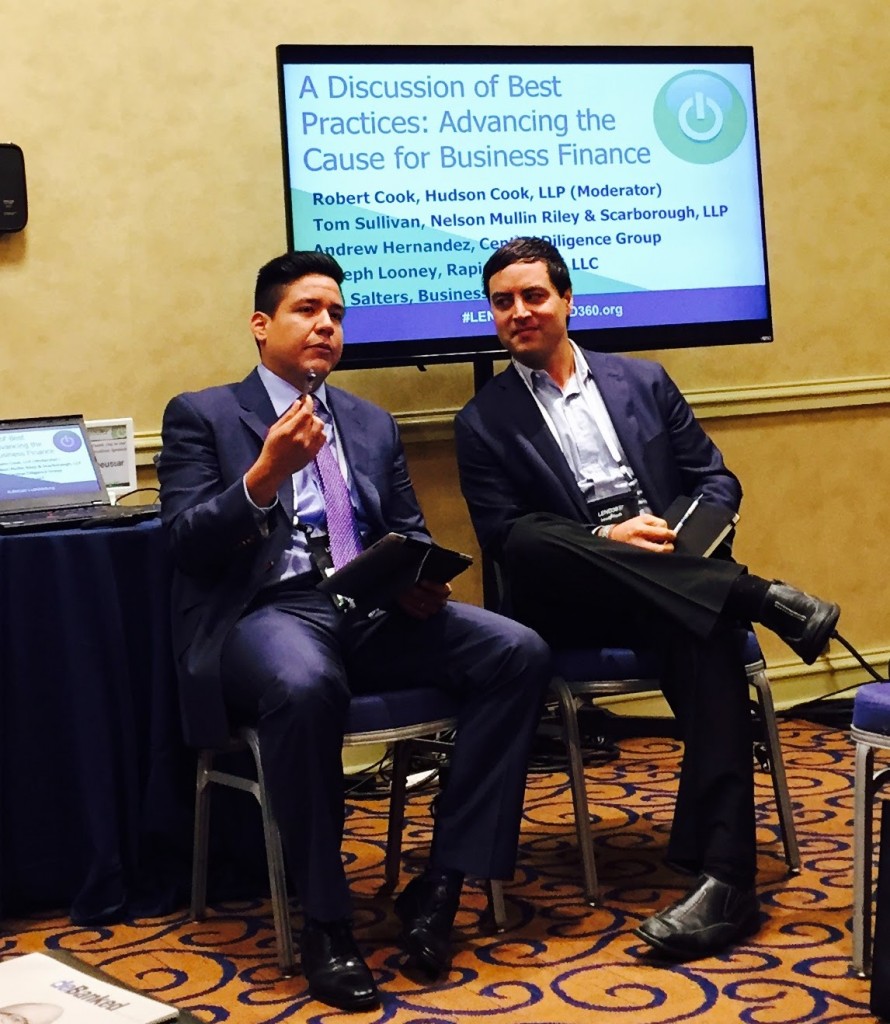
On one conference panel titled, A Discussion of Best Practices: Advancing The Cause for Business Finance, veteran underwriter and industry consultant Andrew Hernandez of Central Diligence Group, said he’s watched a lot of new entrants in this industry make mistakes. “We’ve seen guys lose their shirt,” he said. He explained that too often small business funding companies look to cut their acquisition costs in the wrong places, like simply paying less for leads or paying brokers lower commissions. That only works to a point. “Underwriters can help keep the cost of acquisition down by funding the right deals and trying to get good deals done,” he said.
The owner of one funder summed up his dilemma for me, my brokers are making more on a deal than I am and I’m the one taking all the liability on it. Maybe I should become a broker instead. Not that there would be anything wrong with that. For some companies in this industry, the best path forward is achieved through trial and error. For example, World Business Lenders’ Alex Gemici said at the conference that they started off by making unsecured loans and now only do loans secured by real estate. Gemici also said he believes the industry is heading for a major shakeout within the next three years and that irrational exuberance keeps him up at night.
If he’s right, an economic downturn could squeeze out a lot of players that are already feeling the pinch of high acquisition costs.
For those newer to the industry, they might not remember that the effects of the 2008-2009 financial crisis and ensuing recession was brutal. More than half of the providers of merchant cash advances went out of business, some within weeks when their credit lines were pulled.
A lot of the “industry leaders” of 2008 aren’t around anymore: First Funds, Fast Capital, Second Source, Merit Capital, iFunds, Summit, Infinicap, Global Swift Funding, and more.
Given the favorable economic climate and regulatory environment, this is a bad time to be struggling. 2015 may be one of the last years to pivot in a major way before it’s too late.
Funding Floodgates Reopen
September 20, 2011If you’re a business owner, it’s time to get ’em while they’re ~HOT! Small business funding is BACK and more available than they’ve been in years. And guess what? Because we’re just a news site, we’ve got no reason to douse you with a cheesy sales pitch. There’s a lot of money out there right now and that’s the truth.
Merchant Cash Advance (MCA) continues to dominate the alternative financing market but a few new options are changing the landscape. You might call them ‘alternatives to the alternatives’, deals that are based on MCA but have all the bells and whistles of a loan; Fixed time frame, a payment schedule, and even personal guarantees! The underwriting criteria generally requires a set of recent healthy bank statements and semi decent credit credit (yes, your credit still matters) to qualify. Beyond that, it’s up to the individual lender to present their respective checklist of closing documentation. This usually includes some combination of a business property lease, applicant ID card, business permit, and a recent tax return. That’s it. Oh, and the wait time? Expect a week long process if you’re quick on the draw with paperwork.
Two years ago, there wasn’t much variety in the MCA space. Business owners could shop all they wanted but the underwriting and cost structures were essentially identical everywhere. Now there are factor rates that range from from 1.20 to 1.65. It’s more merit based than it used to be. The higher credit rating, stronger cash flow businesses can earn something better than the one-size-fits-all 1.35 factor rate of yesterday. On the same token, the complete credit averse can grab a shot at financing too, but at a steep price.
But there’s more to it than just cost, there’s also the setup:
Don’t want to switch your merchant account?
Stay where you are: There’s a significant chance your merchant processor already has a contract with the MCA provider you’ve chosen. Often times your sales representative may encourage you to open a new merchant account for the lower discount fees and to have a higher degree of control if problems arise. Ultimately, a new merchant account is not essential if you want a MCA.
Leverage your strong cash flow history: If you’ve managed to keep a large positive balance in your bank account for the last few months, your MCA provider could simply extract the agreed percentage from there, rather than directly through the merchant account.
Lock it up: A Lockbox provides the MCA provider with peace of mind by obtaining their payments without the risk of Non-Sufficient Funds from the debit method but also allows you to keep your merchant account. It’s frequently used as a compromise for businesses that are legally prevented from changing their merchant account(i.e. franchisees), but are too cash flow weak to qualify for direct debit payments.
But the buck doesn’t stop at the many ways you can do MCA. You’ve got options!
Merchant Loan: An actual loan based on your credit card sales history. A percentage may still be withheld from each card sale but a periodic or an end-of-term lump sum payment will be applied as needed to ensure the loan is completed within the time frame allotted.
E-Bay/Amazon Loan: Get a loan based on your sales history on Ebay.com or Amazon.com. The largest lender of this type is Kabbage.
Cash flow loans: We described these in the 2nd paragraph. Expect cost ratios from 1.12 to 1.55 and term lengths between 4 and 24 months.
How can you find the floodgates?
You can refer to the directory of direct MCA providers but can check out alternative lenders such On Deck Capital, ForwardLine, Kabbage, and Sure Payment Solutions if you want to diversify your options.
Kennesaw based funding provider, AdvanceMe expects to fund $1 Billion in the next two years. That’s nearly as much as the entire MCA industry did in the last two years combined.
2009 was a year full of “I should’ves” as in “I should’ve obtained financing before the financial crisis.” Cash is finally available to small businesses again and although it is more expensive than it used to be at the local bank, there may never be a time where the process is this quick, approval is this easy, or where your credit score is weighted this lightly. We’re not the salesman here, just the messenger. If there was any project you were remotely considering, now is the time to make a move… Don’t wait until the funding levees have been restored.
– deBanked
https://debanked.com