Stories
The Next Frontier: Financing the ERC
January 11, 2023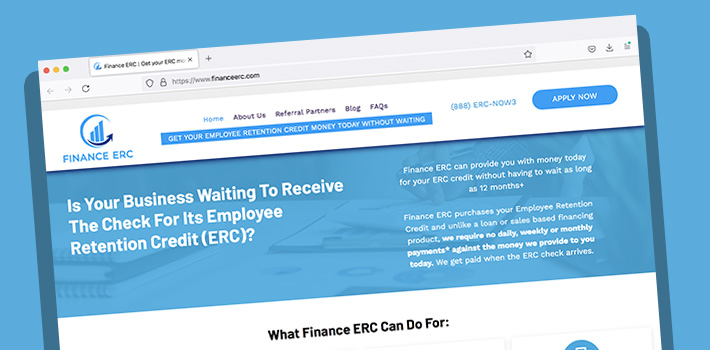 “I have never sold a product that has no daily, no weekly, or no monthly payments,” said David Goldin. That is until now, he explained, because of the Employee Retention Credit from the IRS that’s sweeping the country. Goldin’s new company, Finance ERC, that he co-founded with Newtek co-founder Jeffrey Rubin, is buying the future ERC receivables of small businesses that have filed for it. A key feature? No payments.
“You basically drop off the money, they don’t pay you out of cash flow, we get paid when the checks arrive,” Goldin said. “It’s an amazing offering.”
Goldin is no stranger to the SMB finance game. He is one of the reasons that the MCA product exists today in the United States. A documentary about it was the second most watched in all of 2022, for example. And he’s still a busy guy. One of his other businesses, Capify, finances small businesses on two continents every day.
“I’m busy in the morning with the UK and I’m busy at night with Australia, but I had a lot of free time during the day,” he said about how he was able to pursue yet another venture. “I approached Jeff and we were seeing that there was a gap in the market that the checks don’t arrive.”
The ERC, a potentially generous tax credit available to eligible businesses, has recently enjoyed greater awareness since it was included in the March 2020 CARES Act. Businesses that qualify can amend previous returns to receive a refund. Folks in the small business finance industry, already in direct communication with businesses about their financial needs, have taken notice.
Finance ERC won’t do the filing itself for a business. They have to had filed already to seek out the funding, which can go up to $1 million at present. It’s the waiting game between filing and actually receiving the refund that leaves merchants in a crunch. Goldin said the wait time is “best case scenario three months, worst case scenario a year plus.” And there’s no guarantee that the claims will be paid. That’s a risk they bear.
The deals come in from a variety of sources, business loan brokers, MCA platforms, ERC filing companies and more. The funding amounts can be significantly larger than an MCA and with no payments to be made, is incredibly competitive. A number of other financial service providers are charging a fee just for helping the businesses file for the credit in the first place, which in itself can be lucrative, but Finance ERC sticks just to the funding.
“We work with the funding companies, we work with the brokers, the various ISOs, it’s a great product,” Goldin said.
But the life span of the ERC is purportedly capped. Some experts say that businesses can only amend their 2020 tax return through April 2024 and their 2021 return through April 2025 [dyor]. But then that’s supposed to be it, allegedly.
“That presumes the government is not going to offer any future tax incentives,” Goldin said. “What we’re building at Finance ERC is a platform to finance tax credits. [The ERC] is the first credit.”
The opportunity, he explained, is preparing now for what may repeat often in the future.
“We put together the right players and vendors,” Goldin said. “We’ve hired a super senior management team.” It’s a system that includes sales, marketing, operations, finance, underwriting and more, to be prepared to scale.
But even in the present, opportunity abounds.
“The best estimates I’ve read are 5-6 million ERC are still eligible,” Goldin said. “People in this industry call it America’s best kept secret.”
And thus as marketing of the ERC continues to grow all around, Finance ERC is ready to work with businesses, brokers, and filers going through the process. Businesses can even use the funding from Finance ERC to pay the fee to file in the first place.
“So now all of a sudden they put the risk to me which I’m happy to do for a file that we like, and I pay the filing company / the broker gets paid right away,” Goldin said.
Strategic Funding Secures $12 Million Equity Round and $15 Million Senior Credit Facility
June 27, 2012For Release on MPR / New York (June 26, 2012) – New York City based Strategic Funding (www.sfscapital.com) has announced it has completed a $12 million equity round with an investor group led by Three Layer Capital of Los Angeles, California and simultaneously closed on a new $15 million revolving Senior Credit Facility with Capital One Bank. The new equity and credit facility will be used for ongoing capital needs and to fund the future growth of company.
Strategic Funding is recognized as one of the most innovative companies in the alternative finance industry, providing unique working capital solutions such as merchant cash advance, revenue based factoring (ACH programs) and commercial loans for small businesses. The company’s business model combines sophisticated underwriting incorporating qualitative and quantitative risk analysis with the most advanced enterprise technology available.
“Strategic Funding finances the small to mid-sized businesses of Main Street America” said Andrew Reiser, Chairman and CEO of Strategic Funding. “Since 2006, we have provided thousands of small businesses with the working capital they need to grow and sustain themselves through challenging times. Today’s entrepreneurs have very limited access to bank financing, a void filled by our company and the alternative finance industry – so one might say that we are stimulating the economy, one small business at a time.”
In seeking high yield investment opportunities, Thomas Scoville, a partner at Three Layer Capital stated that, “We were looking for best-of-breed players in the alternative finance space. A lot of companies are currently operating in this arena but few have the disciplines and technology of Strategic. A number of these companies are also beginning to venture into big-data risk analytics, but Strategic has been quietly doing this for years – they’ve got a big head start.” Dan Scholefield, partner in Three Layer Capital added, “Their business model demonstrates remarkably high yields and low default rates while providing financing to traditionally under-banked entrepreneurs. Strategic is very responsive to the needs of the market and economic conditions and provided an outstanding investment opportunity.”
Reiser continued, “We pride ourselves on integrity and responsiveness to the ever changing market and are pleased to welcome our new investors at Three Layer Capital and the team at Capital One Bank.
The Capital One Bank Senior Credit facility replaces the facility provided by Paul Frontier Holdings, which has been a shareholder in Strategic since 2007. Rahul Vaid a managing director of Frontier Capital Advisors, which manages the Paul Frontier Holdings portfolio. He will remain a member of the Board of Directors and his firm will continue their support as a major shareholder of Strategic.
About Strategic Funding
Strategic Funding ( www.sfscapital.com ) is a leading provider of specialty financing to small businesses throughout the United States. Strategic is recognized as the technology leader in servicing the factoring and loan transactions of thousands of merchant accounts for themselves and over one hundred funding partners. The Strategic enterprise technology is at the backbone of the “Strategic Partner” program which promotes syndication among numerous cash advance companies and private investors. Established in 2006, Strategic has its headquarters in New York City and maintains regional offices in Williamsburg, Virginia; Chicago, Illinois and Seattle, Washington, serving thousands of active small business clients in all 50 states.
About Capital One
Capital One Financial Corporation ( www.capitalone.com ) is a financial holding company whose subsidiaries, which include Capital One, N.A., Capital One Bank (USA), N. A., and ING Bank, fsb, had $216.5 billion in deposits and $294.5 billion in total assets outstanding as of March 31, 2012. Headquartered in McLean, Virginia, Capital One and ING Direct offer a broad spectrum of financial products and services to consumers, small businesses and commercial clients through a variety of channels. Capital One, N.A. has approximately 1,000 branch locations primarily in New York, New Jersey, Texas, Louisiana, Maryland, Virginia and the District of Columbia. A Fortune 500 company, Capital One trades on the New York Stock Exchange under the symbol “COF” and is included in the S&P 100 index.
About Three Layer Capital
Three Layer Capital ( www.threelayercapital.com ) is a privately held multidisciplinary fund with focused interests in biotechnology, energy and alternative finance, located in Los Angeles, California.
Contact:
David C. Sederholt, Chief Operating Officer
Strategic Funding
Phone: 212-354-1400
DSederholt@sfscapital.com
A Journey Through Collections With Erica Gilerman
September 8, 2026“Within two weeks, I closed my first deal. I just clicked in the industry,” said Erica Gilerman.
Gilerman wasn’t talking about funding a deal. She was talking about collecting on one.
“Closing the deal on our end means that we have a signed, sealed, and delivered stipulation, one that our client is happy with, and one that truly makes sense financially for the merchant as well,” she said.
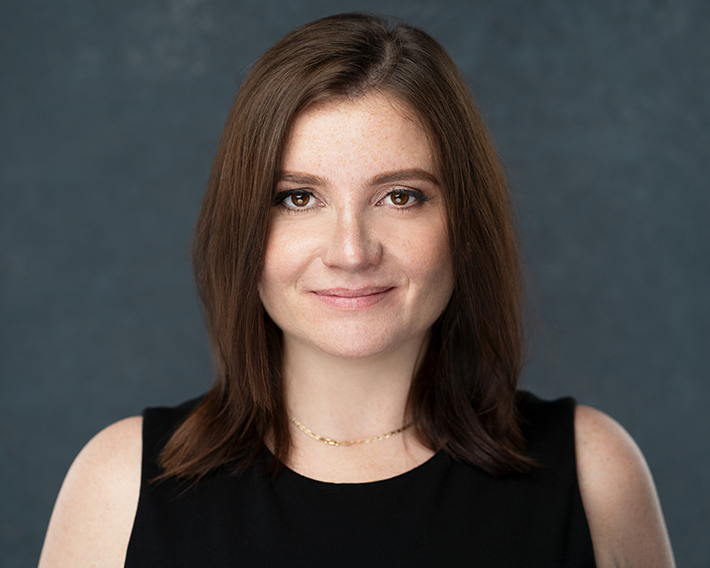
Conventional wisdom in the small business finance industry has long held that anyone can put money out the door; getting it back is the hard part. Gilerman currently serves as Chief Legal Officer of that hard part, working for Triton Recovery Group in South Florida.
Talk to anyone at Triton and they’ll probably tell you that successful collection begins during the underwriting process, before a deal is ever funded in the first place. In a taped interview deBanked conducted with Triton CEO Leo Vargas in 2024, he said, “The underwriting process to me is the most important piece of getting a deal done in the industry.” Vargas offered examples, saying that it’s critical to know from the outset what merchants plan to use the funds for and that the terms of any deal should be set in accordance with a merchant’s anticipated receivables, not deposits.
Today, Triton has 75 employees. But when Gilerman was being recruited to work there in 2021, the company had only six. Vargas was looking to add an attorney to his then-fledgling traditional commercial collections firm, which was focused entirely on the merchant cash advance industry, and he posted an ad in the New York City market.
“I will never forget… it was very interesting to me because it was in all caps and it said ‘COLLECTIONS ATTORNEY, NEW YORK,'” said Gilerman.
She answered the ad, met Vargas in New York, and received an offer. There was just one catch: She had to spend a month training at Triton’s Miami office to learn its particular niche of collections. That required a significant sacrifice, time away from her family, but she decided to take a chance and then determine whether the job was right for her. She started in July 2021 as the firm’s General Counsel.
“Within two weeks, I closed my first deal. I just clicked in the industry,” she said. “Between my accounting background—I understand how the factor rates work, I understand how businesses operate, I take a very unique approach to everything in the sense that I will collect in a way where I put myself in the debtor’s shoes.”
Gilerman, the daughter of immigrants, was born in Brooklyn, New York, and she attended Madison High School in Brooklyn. She was accepted into the school’s law program, which had been created by former Supreme Court Justice Ruth Bader Ginsburg. Ginsburg, herself a Madison graduate, had created the curriculum.
“My love for law really kind of came to play there, and I learned a lot from that program,” Gilerman said, “and that’s why I’m very proud to say I’m a New York City public school graduate, and that’s how I fell into law.”
Gilerman faced a personal family tragedy as she began college at Pace University, around the same time Lehman Brothers collapsed. Pace’s campus in Downtown Manhattan had a front-row seat to the turmoil unfolding across the financial system.
“I will never forget that in that moment I realized I need to find a career that will not keep me into some sort of niche, because 25 years from now I could be one of those people that was carrying boxes,” Gilerman said, “and they had nowhere to go and nothing to do, and it was a very eerie dynamic being on Wall Street at the time.”
Gilerman initially intended to pursue a career in public accounting as a result but ultimately swerved back toward law. After becoming an attorney, she worked in employment litigation before moving on to collecting medical debt for hospitals in New Jersey.
“You have to have a specific type of personality to be in collections, especially as a woman,” she said. “I would candidly say I would never expect myself to be in collections. That was not my goal in law school, but I would not change it for the world now. This is exactly the niche industry I need to be in.”
Part of that certainty came from finding the right person to work with.
“I will say that I learned most of the MCA space, especially on the front end side, from Leo. He taught me the collections mindset for commercial collections, and we just clicked in a way that it was just a great synergy from the beginning.”
Triton was still quite small at the time. When Gilerman visited the company’s original Miami office, they had to set her up in the break room. By the end of 2021, however, the COVID lockdowns were finally beginning to dissipate nationwide, and the company hit the gas pedal by sponsoring a conference that December in New York: Broker Fair.
“We were able to expand and start hiring more after the very first deBanked [conference] that I attended, which was December of 2021,” Gilerman said.
By then, her mind was fully made up. She and her family moved to Miami two weeks after the conference. Five years and nearly 70 additional employees later, spread across two states (Florida and Texas), she has since become the company’s Chief Legal Officer.
In those early days, Gilerman was still trying to wrap her mind around the financial product Triton’s clients worked with. She said she came to really understand “that without the MCA industry, there is no such thing as a mom and pop shop anywhere in this country and it really changed my perspective of what alternative finance as a whole is.”
Triton’s collection practice handles MCA, commercial loans, and equipment financing on a contingency basis. Ask the team a question about underwriting and they’ll readily offer an opinion. They’re only interested in legally enforceable paper.
The latest frontier in collections includes dealing with merchants who have turned to LLMs to fire off letters, emails, and demands, often containing incorrect information or citations to the wrong statutes. It has become commonplace to see merchants effectively act as their own attorneys with the help of AI, or even claim that AI is representing them.
“I see a lot from ChatGPT and Claude there, and the problem is that they continue to just say the same thing over and over,” she said. “You could tell by the tone because no one’s actually telling them to make it sound like themselves.”
Even on phone calls, merchants may attempt to bring AI agents onto the line with them.
On the flip side, collectors can use AI too. In a recent social media post, Triton CEO Leo Vargas said, “The best agencies will use AI to eliminate repetitive tasks, improve compliance, analyze consumer behavior, optimize account placement and provide collectors with better insights before they ever pick up the phone. Collections has always been about people. AI simply gives those people better tools to succeed.”
Vargas also referenced Gilerman in an email to deBanked. “Five years ago, [Gilerman] took a chance on Triton and joined us during an important stage of our growth,” he said. “Since then, she has grown alongside the company and worked her way to becoming our Chief Legal Officer and a key member of our executive leadership team.”
“Collections, especially the MCA space, this is us playing chess,” Gilerman asserted. “And for us, a checkmate is getting that payment through the door, making our client happy, allowing our client to then redeploy those funds.”
Heron Raises $16M Series A to Bring the AI Revolution from Silicon Valley to American Businesses
July 15, 2025Backed by Insight Partners, Heron automates document-heavy workflows in insurance, lending, and finance — bringing reliable AI to businesses and allowing humans to focus on complex tasks
Heron, a startup using AI to automate workflows in business lending, equipment finance, and insurance, has raised $16 million in Series A funding led by global software investor Insight Partners, with participation from existing investors Y-Combinator, BoxGroup and Flex Capital. The Series A will support Heron’s next phase of expansion, helping the company scale its AI-driven solutions to more segments.
While many AI startups target developers or other technologists, Heron is at the frontier of deploying AI into real-life business operations in traditional industries like lending, banking, and insurance. Heron’s mission is to free up humans to focus on judgment-based work and complex edge cases while software handles the repetitive, monotonous work. Heron focuses on serving companies without large engineering departments, enabling more businesses to reap the rewards of the rapid advances in AI.
Heron’s system can automate time-consuming manual workflows end-to-end, completing tasks automatically or flagging edge cases for human review. That reliability has led many customers to fully offload entire processes to Heron — freeing up their teams to focus on critical work.
For example, SMB lenders employ teams of underwriting analysts that spend hours on repetitive intake work — scanning email inboxes for submissions, downloading and renaming files, checking packet completeness, manually entering data into CRMs, and running basic eligibility checks. Using Heron, these hours of work can be accomplished in seconds, and with higher accuracy, full auditability, and no manual overhead.
This focus on reliability and solving problems end-to-end has attracted more than 150+ customers to Heron, including insurance carriers and FDIC-insured banks, and enabled the company to process over 350,000 documents per week. One lender cut submission-to-decision time by 60%, while an insurer used Heron to automate over 80% of its inbound submission triage.
“Anyone who tells you they use AI to automate work with 100% accuracy is probably lying to you. Instead of chasing accuracy, we focus on clearly understanding where our software is successful and where humans still need to review. This allows customers to use Heron in situations where millions of dollars are at stake and reap the rewards of the AI revolution in a reliable fashion that drives business outcomes,” said Johannes Jaeckle, co-founder and CEO of Heron
Founded in 2020 by Dom Kwok, Jamie Parker, and Johannes Jaeckle, Heron launched out of Y-Combinator’s Summer 2020 batch, initially building products for financial services companies with earlier generations of AI in the pre-ChatGPT era. The company eventually landed on a core insight: traditional industries weren’t waiting for flashy new tools — they were drowning in unstructured data, and paying millions of dollars a year to deal with it. In 2023, as LLMs matured, Heron pivoted to focus on AI document workflow automation. With minimal outside capital, the team tripled annualized revenue in 2024 and has continued to expand its presence in insurance and specialty finance this year.
“Heron’s AI models with vertical specific context automate the end-to-end data processing workflow, enabling automation and driving competitive differentiation in industries where speed to decisioning is of the essence,” said Philine Huizing, Managing Director at Insight Partners. “Heron’s founding team—Johannes, Jamie, and Dom—are an experienced trio that has proven their ability to adapt and execute. We’re thrilled to partner with them and the entire Heron team as they continue to scale up.”
The new capital will be used to scale Heron’s presence in insurance, equipment finance and SMB lending, while expanding into adjacent verticals that have shown demand for Heron’s solution. The company plans to grow its engineering and go-to-market teams in New York and London, and continues to invest in internal AI Tooling to enable a small team to serve more and more customers.
“We’ve proven we can win in one segment,” said Jaeckle. “Now we’re going workflow by workflow, industry by industry — giving people hours back in their day by eliminating time-intensive manual work.”
About Heron
Heron automates document-based workflows across industries like lending, insurance, and equipment finance. By turning unstructured documents into structured, actionable data, Heron helps companies process information faster, more accurately, and with less manual effort. Heron is based in New York and London, with the team bringing a wealth of experience from top-tier tech companies including Facebook, Spotify, N26, Revolut and Taptap Send.
Learn more at herondata.io
About Insight Partners
Insight Partners is a global software investor partnering with high-growth technology, software, and Internet startup and ScaleUp companies that are driving transformative change in their industries. As of December 31, 2024, the firm has over $90B in regulatory assets under management. Insight Partners has invested in more than 800 companies worldwide and has seen over 55 portfolio companies achieve an IPO. Headquartered in New York City, Insight has offices in London, Tel Aviv, and the Bay Area. Insight’s mission is to find, fund, and work successfully with visionary executives, providing them with tailored, hands-on software expertise along their growth journey, from their first investment to IPO. For more information on Insight and all its investments, visit insightpartners.com or follow us on X @insightpartners.
As IRS Announces Pause of ERC Payouts, Businesses May Resume Pursuit of Upfront Alternatives
September 14, 2023 Across the web on internet forums such as Reddit, business owners accustomed to telling ERC filing war stories are starting to worry that their checks might not be coming any time soon.
“I spoke with an agent today. She said they received an organization-wide email to stop processing ERC for the time being,” one user reported at the end of August. Some users replied to say that it wasn’t true. But it is.
On July 26, IRS Commissioner Danny Werfel said that the IRS had cleared its backlog of valid ERC claims and is now “intensifying compliance work and putting in place additional procedures to deal with fraud in the program.”
“The further we get from the pandemic, we believe the percentage of legitimate claims coming in is declining,” Werfel said.
The IRS later confirmed to the Wall Street Journal that it had in fact slowed its processing of claims. There’s some truth in the assertion that the IRS had cleared out a major backlog before doing this.
In late June, for example, those same internet forums were abuzz with happy check recipients and a rush of optimism that the era of long processing wait times was coming to a close. The shift in sentiment had implications. For Finance ERC, a company that provides business owners with cash upfront in return for buying their future ERC receivables, the impact was immediate.
“[Early in] the summer we saw tremendous demand in our origination levels, April, May, and June, of companies coming to us with the mindset that the IRS was taking too long so they wanted to sell their ERC credit rather than wait,” said David Goldin, a Managing Member of Finance ERC. “And then we saw in our portfolio, which is large checks flowing in from the IRS all at once over the summer, and then we saw our demand for new customers fall off a cliff.”
The IRS cranking out checks had made people reconsider not wanting to wait.
“Psychologically, customers then would say, ‘why would I finance it, I’m going to be getting my check any day, my friend got his check, this one got his check…'”
But since then IRS checks slowed to a crawl, intentionally. And for all the talk about clearing the backlog, there were still 637,000 unprocessed 941-X forms (adjusted quarterly tax forms necessary for the credit) as of September 6th, not to mention that under current law, 2020 tax returns can be amended until April 2024, and 2021 returns can be amended until April 2025.
On September 14th, the IRS upped the ante of a delay to a total pause for new claims. “New claims for the employee retention credit, or ERC, won’t be processed until at least 2024,” the WSJ reported. The headline leaves little room for misinterpretation: IRS Shuts Door on New Pandemic Tax Credit Claims Until at Least 2024.
 All of which means that business owners are now back to the waiting game and potentially back to considering upfront solutions. For Finance ERC, the company saw interest suddenly pick up and then accelerate since the first WSJ story came out.
“So I’m not saying the day that article came out, but we’ve definitely seen a spike in demand,” Goldin said. “My thing would be that for anyone that was selling [ERC financing], to think about that again, or those that weren’t selling it and they’re feeling that the MCA market is struggling, it’s too competitive, this is a new opportunity.”
Goldin shared this prior to the news breaking that the delay of ERC payouts had completely paused. Presumably, it would only make businesses more interested in getting the financing.
As he previously told deBanked, Finance ERC’s product requires no payments, can be eligible for up to 4-6x of what they would otherwise qualify for with an MCA, and can get it at a fraction of the cost of an MCA. But offering it can’t be done as an afterthought, he explained, even if you’re a big company with a big merchant portfolio.
“…you send out one or two emails you might as well not even send them out at all,” Goldin said.” Unless you’re actually embracing the product in your ecosystem, you know, drip marketing, follow up, you literally have to have a separate team selling it or it won’t work. But the guys that have done it, I know a few MCA guys that have, they’ve crushed it on both filing and funding. They’ve set up a separate group, separate sales guys, and they’re really killing it.”
And so the previous frontier of financing the ERC could now also be the next frontier yet again because of what’s taking place. On one subreddit, now that the reality is setting in, the tone has shifted.
“Has anyone tried contacting their state representative about the delay in refund?” The user began. He then adds that he’s already been waiting a whole year.
Alternative Finance Bar Association Event is Wednesday
September 10, 2017If you’re interested in going, the Alternative Finance Bar Association event on Wednesday is open to both funding company executives and industry attorneys. The New Regulatory Challenges Facing Small Business Lending: Navigating the New Frontier will feature Joann Needleman, Esq., Jane Luxton, Esq. & Tommy Brooks, Esq. from Clark Hill PLC in the NYC Bar Association Offices on 42 West 44th Street in New York City.
To register or for more information, contact Tiffany Diaz at Tiffany@LRohanlaw.com.
The original announcement can be accessed here.
It’s Here: Artificial Intelligence Changes MCA Broker’s Business, Improves Bank Underwriting and Debt Collection
November 22, 2016In this age of man versus the machine, the case for artificial intelligence and machine learning does not need many vociferous advocates.
Some predict that revenues from fintech startups using AI and predictive models is set to jump by 960 percent or to $17 billion by 2021. We might be closer to that number than we think, considering 140+ AI startups raised a total of $958M in funding in Q3’16, alone.
While healthcare, cybersecurity and advertising are frontiers of AI innovation, the growth and momentum of big data in finance (spurred by online lending) is fast bringing fintech to the forefront. In lending, specifically, data has become the new currency. It’s not so much that lenders didn’t use data for decision making earlier, but the data available then, wasn’t as rich or as extensive. A loan approval decision that just required a decent FICO score and assessment of character has expanded to include data points like a business’ social media presence, reviews, and owners’ background history.
Today, artificial intelligence in fintech has grown to tackle cybersecurity threats, act as a personal assistant, track credit scores and perform sentiment analysis to predict risk — making automated underwriting just the tip of the iceberg for what artificial intelligence and machine learning can do for the financial services industry. deBanked spoke to three fintech upstarts that have taken AI beyond underwriting.
AI Assist
 When Roman Vinfield started his ISO, Assure Funding in early 2015 with 16 openers, five chasers and three closers, little did he know that a business intelligence software would replace 85 percent of his staff for the same productivity. He stumbled onto Conversica, a AI-powered virtual sales assistant and was convinced to give it a try.
“I hadn’t heard anything like an artificial-intelligence sales assistant,” said Vinfield. “The results we got within a month of using it were unbelievable.” Within the first month, Vinfield made $35,000 in revenues by spending just $4,000 and eventually reduced his staff of 24 to 4 people. He was so sold on its potential for the merchant cash advance industry that after prolonged negotiations, he secured the rights to be the exclusive reseller of the software, and called it AI Assist. The software is now used by leading MCA companies like Yellowstone, Bizbloom and GRP Funding.
While Conversica’s clientele includes auto and tech giants like Oracle, Fiat, Chrysler and IBM, for the financial services industry, it’s marketed and sold to MCA and lending companies through AI Assist. It integrates easily with CRM software like Salesforce and creates a virtual sales assistant avatar that tracks old leads and reestablishes engagement. In the lead generation race, where a 3-5 percent response rate could be considered good, the response rate for Conversica has been 38 percent.
Designed to be akin to a human sales assistant, Conversica’s technology can determine a lead’s interest based on the response and set up a conversation with the sales department to follow up. “Your Conversica virtual assistant is an extremely consistent, personable and tireless worker. She doesn’t get sick and never needs a break. She never gets discouraged, and she improves with each engagement,” says the AI Assist website.
 True Accord
Personal chat assistants for money management and sales is one of the popular modes of AI implementation in fintech, given it’s scalability in lending for functions like debt collection. One company that does this, is True Accord. True Accord, similar to AI Assist uses automation software to schedule and send messages to customers by the company’s “Automated Staff”
The San Francisco-based company was founded by Ohad Samet who has over 11 years of machine learning experience in finance. The idea came to Samet while he was working as a chief risk officer at payments and e-commerce company Klarna, underwriting loans worth $2 billion. “While working at Klarna, I realized how big a piece debt collection is and I did not like the way it was done,” said Samet. “I needed machine learning to change it.”
Samet founded True Accord in 2013 to develop a debt collection AI assistant and today the company works with leading banks, credit card companies and food delivery services and has collected over half a billion dollars. It establishes targeted communication with the customer less frequently than traditional collection agencies and allows customers to pay their dues over mobile, which accounts for 35 percent of collections for the company.
“We humans don’t want to accept it but the reality is that, when it comes to scale, machines make better decisions than humans,” said Samet. “Machines are consistent, they are not tired, not angry, don’t fight with the significant other and all of this makes for better accuracy, better cost structure and better returns of scale.” While this might be true, building an efficient, compatible and compliant model is harder than it might seem.
James.Finance
 Since AI tools do not come in a one-size-fits-all package, its application can be as varied as the range of companies that use it. Building an AI framework that aligns with a company’s targets while being compliant to regulatory mandates can be an uphill task.
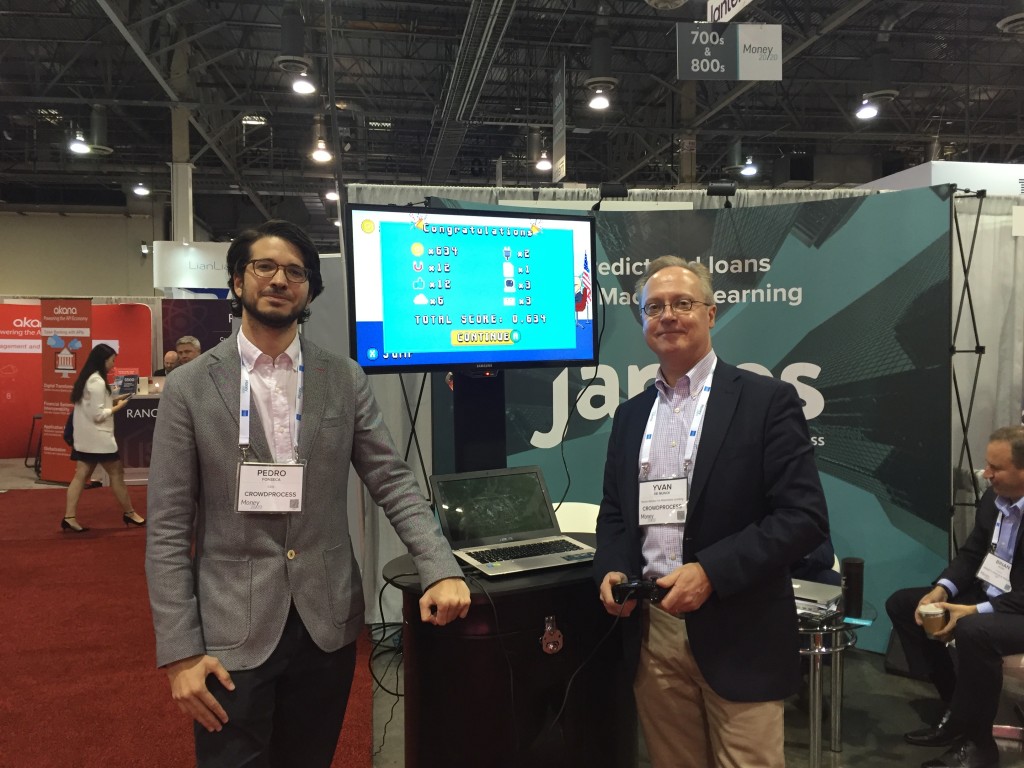
Recognizing this opportunity, James.Finance, a Portugal-based startup is using artificial intelligence to help financial institutions like banks build their own credit scoring models. Founder and CEO Pedro Fonseca, describes James as a “narrow AI” for a specific purpose of guiding risk officers to build machine learning models that follow regulatory compliance.
The startup works with consulting agencies or partners to reach out to banks. It offers a trial run of the software, which it calls a ‘jumpstart,’ where a risk officer is provided with James’ technology and in 24 hours, he or she will have to beat it with their in-house AI software.
“And we are consistently able to beat the models,” said Fonseca. The company won the startup pitch at Money 20/20 in Copenhagen earlier this year after receiving an uproarious response in Europe. Fonseca wants to divert his attention to the US’s fragmented banking market, which is dotted with smaller banks and credit unions. “The US is a perfect target for us. We are looking to work with local consultancies that know the problems of a bank intimately.”
As these entrepreneurs vouch for it, the current state of AI use in fintech is just the tip of the iceberg. And anything man can do, machines can do faster and better, right?
News from the Space
November 18, 2013 American Express recently teamed up with Heartland Payment Systems to provide split-processing loans tied to all card transactions rather than just American Express exclusively. The max loan size is $750,000. Prior to this deal American Express and other merchant cash advance companies rarely competed head-to-head. Unless a small business was processing substantial AMEX, they weren’t a candidate for American Express Merchant Financing. I expect them to make similar deals with other card processors.
Lending Club got a valuation boost with a $57 million investment from Yuri Milner’s DST Global and Coatue Management LLC. They’re now worth about $2.3 billion. They are expected to go public in 2014 which will be especially significant given their plans to enter the small business lending space as early as January. Today, alternative small business lenders worth tens of millions or hundreds of millions of dollars are the big shots in the industry. Expect major disruption if Lending Club achieves an IPO valuation in the tens of billions.
Zazma put their own spin on lending by financing the purchases small businesses make. Funds are actually wired directly to the suppliers instead of to the borrower. For now they are only doing up to $5,000 at one time, which is typically the minimum sized deal for the merchant cash advance industry.
ISO&Agent published a great article about merchant cash advance titled, Taming the Wild Frontier.
The end of the year is coming and Capital Access Network, which is now CAN Capital projects they will finish with $800 million in transactions for 2013. 15 years after they started, they are still the biggest in the business.